
Many businesses have had the experience of a business owner who has just looked at his or her P&L statement and realized that his or her business has made money for him or her last month. But he or she has payroll due on Friday and the money in his or her account will not be there to meet the obligations.
His or her customers owe him or her hundreds of thousands of dollars that they just have not paid invoices that are due. But a supplier wants them to pay up front for a contract and a quarterly tax payment comes due that week and despite the fact that their business made money, some ways they are broke.
The problem is that profits are not the same as cash flow. Profits tell you how much money your business makes you over time and cash flow tells you if money is coming in before it goes out.
You can have a profitable business but if your customers pay slowly, your inventory is tying up cash, and large payments are coming due before you have received payments for your product or service you can have a profitable business that finds itself constantly in need of cash.
Expert Perspective
This guide explains what cash flow is, why managing it matters, six practical ways to improve it, and a simple projection format you can use in your own business.
The good news is that cash flow is not completely random. There are a few levers that impact cash flow and the keys to cash flow management are understanding how these levers impact cash flow and knowing how and when to use them. The six practices that follow will show you how you can use the levers of budgeting horizon, collection speed, spending speed, inventory, debt structure, and contingency funds.
The strongest cash flow lever looks different depending on what you sell. For a service business, it's almost always collections: invoicing the day work is delivered, shortening terms, and following up before an invoice goes stale. For a product business, it's inventory, because every dollar sitting in unsold stock is a dollar you can't use for payroll or growth. Owners often work on the wrong lever for their model and wonder why cash stays tight.
Ankit Sagatani, MBA, B.Com · LinkedInWhat is Cash Flow?
Cash flow is the movement of money into and out of your business over a period of time. Positive cash flow means more cash came in than went out. Negative cash flow means the opposite, and it can happen even in a profitable month if customers are slow to pay or big expenses come due at once.
Cash flow is usually grouped into three categories. Operating cash flow comes from your core business activity, such as customer payments, supplier bills, and payroll. Investing cash flow comes from buying or selling long-term assets like equipment. Financing cash flow covers loans, loan repayments, and money put in or taken out by owners or investors.
Why Cash Flow Management Matters
Running out of cash is one of the most common reasons small businesses fail, and often it happens to businesses that are profitable on paper. Profit doesn't pay the rent. Cash does.
Here's how the gap appears. Say a business invoices $200,000 in a month, collects only $80,000 of that, and pays $150,000 in expenses. The business looks profitable because it billed more than it spent, but it's $70,000 short in cash that month.
Cash flow management is about closing that gap: getting customer payments in faster, timing outgoing payments sensibly, and keeping a reserve for the months when timing doesn't work in your favor.
Best Practice 1: Forecast Cash Flow Every Week
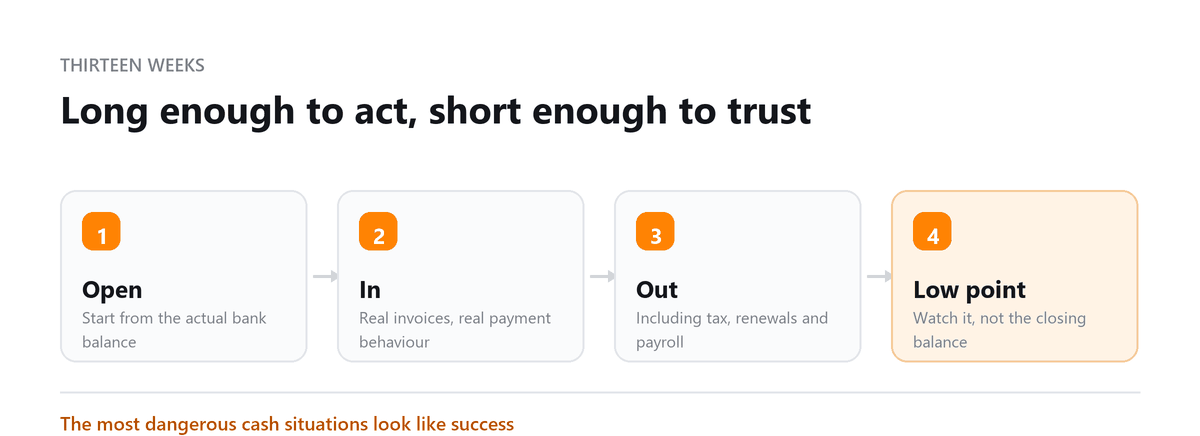
Build a 13-week rolling cash flow forecast. List every cash inflow you expect, based on when customer invoices are actually due, and every outflow, including supplier payments, payroll, rent, loan repayments, and tax payments, for the next 13 weeks.
Update it every week, rolling forward as each week passes. That gives you roughly 90 days of visibility and typically flags a shortfall four to six weeks before it happens.
That lead time is what matters. With a month's warning, you can push harder on collections, delay non-essential spending, talk to your bank, or draw on a credit line calmly rather than in a panic.
Best Practice 2: Tighten Accounts Receivable
Invoice Immediately
Send invoices as soon as the work is delivered or the product ships, not at the end of the week or month. Every day an invoice waits to go out is another day before it gets paid.
Shorten Payment Terms Where You Can
If Net 30 is your default, consider whether Net 15 or Net 20 would work, especially for new customers. Even a small change across your customer base can make a noticeable difference to cash.
Automate Payment Reminders
Set up reminders to go out a few days before an invoice is due, on the due date, and about a week after it's overdue. Automation keeps follow-up consistent without adding to anyone's workload.
Make It Easy to Pay
Accept ACH, credit cards, and online payment links. The fewer steps a customer has to take, the faster the money tends to arrive.
Review Receivables Every Week
Check your accounts receivable aging report weekly. Anything more than 30 days past due deserves a personal call or email, not just another automated reminder. The older an invoice gets, the harder it is to collect.
Best Practice 3: Manage Expenses Proactively
Review Subscriptions Every Quarter
Software, memberships, and service subscriptions pile up quietly. Once a quarter, go through them and cancel anything unused or underused.
Negotiate Better Supplier Terms
Moving a key supplier from Net 15 to Net 30 improves your cash position without costing you anything, as long as you keep paying on time. Strong payment history makes that conversation much easier.
Pay Suppliers in Batches
Instead of paying bills as they arrive, pay suppliers on a set weekly or biweekly schedule. It gives you a clearer view of cash going out and lets you time payments within their terms.
Require Approval for Significant Purchases
Use purchase orders or a simple approval step for anything above a set amount. It prevents unplanned spending and creates a record of who approved what.
Best Practice 4: Keep Inventory Lean
For product businesses, inventory is often the biggest drain on cash. Every unit sitting in a warehouse is money you've already spent and can't use for anything else until it sells.
Order based on actual sales velocity rather than optimistic forecasts. Where suppliers allow it, negotiate smaller, more frequent deliveries so you're not carrying months of stock. And track inventory turnover every month, by product where possible, so slow movers get spotted early.
What counts as healthy turnover depends heavily on your industry. Grocery and fresh goods turn many times a year, while furniture, machinery parts, or luxury goods turn far more slowly. Many retail and consumer product businesses use roughly four turns a year, or about three months of stock on hand, as a starting point, but the right benchmark is the one for your sector and your own trend over time.
Best Practice 5: Manage Debt Strategically
Debt isn't automatically bad for cash flow, but the structure matters.
A fixed-rate term loan with set monthly payments is predictable and easy to plan around. A revolving line of credit is more flexible, since you draw and repay as needed, but it takes discipline to avoid using it to cover ongoing losses rather than short-term timing gaps.
Keep an eye on your total monthly debt payments compared with your monthly revenue and operating cash flow. There's no universal cutoff, but if loan repayments are routinely squeezing payroll or supplier payments, it's a sign the debt load is too heavy for your cash flow. At that point, it's worth talking to your lender about refinancing, extending terms, or consolidating.
Best Practice 6: Build and Maintain a Cash Reserve
A cash reserve is your buffer against everything the forecast can't predict: a slow month, a major customer paying late, an equipment breakdown, or a seasonal dip.
Many businesses aim for three to six months of operating expenses. The right amount depends on how predictable your revenue is and how seasonal the business is.
Build it steadily. Move a set share of monthly profit, often 5 to 10 percent, into a separate account until you reach your target, then top it up whenever you draw on it. Keeping it in a separate account makes it much less tempting to spend.
Small Business Cash Flow Projection
A basic monthly cash flow projection structure:
| Line Item | Jan | Feb | Mar |
|---|---|---|---|
| Opening cash balance | $X | $X | $X |
| + Customer collections | $X | $X | $X |
| - Supplier payments | ($X) | ($X) | ($X) |
| - Payroll | ($X) | ($X) | ($X) |
| - Rent & fixed costs | ($X) | ($X) | ($X) |
| - Loan repayments | ($X) | ($X) | ($X) |
| - Tax instalments | ($X) | ($X) | ($X) |
| = Closing cash balance | $X | $X | $X |
| Reserve target | $X | $X | $X |
| Surplus / (Shortfall) | $X | $X | $X |
Book a free consultation and we will build the forecast with you.
Frequently Asked Questions
What is the difference between cash flow and profit?
Profit is revenue minus expenses, usually recorded when income is earned and costs are incurred, regardless of when money actually changes hands. Cash flow is the actual cash received minus the actual cash paid out in a period. That's why a profitable business can have negative cash flow if customers pay slowly or big expenses come due before revenue is collected.
What is a good cash flow for a small business?
A healthy position usually means consistently positive operating cash flow, where day-to-day operations bring in more cash than they use, plus a reserve of at least three months of expenses. The right dollar amount depends on your cost base. An extra $10,000 a month is strong for a business spending $50,000 a month, but thin for one spending $200,000.
How can I improve cash flow quickly?
The fastest improvements usually come from receivables. Send any unbilled invoices today, follow up personally on overdue accounts, and offer easy online payment options. On the spending side, pause non-essential purchases and ask key suppliers about longer payment terms. A 13-week forecast will then show where the remaining gaps are.
Should I offer customers a discount for paying early?
It can help, but it isn't free. A discount like 2/10 Net 30, which gives customers 2 percent off for paying within 10 days, is equivalent to an annualized cost of roughly 37 percent. That can be worth it if you're short on cash or would otherwise borrow at a higher rate, but for most businesses, faster invoicing and consistent follow-up are cheaper ways to speed up collections.
How often should a small business update its cash flow forecast?
Weekly is best, especially if cash is tight or the business is growing quickly. A 13-week forecast updated every week gives you enough warning to act on shortfalls. Businesses with very stable cash flow may manage with a monthly update, but weekly reviews tend to catch problems much earlier.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Cash Always Tight?
Book a free consultation and we will build the forecast with you.