
What is Accounting Profit?
Accounting profit is the financial gain a business generates after deducting all explicit costs from total revenue. Explicit costs are the out-of-pocket expenses that appear in the general ledger and are recorded in financial statements: cost of goods sold, operating expenses (salaries, rent, utilities, software), interest on debt, and depreciation on fixed assets. Accounting profit is what appears on the income statement as net income, the figure most business owners and investors focus on when assessing financial performance.
It is calculated using standardised accounting rules (GAAP or IFRS) and provides an objective, auditable measure of reported profitability.
Accounting profit is what you report to the IRS. Economic profit is what helps you decide whether to stay in this business or do something else with your time and capital. The two numbers tell completely different stories.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is Economic Profit?
Economic profit extends the concept of accounting profit by incorporating implicit costs, the opportunity costs of resources used in the business that do not appear in financial statements. Implicit costs include the salary the business owner could have earned working for someone else, the return on equity capital that could have been earned by investing the same funds in alternative assets, and the potential value of any other resources (such as property or intellectual capital) being used in the business instead of their next best alternative use.
Economic profit asks a more fundamental question than accounting profit: given everything the owner has committed to this business, time, capital, and other resources, is the return better than what they could earn elsewhere?
Formulas
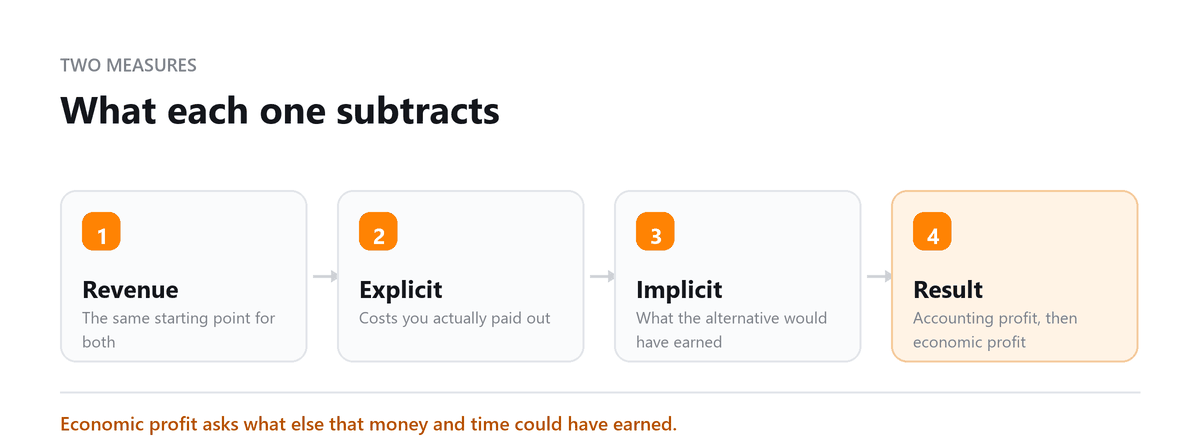
Accounting Profit = Total Revenue − Explicit Costs
Economic Profit = Accounting Profit − Implicit Costs
Or equivalently: Economic Profit = Total Revenue − Explicit Costs − Implicit Costs
Note that economic profit will always be less than or equal to accounting profit, because it subtracts an additional layer of costs, opportunity costs, that accounting profit does not recognise.
How to Calculate Each
Calculating accounting profit is straightforward: gather the income statement data, confirm that all explicit costs have been recognised under the applicable accounting standard, and read net income from the bottom of the statement. The process is objective and standardised.
Calculating economic profit is more nuanced because it requires estimating implicit costs through market analysis, and those estimates involve judgment. The owner must determine what they could realistically earn in alternative employment (using comparable market salary data), what the equity capital invested in the business could earn in an alternative investment of comparable risk (typically benchmarked against equity market returns or risk-adjusted returns on alternative projects), and the opportunity cost of any other committed resources.
Because these estimates vary with market conditions and individual circumstances, economic profit calculations are inherently more subjective than accounting profit.
Examples
Consider a bakery with the following figures for the year: total revenue of $100,000 and explicit costs (ingredients, rent, wages, equipment depreciation) totalling $70,000. Accounting profit is $30,000, a positive result that would show as net income on the income statement.
Now apply economic profit analysis. The owner estimates that working for a comparable bakery as a manager would have paid $5,000 more than the implicit return from the business. Economic profit = $30,000 − $5,000 = $25,000. The business is economically profitable, but only marginally so relative to the owner's opportunity cost. If the owner's forgone salary opportunity were $35,000, the economic profit would be negative, meaning the owner would be better off financially working for someone else, even though the business is reporting accounting profit.
Differences
| Factor | Accounting Profit | Economic Profit |
|---|---|---|
| Costs included | Explicit costs only | Explicit + implicit costs |
| Data source | Income statement | Income statement + estimates |
| Use case | Tax, reporting, compliance | Strategic decisions, investment analysis |
| Objectivity | Objective, standardized | Subjective (opportunity costs vary) |
| Long-run relevance | Short-term performance | Long-term value creation |
Additional Considerations
In economic theory, an economic profit of exactly zero is called 'normal profit', the point at which the business is earning precisely what its resources could earn in their next best alternative use. A business earning normal profit is covering all costs including opportunity cost and is therefore in long-run equilibrium. A negative economic profit, by contrast, signals that the resources committed to the business, the owner's time, equity capital, and other assets, would generate more value if redeployed elsewhere.
This is a common condition in small businesses and is an important consideration when evaluating whether to expand, pivot, or exit.
Conclusion
Accounting profit and economic profit answer fundamentally different questions about a business. Accounting profit, the figure on the income statement, tells you whether the business generated more revenue than it spent on explicit costs during the period. Economic profit tells you whether the business generated more value than the owner's resources could have earned in their best alternative use. Both measures are important: accounting profit is essential for compliance, reporting, and investor communication; economic profit is essential for long-run strategic decisions about resource allocation, business continuation, and investment.
Business owners who understand both metrics are equipped to make decisions that go beyond 'are we profitable?' to ask the more fundamental question: 'is this the best use of our time and capital?'
Book a free consultation and we will look past the P&L line.
Frequently Asked Questions
Can a business have positive accounting profit but negative economic profit?
Yes, this is more common than most business owners realise. If the owner could earn $120,000 working for someone else but only earns $80,000 in accounting profit from their business, the economic profit is negative. The business is technically profitable but not the best use of the owner's time and capital.
Why do economists care about economic profit while accountants focus on accounting profit?
Accountants measure what actually happened financially, transactions recorded in the books. Economists measure opportunity cost, what resources could have earned in their next best use. Both perspectives are valid but serve different analytical purposes.
Is economic profit used in financial statements?
No, economic profit is not a GAAP metric and does not appear in any formal financial statement. It's an analytical concept used in economics, strategic planning, and investment analysis.
What is 'normal profit' in economics?
Normal profit occurs when economic profit equals zero, meaning the business is earning exactly what it could in its next best alternative. It's the breakeven point for economic decision-making. Businesses earning normal profit are covering all costs including opportunity cost, but creating no excess value above that.
How should business owners use the concept of economic profit?
Use it when evaluating whether to continue, expand, or exit a business line. If a product line shows strong accounting profit but the same capital invested elsewhere would earn more, the economic profit may be negative, meaning reallocation would create more value.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want to Know Your Real Return?
Book a free consultation and we will look past the P&L line.