
Federal Tax on Retirement and Pension Income: What Retirees Need to Know
Overview: Retirement Income and Federal Tax, Social Security Benefits: 0-85% Taxable, and Traditional IRA and 401(k)
Retirement income is not taxed uniformly. What you pay depends on which account the money came from, what was contributed, and what else you received in the same year.
That last point is the one most often missed. Drawing from one account can change how another source is treated in the same year, which makes the order of withdrawals a planning decision rather than an administrative one.
This covers how each kind of retirement income is treated, how social security interacts with the rest, what required withdrawals mean in practice, and how withholding should be set.
Overview: Retirement Income and Federal Tax
Retirement income is not all treated the same by the IRS. The tax treatment depends on the source: Social Security, traditional vs Roth accounts, pension (employer-funded vs employee-contributed), and Required Minimum Distributions.
The order accounts are drawn down in can change the outcome considerably, because what is taken in one year affects how other income is treated in the same year. It is a planning question that has to be settled before the withdrawals, not a filing question.
Anu Gupta, CA, EA, B.Tech · LinkedInSocial Security Benefits: 0-85% Taxable
Social Security benefits may be taxable at the federal level depending on your 'combined income' (also called provisional income):
Combined Income = Adjusted Gross Income + Non-taxable interest + 50% of Social Security benefits
| Filing Status / Combined Income | Taxable SS Benefit |
|---|---|
| Single: under $25,000 | 0% of SS taxable |
| Single: $25,000 - $34,000 | Up to 50% of SS taxable |
| Single: over $34,000 | Up to 85% of SS taxable |
| MFJ: under $32,000 | 0% of SS taxable |
| MFJ: $32,000 - $44,000 | Up to 50% of SS taxable |
| MFJ: over $44,000 | Up to 85% of SS taxable |
Pro Tip: Roth IRA distributions do not count toward combined income, making Roth conversions a powerful tool for reducing SS taxation. IRA withdrawals do count, manage them strategically.
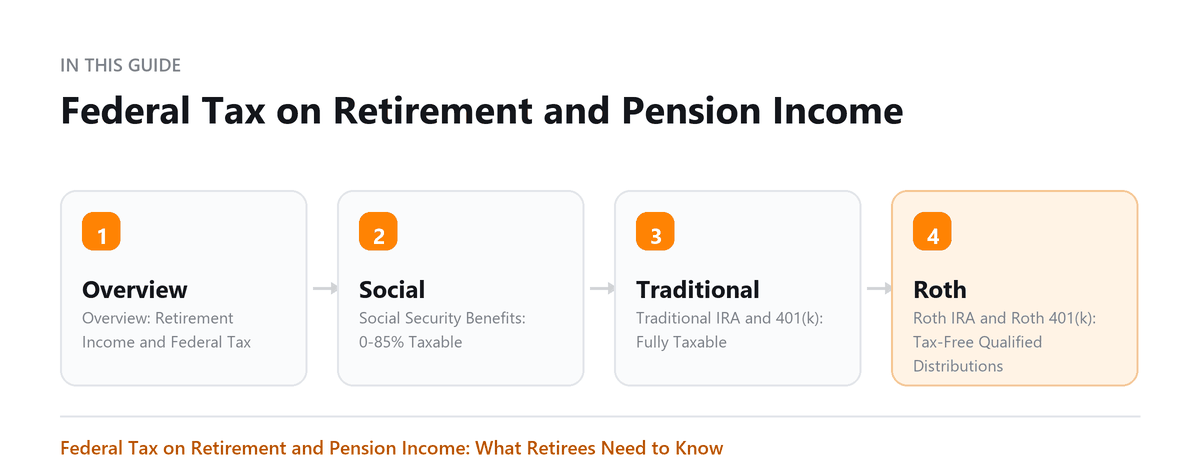
Traditional IRA and 401(k): Fully Taxable
All withdrawals from traditional (pre-tax) IRAs and 401(k)s are taxable as ordinary income:
- Taxed at your marginal federal income tax rate in the year of withdrawal
- No capital gains treatment, even if the underlying investments generated capital gains
- 10% early withdrawal penalty if under age 59.5 (with exceptions: disability, substantially equal periodic payments, certain medical/education expenses)
- Mandatory withholding: 20% if paid directly from a 401(k) (rollover avoids this); 10% default for IRA (can waive)
Roth IRA and Roth 401(k): Tax-Free Qualified Distributions
Qualified distributions from Roth accounts are completely tax-free at the federal level:
- Account must be at least 5 years old (5-year rule)
- Taxpayer must be 59.5 or older, disabled, or deceased
- Contributions (not earnings) can always be withdrawn tax-free and penalty-free
- Roth 401(k) does not have to be rolled over to avoid RMDs, but it is advisable since Roth IRAs have no RMDs during the owner's lifetime (SECURE 2.0 also eliminated Roth 401(k) RMDs)
Pension Income: Taxability Depends on Contributions
How your pension is taxed depends on whether you made after-tax contributions:
- Fully employer-funded pension: 100% of each payment is taxable as ordinary income
- Partially employee-contributed (after-tax): use the Simplified Method (or General Rule) to determine the taxable vs non-taxable portion of each payment
- Government pensions: same rules apply; state taxability varies
Required Minimum Distributions (RMDs)
The IRS requires you to begin taking minimum distributions from traditional retirement accounts:
| Item | Rule |
|---|---|
| RMD start age | Age 73 (SECURE 2.0, effective 2023); will rise to 75 starting in 2033 |
| Accounts subject to RMD | Traditional IRA, SEP IRA, SIMPLE IRA, traditional 401(k), 403(b), 457(b) |
| Accounts NOT subject to RMD | Roth IRA (owner lifetime); Roth 401(k) after SECURE 2.0 (2024 onward) |
| Penalty for missing RMD | 25% excise tax on the shortfall (reduced to 10% if corrected timely) |
| Qualified Charitable Distribution (QCD) | Up to $105,000/year directly from IRA to charity, counts toward RMD, not included in AGI |
Withholding on Retirement Income
Retirees often underpay taxes because withholding is not automatic:
- Form W-4P: submit to pension payer or IRA custodian to request withholding from pension/IRA payments
- Form W-4V: submit to Social Security Administration to request voluntary withholding (7%, 10%, 12%, or 22%)
- Estimated tax payments: if withholding is insufficient, file quarterly estimates (Form 1040-ES) to avoid underpayment penalty
Book a free consultation and we will take the return off your desk.
Frequently Asked Questions
Is all my 401(k) withdrawal taxed?
Yes, if all contributions were pre-tax (traditional 401(k)), every dollar withdrawn is ordinary income. If you made after-tax contributions, those contributions come back tax-free.
At what income level do Social Security benefits become taxable?
The formula uses combined income. Once combined income exceeds $25,000 single / $32,000 MFJ, up to 50% of SS is taxable. Above $34,000 single / $44,000 MFJ, up to 85% is taxable.
What states do not tax retirement income?
Florida, Texas, Nevada, Alaska, Washington, Wyoming, South Dakota, New Hampshire, and Tennessee have no state income tax. Many other states offer partial or full exemptions on Social Security or pension income.
Does the order in which accounts are drawn down matter?
It can matter a great deal, because different accounts are treated differently and because what is drawn in a year affects how other income is treated. The result is that two people with identical savings can end up with materially different outcomes depending on sequence. It is a planning question rather than a filing one, which means it has to be addressed before the withdrawals rather than at the return.
What should be reviewed each year rather than set once?
The withholding, the beneficiary designations, and whether anything has changed in the rules. Withholding set years ago against a different income level is a common cause of an unexpected balance. Beneficiary designations sit outside a will and are the most frequently overlooked document in the whole plan. The rules themselves also move, so confirm the current position each year rather than assuming continuity.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Want the Filing Handled?
Book a free consultation and we will take the return off your desk.