
Spending almost all of each payment before the next arrives is not primarily a low-income problem, which is what makes it so persistent.
It is a structural one. Without a buffer, every unexpected expense goes on credit, and the repayments on that credit consume the money that would have built the buffer.
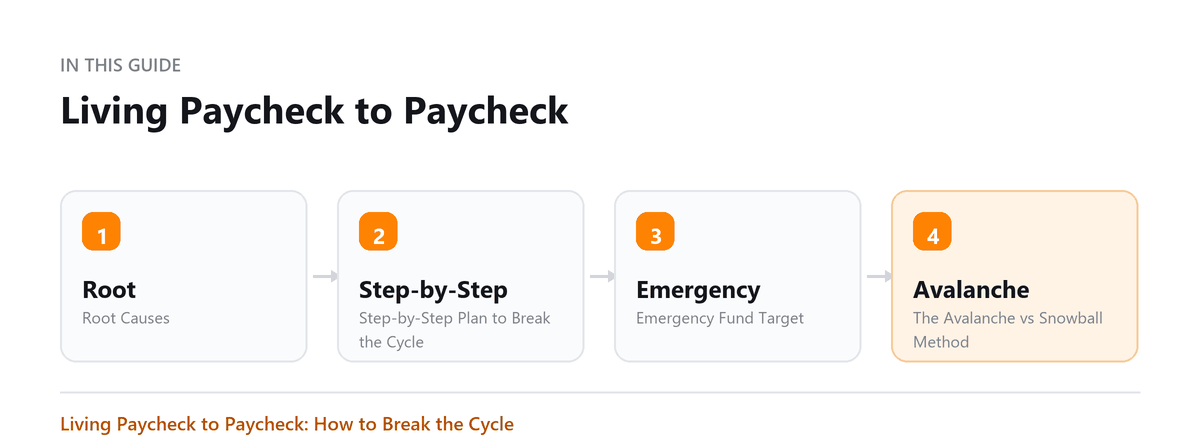
This covers what causes the cycle, a step-by-step way out of it, how large a buffer needs to be before it changes anything, and the two approaches to clearing debt and when each suits.
Living paycheck to paycheck means spending almost all of each paycheck before the next one arrives, leaving no buffer for emergencies, unexpected expenses, or savings. It is not always a low-income problem, many high earners live paycheck to paycheck due to lifestyle inflation and debt.
Root Causes
| Root Cause | What It Looks Like |
|---|---|
| Insufficient income vs expenses | Income does not cover basic needs at current cost of living |
| No budget or spending awareness | Spending happens on autopilot; surprises at month end |
| Lifestyle inflation | Income grows but spending grows faster |
| High-interest debt | Credit card minimums consume discretionary income |
| No emergency fund | Every car repair or medical bill requires a credit card or loan |
Start with one month of actual figures rather than a plan. Almost everybody underestimates two or three categories of regular spending, and the gap between what people believe they spend and what they do is usually where the whole problem sits.
Abhinav Gupta, CPA, CA, MBA · LinkedInStep-by-Step Plan to Break the Cycle
- Track every dollar for 30 days. Before cutting anything, know where the money goes. Use a free app (Mint, YNAB, or a simple spreadsheet). Categorise every transaction.
- Build a $1,000 starter emergency fund. This is your circuit breaker, it means the next unexpected expense does not go on a credit card. Cut non-essential spending temporarily to build it fast.
- List all debts: balance, interest rate, minimum payment. Sort by interest rate (highest first).
- Attack the highest-interest debt first (avalanche method). Pay minimums on all others. Direct every extra dollar at the highest-rate debt until it is gone.
- Once high-interest debt is paid, build a full 3-6 month emergency fund.
- Automate savings: set up automatic transfers on payday so savings happen before discretionary spending.
- Find income gaps: side income, overtime, or career advancement can accelerate the process if expenses are already lean.
Emergency Fund Target
| Life Situation | Target Fund |
|---|---|
| Single income, stable job | 3 months of essential expenses |
| Dual income household | 3 months of essential expenses |
| Variable income / freelance | 6 months of essential expenses |
| Single income with dependents | 6 months of essential expenses |
The Avalanche vs Snowball Method
| Method | How It Works |
|---|---|
| Avalanche | Pay off highest interest rate debt first. Mathematically optimal, pays less total interest. |
| Snowball | Pay off smallest balance first. Psychologically motivating, builds momentum with quick wins. |
Pro Tip: If you have a debt with an interest rate above 20% (most credit cards), every dollar you put toward it earns a guaranteed 20%+ return. This is better than almost any investment.
Building the Buffer Back
Breaking the cycle and staying out of it are two different problems. The plan above addresses the first. The second is about what happens after the debt is cleared, and it is where most people quietly return to where they started.
The mechanism that works is making the saving happen before the money is available to spend. A transfer that leaves the account on the day income arrives is treated as a fixed cost; one made at the end of the month from whatever remains is made only in the months when something remains, which are the months it mattered least. The amount is far less important than the automation.
The second habit is protecting the buffer from ordinary spending by keeping it somewhere with a small amount of friction: a separate account, ideally at a different institution, without a card attached. Its purpose is the unexpected expense that would otherwise go on credit, which is precisely the event that restarts the cycle.
- Automate the transfer for the day income arrives, and start with an amount small enough that you will not reverse it
- Keep the buffer separate from day-to-day money, with enough friction that reaching it is a decision
- Increase the transfer whenever income rises, before the higher figure becomes the new normal
- Rebuild it deliberately after it is used, treating that as the next priority rather than a background intention
Book a free consultation and we will take the return off your desk.
Frequently Asked Questions
Is it possible to save while paying off debt?
Yes, but prioritise the $1,000 starter emergency fund before aggressive debt payoff. Without a small buffer, every emergency goes back on the credit card, undoing your progress.
What if my income simply does not cover my fixed expenses?
The equation only balances two ways: reduce expenses or increase income. Start by auditing fixed expenses (housing, car, insurance) for potential reductions. If that is not enough, focus on income growth.
How long does it take to break the paycheck-to-paycheck cycle?
With discipline and an average income, most people can build a $1,000 emergency fund in 1-3 months and become meaningfully debt-free in 2-5 years. The timeline varies widely based on the debt load and income gap.
Where should someone start if the situation feels unmanageable?
With a single month of actual figures rather than a plan. Almost everybody underestimates two or three categories of regular spending, and the gap between what people believe they spend and what they do is usually where the problem is. One month of recording every payment, without changing anything, produces a more useful starting point than any budget built on estimates.
Does this change anything about how tax should be handled?
It changes the timing rather than the amount, and that matters more than people expect. Someone with no buffer is badly exposed to an unexpected balance at the end of the year, so checking that withholding matches the actual position, rather than discovering a shortfall in filing season, is worth doing early. Where income is irregular or self-employed, setting money aside as it arrives is the protection.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Want the Filing Handled?
Book a free consultation and we will take the return off your desk.