
What is SaaS Accounting?
SaaS accounting is the process of recording, interpreting, and analyzing financial data for subscription-based software companies. It is fundamentally distinct from traditional business accounting because of the recurring revenue models, deferred revenue recognition, and usage-based billing structures that define the SaaS business model.
Where a traditional business records revenue when a product is sold, a SaaS company must recognize revenue gradually over the period in which service is delivered making accounting significantly more complex from day one.
Most SaaS founders understand their MRR intuitively. Where I see the accounting break down is deferred revenue, when a customer pays for a year upfront, that's a liability on your balance sheet, not revenue. Mishandling that makes your financials misleading to investors and the IRS.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhy is SaaS Accounting Important?
SaaS accounting provides financial clarity for subscription dynamics that standard bookkeeping simply cannot handle. Investors, lenders, and acquirers evaluate SaaS companies on metrics that are invisible in a conventional income statement, metrics like monthly recurring revenue, churn rate, and customer lifetime value. Without SaaS-specific accounting, founders and finance leaders are flying blind on the numbers that matter most to valuation and growth planning.
How is SaaS Accounting Different from Non-SaaS Companies?
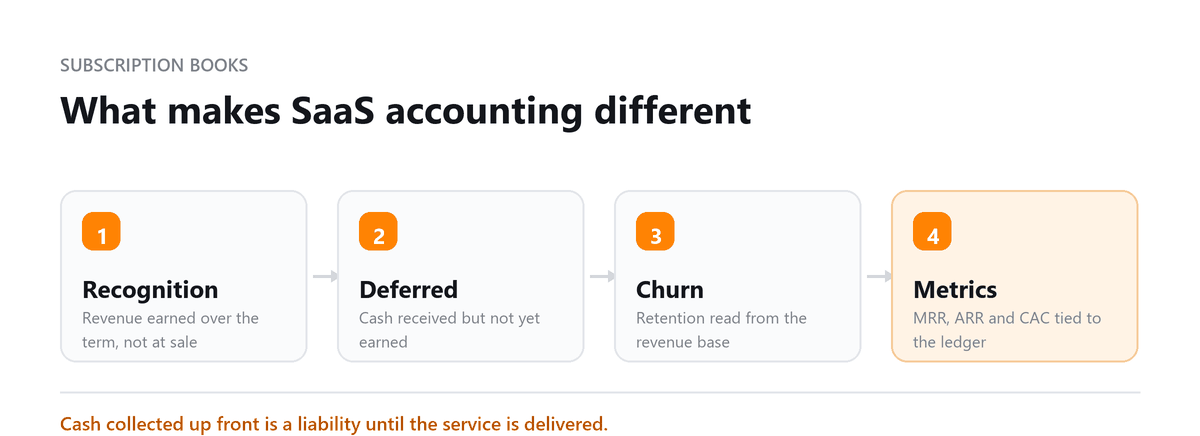
The core differences come down to revenue timing and reporting. A traditional business recognizes revenue at the point of sale. A SaaS business receives cash upfront but must recognize it ratably over the service period, meaning the balance sheet carries a deferred revenue liability until each portion of service is earned. SaaS companies also report on metrics like MRR, ARR, and churn that do not appear in standard financial statements, and they must follow ASC 606 revenue recognition rules that govern when and how subscription revenue can be recorded.
Types of SaaS Accounting
SaaS accounting encompasses several interrelated functions, all adapted for the subscription context: general ledger management for recording all financial transactions; accounts payable automation for managing vendor payments and software subscriptions; accounts receivable automation for billing, collections, and renewal tracking; payroll accounting for employee compensation; project accounting for tracking costs by product or initiative; and tax accounting for federal, state, and international compliance. Each of these functions requires SaaS-specific adaptations, particularly around how recurring revenue and deferred revenue flow through the books.
What are the SaaS Accounting Rules?
The governing framework for SaaS revenue recognition is ASC 606 (Revenue from Contracts with Customers), which establishes a five-step model: (1) Identify the contract with a customer; (2) Identify the performance obligations in the contract; (3) Determine the transaction price; (4) Allocate the transaction price to the performance obligations; and (5) Recognize revenue when (or as) the entity satisfies a performance obligation. For a SaaS subscription, this typically means recognizing revenue ratably over the subscription term as the software service is delivered.
ASC 606 operates within the broader GAAP framework, which governs all U.S. financial reporting.
Best Practices in SaaS Accounting
Master Revenue Recognition
Apply ASC 606 rigorously from the first subscription dollar. Recognize subscription revenue ratably over the service period, not when cash is received. If a customer pays $12,000 for an annual subscription in January, you recognize $1,000 of revenue per month, not $12,000 in January. Getting this wrong creates misleading financials and significant problems during due diligence or an IRS audit.
Keep Your Subscription Management Tight
Track monthly recurring revenue, annual recurring revenue, upgrades (expansions), downgrades (contractions), and churned revenue as separate line items. This granularity is what allows you to calculate net revenue retention, the metric that distinguishes a healthy SaaS business from one with a leaky bucket.
Separate Deferred Revenue
Cash received for future service periods must sit on the balance sheet as a current liability (deferred revenue) until it is earned. This is not optional, it is an accounting requirement under ASC 606 and GAAP. Mixing deferred revenue with earned revenue inflates your income statement and understates your liabilities.
Monitor Burn Rate and Runway
For VC-backed SaaS companies, burn rate and runway are existential metrics. Monthly cash burn (total cash outflows minus cash inflows) divided into current cash balance gives you runway in months. Finance teams should model burn rate scenarios monthly, not just report historical actuals, so leadership can see the impact of hiring decisions, marketing spend, and revenue trajectory on cash position.
SaaS Financial Reporting and Key Metrics
The following metrics are the foundation of SaaS financial reporting. Investors and board members will expect fluency with all of them:
| Metric | What It Measures | Why It Matters |
|---|---|---|
| MRR (Monthly Recurring Revenue) | Predictable monthly subscription revenue | Revenue baseline for forecasting |
| ARR (Annual Recurring Revenue) | Annualized subscription revenue | Investor valuation benchmark |
| CAC (Customer Acquisition Cost) | Cost to acquire one customer | Efficiency of sales/marketing spend |
| CLV (Customer Lifetime Value) | Total revenue from one customer | Validates CAC investment |
| Churn Rate | % of subscribers cancelling | Core health indicator |
| Burn Rate | Monthly cash expenditure | Runway calculation |
Top Cloud-Based SaaS Accounting Software for 2026
The right accounting software depends on your SaaS company's size, complexity, and growth stage. Here are the leading platforms:
| Software | Best For | Key SaaS Feature |
|---|---|---|
| QuickBooks Online | Small SaaS, early-stage | Recurring invoices, bank feeds |
| Xero | Growing SaaS teams | Multi-user, 1,000+ integrations |
| FreshBooks | Founder-managed SaaS | Subscription billing tracking |
| Zoho Books | Budget-conscious SaaS | Full suite with CRM integration |
| Sage Intacct | Mid-market SaaS | ASC 606 compliance, multi-entity |
How Profitjets Helps SaaS Companies
Profitjets provides outsourced accounting specifically built for SaaS businesses. That means ASC 606-compliant revenue recognition, MRR and ARR tracking, deferred revenue management, and investor-ready financial reporting, all delivered by accountants who understand the SaaS model, not generic bookkeepers applying traditional accounting rules to a subscription business.
A SaaS founder contacted us eight months into their first ever annual contract. They were beyond confused since their cash on hand was positive but according to their Profit and Loss statement, they were spending money.
Their problem was that in their P&L, for the January of the new year, they recorded a $60,000 annual deal in January, collected the full payment upfront, and immediately booked the entire $60,000. All signs pointed to a prosperous year ahead, but in fact, the company only had liabilities for the next eleven months and no revenue recorded for the following months.
We managed to sort out their books for them, changing the revenue per month to 5,000 and recording the rest as deferred revenue. After that, we explained to the confused founder why exactly did their P&L said that they were spending money in February.
One of the most prominent investors from their seed round contacted them six weeks later asking about their deferred revenue schedule. We, at Revenue Analytics, made sure they responded to the investor with confidence, probably securing the deal for them.
Conclusion
SaaS accounting is not a variation on standard bookkeeping, it is a specialized discipline built around recurring revenue, deferred recognition, and subscription-specific metrics. Getting it right from the start means clean financials for fundraising, accurate tax compliance, and the visibility to make better business decisions. Getting it wrong means expensive corrections, audit exposure, and financial statements that don't reflect reality.
Book a free consultation and we will set revenue recognition up correctly.
Frequently Asked Questions
Why is deferred revenue such an important concept for SaaS businesses?
When a SaaS customer pays 12 months upfront, you haven't yet delivered all 12 months of service. Under ASC 606, you can only recognize revenue as service is delivered, typically 1/12th per month. The remaining unearned amount sits as a liability (deferred revenue) on your balance sheet until it's earned.
What is the difference between MRR and ARR?
MRR (Monthly Recurring Revenue) is the normalized monthly value of all active subscriptions. ARR (Annual Recurring Revenue) is simply MRR x 12. ARR is the standard metric for investor conversations and company valuation; MRR is more useful for month-to-month operational tracking.
Does a SaaS company need accrual accounting?
Yes, cash basis accounting cannot properly handle deferred revenue, prepaid expenses, or subscription revenue recognition. Accrual accounting (and specifically ASC 606 compliance) is essential for SaaS companies, especially those seeking investment or preparing for acquisition.
What is a healthy churn rate for a SaaS business?
For B2B SaaS, annual churn below 5% is considered strong. Monthly churn below 0.5% is the benchmark for enterprise SaaS. Consumer SaaS has higher acceptable churn (3-8% monthly) due to shorter subscription cycles. High churn undermines even strong new-customer growth.
When should a SaaS company hire a dedicated accountant?
From the moment you recognize your first subscription revenue, especially if you have multiple subscription tiers, trial periods, or annual prepayments. ASC 606 compliance is complex; errors in early-stage revenue recognition create expensive problems during due diligence or an audit.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Running a Subscription Business?
Book a free consultation and we will set revenue recognition up correctly.