The first time a small business owner has heard of “EBITDA” is likely to be attached to something important. A lender, considering a loan application, or a broker, thinking about buying a share in the company, or even an investor, can turn a small business owner’s thoughts to this mysterious acronym.
It appears to be an intimidating term, and it most certainly comes with its own set of complications, which may be attached to a high value, too.
EBITDA stands for Earnings Before Interest, Taxes, Depreciation, and Amortisation. Essentially, it is a figure obtained by adding several costs to the bottom line, costs that are dependent on the method of financing, taxation system, and the way the company accounts for depreciation.
The result is used to value a company, and it is a helpful indicator because it equalises profits of a firm that may have substantially different levels of debt.
While it may give a misleading impression of the company’s finances, it is a useful tool in showing how much a company is worth. It is important to keep in mind that EBITDA is a figure obtained by ignoring several significant expenses, and a business owner who relies on it exclusively risks making a deal based on faulty premises.
The gap I see most often between EBITDA and cash is in growing businesses. EBITDA looks healthy, the owner expects the bank balance to follow, and it doesn't.
When we reconcile the two, the missing cash is sitting in receivables that grew with sales, inventory bought ahead of demand, equipment purchases, and loan principal payments, none of which show up in EBITDA.
The fix is a simple monthly bridge: start with EBITDA, subtract working capital growth, capital spending, debt repayments, and taxes, and see what cash is actually left. That number tells you far more about what you can afford.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhat Is EBITDA?
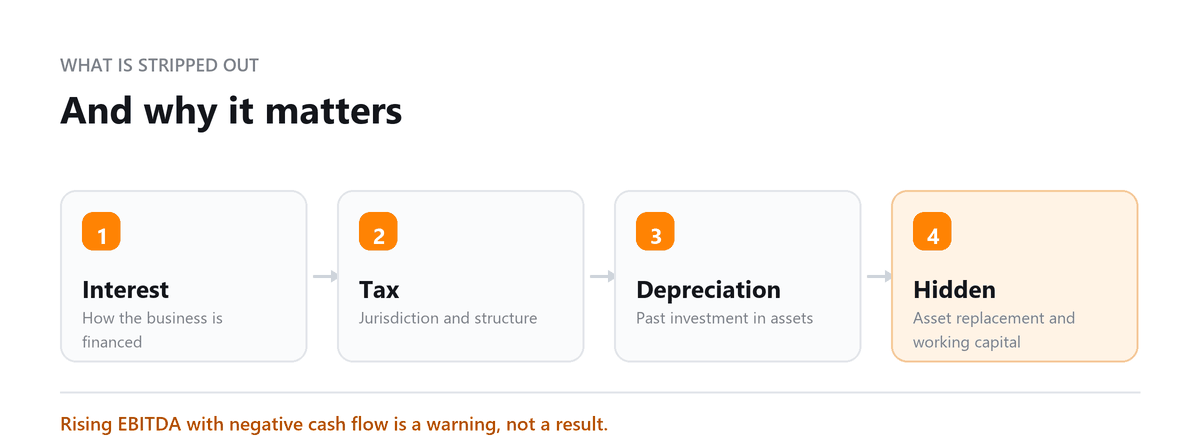
EBITDA removes four items from net income:
| Removed Item | Why It's Removed |
|---|---|
| Interest | Reflects financing structure (debt vs equity), not operational performance, two identical businesses with different debt loads show different net incomes |
| Taxes | Varies by jurisdiction, tax elections, and prior-year credits, not comparable across entities |
| Depreciation | Non-cash charge for historical capital expenditure, a fully depreciated machine still produces the same output |
| Amortization | Non-cash write-down of intangible assets (goodwill, patents, customer lists) from acquisitions |
How to Calculate EBITDA
Two equivalent methods:
Method 1: Starting from Net Income
EBITDA = Net Income + Interest + Taxes + Depreciation + Amortization
Example from live page: Revenue $1,000,000
| Item | Amount |
|---|---|
| Net Income | $200,000 |
| + Interest Expense | $15,000 |
| + Income Tax Expense | $30,000 |
| + Depreciation | $20,000 |
| + Amortization | $10,000 |
| = EBITDA | $275,000 |
Method 2: Starting from Operating Profit (EBIT)
EBITDA = Operating Profit (EBIT) + Depreciation + Amortization
This is simpler when D&A is broken out separately on the income statement.
EBITDA Margin
EBITDA Margin = EBITDA / Total Revenue x 100
Example: $275,000 / $1,000,000 = 27.5%. EBITDA margin normalises profitability so you can compare across companies of different sizes.
Industry EBITDA Margin Benchmarks
| Industry | Typical EBITDA Margin Range | Notes |
|---|---|---|
| SaaS / Software | 15 to 35% | High once past early growth; scales with recurring revenue |
| Professional Services (consulting, legal, accounting) | 20 to 35% | Low capex, high margin if utilisation is strong |
| Retail (physical goods) | 3 to 8% | High COGS and rent compress margins |
| Manufacturing | 8 to 15% | Varies by automation level and commodity input prices |
| Healthcare / Medical Clinics | 10 to 20% | Staffing costs are the primary driver |
| Restaurants | 10 to 15% | Food and labour cost control is critical |
| E-commerce (product-based) | 5 to 15% | Depends heavily on brand vs commoditised products |
| Construction | 8 to 12% | Project-based variability; working capital intensive |
These ranges are indicative starting points. Check them against benchmarks for your own sub-sector before drawing conclusions.
EBITDA vs Other Profit Metrics
| Metric | What It Includes / Excludes | Best Used For |
|---|---|---|
| Gross Profit | Revenue minus COGS only | Pricing efficiency and production cost management |
| Operating Profit (EBIT) | After operating expenses; before interest and tax | Core operating performance including D&A |
| EBITDA | Before interest, tax, D&A | Cross-company comparison; acquisition valuation; lender analysis |
| Net Income | After everything, interest, tax, D&A | Bottom-line profit; dividend capacity; EPS |
Limitations of EBITDA
- Ignores capex requirements, a company spending $500K/year on equipment replacement is not as profitable as EBITDA implies
- Can be gamed, companies with aggressive acquisition strategies inflate EBITDA through amortisation exclusions
- Does not equal cash flow, working capital changes (receivables growing, payables shrinking) consume cash that EBITDA does not capture
- Warren Buffett famously called depreciation 'the worst kind of expense' to exclude, it represents real economic consumption of assets
CLIENT QUOTE: Our EBITDA looked healthy, so we were surprised that cash was getting tighter every month. Profitjets reconciled our operating cash flow and showed that accounts receivable had increased by nearly $300,000, meaning a large part of the profit we were reporting hadn't actually been collected. We tightened our collections process and started tracking receivables alongside EBITDA so we could see the difference between accounting profit and cash generation.
Book a free consultation and we will build a defensible schedule.
Frequently Asked Questions
Is a higher EBITDA always better?
Within the same industry, a higher EBITDA margin usually means more efficient operations. Across industries, comparisons are less meaningful, because capital needs and cost structures differ so much. Also check whether strong EBITDA actually turns into cash after equipment spending, debt payments, and working capital needs.
Can EBITDA be negative?
Yes. Negative EBITDA means the business's operating costs, before depreciation and amortisation, are higher than its revenue. The core operations lose money before interest or taxes are even considered. It's common in early-stage companies spending heavily on growth, and a serious warning sign in an established business.
What's the difference between EBITDA and adjusted EBITDA?
Adjusted EBITDA adds back further items the business considers unusual or non-recurring, such as a one-time legal settlement, owner compensation above market rate, or relocation costs. It's widely used when selling a business. Buyers and lenders scrutinise each adjustment, so every add-back should be clearly documented and genuinely non-recurring.
Why do lenders and buyers use EBITDA?
It gives them a quick, comparable view of operating earnings before financing and tax decisions. Lenders use it to judge how much debt a business can support. Buyers often value businesses as a multiple of EBITDA or adjusted EBITDA. Both usually look at cash flow and capital needs as well.
Is EBITDA the same as operating cash flow?
No. Operating cash flow accounts for actual cash movements, including changes in receivables, inventory, and payables, as well as interest and taxes paid. EBITDA does not. A growing business can have strong EBITDA and weak operating cash flow at the same time.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Preparing the Business for Sale?
Book a free consultation and we will build a defensible schedule.