
Selling an investment at a profit feels straightforward until tax season. Two people can make the same $20,000 gain on the same stock and owe completely different amounts. One pays nothing. The other pays thousands. The difference usually comes down to two things: how long each person held the investment, and how much other income they had that year.
That's what makes capital gains tax so worth understanding. Unlike wages, which run through the ordinary brackets no matter what, gains on assets held for more than a year get their own lower rates, and some taxpayers pay 0 percent on part or all of those gains. Sell a day too early, or in a year when your other income is unusually high, and the same profit can cost far more.
For business owners, the stakes are often larger. Selling equipment, a rental property, or the business itself can involve depreciation recapture, special rates on real estate, and decisions about how the sale price is allocated. Those details can matter as much as the headline rate.
Expert Perspective
This guide explains what counts as a capital gain, how short-term and long-term gains are taxed, the current rates, how gains are calculated, special rules for homes, real estate, and business assets, and practical ways to reduce the tax.
The capital gains issue business owners overlook most is what happens to depreciation when they sell. They've written off equipment or a building for years, then sell it and assume the whole gain gets the low capital gains rate. It doesn't.
Part of it comes back as depreciation recapture, taxed at ordinary rates or up to 25 percent for real estate. When you're selling a business, how the price is split between equipment, goodwill, and other assets can shift thousands of dollars between those rates, so it's worth negotiating with the tax result in mind, not after the deal is signed.
Anu Gupta, CA, EA, B.Tech · LinkedInWhat is a Capital Gain?
A capital gain is the profit you make when you sell or exchange a capital asset for more than its tax basis. If you sell for less than your basis, you have a capital loss.
Capital gain or loss = Sale price − Selling costs − Adjusted basis
Your adjusted basis usually starts with what you paid for the asset, including commissions and fees. It increases with capital improvements, such as a new roof on a rental property, and decreases with depreciation you've claimed.
Gains are generally taxed only when you sell. An investment that has risen in value but hasn't been sold, often called an unrealized gain, isn't taxed.
What Counts as a Capital Asset?
Most property you own for personal use or as an investment is a capital asset. That includes stocks, bonds, mutual funds, and ETFs, cryptocurrency and other digital assets, your home and other personal property, land and investment real estate held for appreciation, and collectibles like art, coins, and precious metals.
Some property isn't treated as a capital asset, even though it may be sold at a gain:
Inventory and property held for sale to customers, which produces ordinary income.
Depreciable property and real estate used in a business, which falls under special Section 1231 rules covered below.
Accounts receivable from the ordinary course of business.
Copyrights and creative works held by the person who created them, which generally produce ordinary income when sold.
Short-Term vs Long-Term Capital Gains
How long you held an asset determines which tax rates apply.
| Type | Holding Period | How It's Taxed |
|---|---|---|
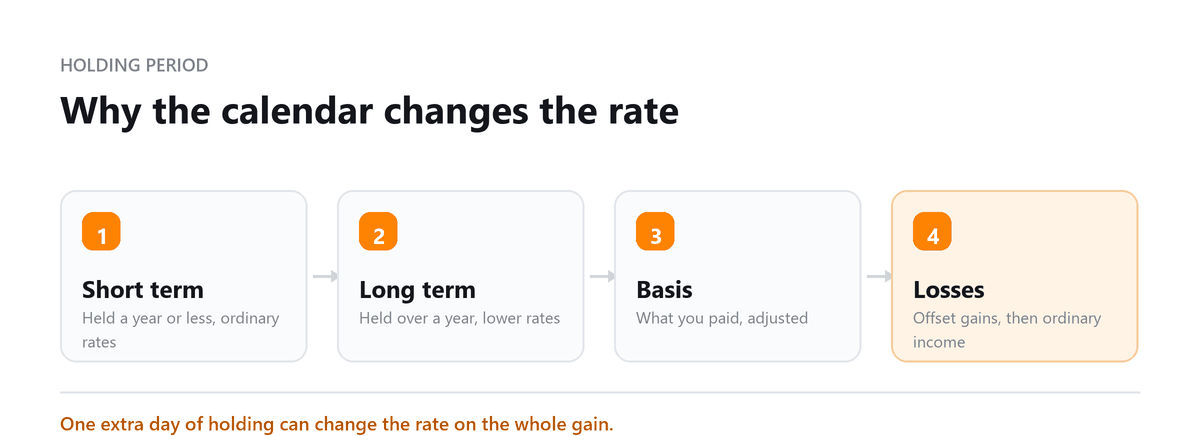
| Short-term | One year or less | As ordinary income, at rates from 10% to 37% |
| Long-term | More than one year | At 0%, 15%, or 20%, with some exceptions |
The holding period starts the day after you acquire the asset and includes the day you sell it. To qualify as long-term, you need to hold it for more than one year. An asset bought on March 10, 2025 would need to be sold on March 11, 2026 or later.
Inherited property is always treated as long-term, no matter how briefly you or the person who died held it.
Long-Term Capital Gains Tax Rates
2026 Long-Term Capital Gains Rates
These thresholds apply to sales made during 2026, reported on returns filed in 2027.
| Rate | Single | Married Filing Jointly | Head of Household | Married Filing Separately |
|---|---|---|---|---|
| 0% | Up to $49,450 | Up to $98,900 | Up to $66,200 | Up to $49,450 |
| 15% | $49,451 to $545,500 | $98,901 to $613,700 | $66,201 to $579,600 | $49,451 to $306,850 |
| 20% | Over $545,500 | Over $613,700 | Over $579,600 | Over $306,850 |
2025 Long-Term Capital Gains Rates
Use these thresholds for sales made during 2025, including returns filed on extension through October 15, 2026.
| Rate | Single | Married Filing Jointly | Head of Household | Married Filing Separately |
|---|---|---|---|---|
| 0% | Up to $48,350 | Up to $96,700 | Up to $64,750 | Up to $48,350 |
| 15% | $48,351 to $533,400 | $96,701 to $600,050 | $64,751 to $566,700 | $48,351 to $300,000 |
| 20% | Over $533,400 | Over $600,050 | Over $566,700 | Over $300,000 |
These thresholds are based on your total taxable income, including the gain itself, not just the gain.
Special Long-Term Rates
A few types of long-term gains are taxed at higher maximum rates:
| Type of Gain | Maximum Rate |
|---|---|
| Collectibles, such as art, coins, stamps, and precious metals | 28% |
| Unrecaptured Section 1250 gain, which is the portion of gain on real estate from prior depreciation | 25% |
| Certain gains on qualified small business stock that aren't excluded | 28% |
Qualified dividends are taxed at the same 0, 15, and 20 percent rates as long-term capital gains.
How Capital Gains Are Taxed on Top of Other Income
Long-term capital gains are stacked on top of your ordinary income. Your wages, business income, and other ordinary income fill the brackets first, and your gains use whatever room is left in the 0 percent and 15 percent ranges.
Example: Single Filer, 2026
Jordan has $40,000 of ordinary taxable income after the standard deduction and sells stock held for three years at a $30,000 long-term gain. Total taxable income is $70,000.
| Portion of the Gain | Amount | Rate | Tax |
|---|---|---|---|
| Fills the rest of the 0% range, from $40,000 to $49,450 | $9,450 | 0% | $0 |
| Remaining gain, from $49,450 to $70,000 | $20,550 | 15% | $3,082.50 |
| Total tax on the gain | $30,000 | $3,082.50 |
That works out to about 10.3 percent of the gain. If Jordan had sold after holding the stock for only 11 months, the entire $30,000 would have been taxed as ordinary income, mostly at 12 and 22 percent, and the tax on it would have been roughly $5,600.
The Net Investment Income Tax
Higher earners may owe an additional 3.8 percent net investment income tax on top of the regular capital gains rate. It applies to the lesser of your net investment income or the amount by which your modified adjusted gross income exceeds these thresholds:
| Filing Status | Threshold |
|---|---|
| Single or head of household | $200,000 |
| Married filing jointly or qualifying surviving spouse | $250,000 |
| Married filing separately | $125,000 |
These thresholds aren't adjusted for inflation, so more taxpayers cross them each year.
Net investment income includes capital gains, dividends, interest, and most rental income. It generally doesn't include gain from selling assets used in a business you actively participate in, or the portion of a home sale gain excluded under the primary residence rules.
For someone in the top bracket, the combined federal rate on long-term gains can reach 23.8 percent.
Selling Your Home
If you sell your main home, you can exclude up to $250,000 of gain from income, or up to $500,000 for married couples filing jointly. To qualify, you generally must have:
Owned the home for at least two years during the five years before the sale.
Lived in the home as your main residence for at least two years during that same five-year period.
Not used the exclusion on another home sale in the two years before this sale.
The two years don't have to be continuous. For the $500,000 exclusion, either spouse can meet the ownership test, but both must meet the use test.
Gain above the exclusion is taxable, usually as long-term capital gain. If you claimed depreciation on the home, for example for a home office or while renting it out, the gain equal to that depreciation generally can't be excluded and is taxed at up to 25 percent. A loss on the sale of a personal home isn't deductible.
Capital Gains for Business Owners
Section 1231 Property
Depreciable property and real estate used in a business and held for more than a year, such as equipment, vehicles, and buildings, fall under Section 1231. The treatment is favorable: net gains for the year are generally taxed as long-term capital gains, while net losses are treated as ordinary losses that can offset other income.
Depreciation Recapture
When you sell business property you've depreciated, part of the gain may be recaptured.
Equipment, vehicles, and other personal property. Gain up to the amount of depreciation you've claimed, including Section 179 and bonus depreciation, is taxed as ordinary income.
Buildings and other real property. Gain from prior depreciation is generally taxed as unrecaptured Section 1250 gain at up to 25 percent, with any remaining gain eligible for regular long-term rates.
This is why expensing equipment immediately isn't free. The deduction you took early can come back as ordinary income when you sell.
Selling a Business
A business sale is rarely taxed as one single gain.
In an asset sale, which is common for sole proprietorships, partnerships, LLCs, and many S corporations, the price is allocated among the business's assets. Each piece is taxed according to its type: inventory as ordinary income, equipment with depreciation recapture, and goodwill usually as long-term capital gain.
In a stock sale of a corporation, the seller generally reports a single capital gain on the shares.
Buyers usually prefer asset purchases for the depreciation deductions, while sellers often prefer stock sales for simpler capital gains treatment. The final structure and allocation are negotiated, so bring in tax advice before terms are agreed.
Reporting Capital Gains
Most capital gains and losses are reported on Form 8949 and summarized on Schedule D of Form 1040. Brokers report sales of stocks and other securities on Form 1099-B, and digital asset brokers are phasing in reporting of their own.
Keep records that show your basis, including purchase confirmations, improvement receipts for property, and depreciation schedules. If basis isn't reported to the IRS or you can't prove it, you may end up paying tax on more gain than you actually made.
How to Reduce Capital Gains Tax
Hold Assets for More Than a Year
Qualifying for long-term treatment is often the single biggest saving. If a sale is close to the one-year mark, check the exact date before selling.
Harvest Losses
Selling investments that have lost value can offset capital gains. Losses first offset gains of the same type, then gains of the other type. If losses exceed gains, up to $3,000 a year, or $1,500 if married filing separately, can offset ordinary income, and any remaining loss carries forward indefinitely.
Watch the wash sale rule. If you buy the same or a substantially identical security within 30 days before or after selling it at a loss, the loss is disallowed for now and added to the basis of the new shares.
Time Sales for Lower-Income Years
Because long-term gains stack on top of ordinary income, selling in a year when your income is lower, such as after retiring or during a slow year for the business, can let more of the gain fall into the 0 percent or 15 percent range.
Use Tax-Advantaged Accounts
Trades inside a 401(k), traditional IRA, or Roth IRA don't create taxable capital gains. Placing investments you trade more often inside these accounts can reduce taxable gains in your regular brokerage account.
Give Appreciated Assets Instead of Cash
Donating long-term appreciated stock directly to a qualified charity generally lets you avoid tax on the gain and, if you itemize, deduct the fair market value, subject to income limits.
Consider an Installment Sale
When selling property or a business, receiving payments over several years can spread the gain across multiple tax years, which may keep more of it in lower brackets. Depreciation recapture is generally taxed in the year of sale, even with installment payments.
Use a Like-Kind Exchange for Real Estate
A Section 1031 exchange lets you defer gain when you sell investment or business real estate and reinvest in similar property, as long as strict identification and timing rules are met. It applies only to real property, not equipment or stocks.
Understand Basis at Death and in Gifts
Inherited assets generally receive a basis equal to their fair market value at the date of death, which can eliminate the gain built up during the original owner's lifetime. Gifted assets, by contrast, usually keep the giver's original basis. That difference can matter a lot when deciding whether to give appreciated property during life or leave it to heirs.
State Taxes on Capital Gains
Most states with an income tax treat capital gains as ordinary income, with no special lower rate. A few offer partial exclusions, and states without a personal income tax generally don't tax capital gains. Washington is a notable exception, with a separate tax on certain long-term capital gains above a high threshold. Check your state's rules alongside the federal calculation.
Conclusion
Capital gains tax isn't one rate. It depends on how long you held the asset, what kind of asset it was, and how much other income you had in the year of the sale. Long-term gains can be taxed at 0, 15, or 20 percent, while short-term gains are taxed like wages, and higher earners may add the 3.8 percent net investment income tax.
Business owners also need to plan for depreciation recapture and the way a sale is structured. Track your basis, watch holding periods, use losses and timing wisely, and get advice before a large sale, when there's still time to shape the outcome.
Book a free consultation and we will work out the timing and the tax.
Frequently Asked Questions
What is the capital gains tax rate for 2026?
Long-term capital gains are taxed at 0, 15, or 20 percent. For single filers, the 0 percent rate applies to taxable income up to $49,450, 15 percent up to $545,500, and 20 percent above that. Short-term gains on assets held one year or less are taxed as ordinary income at rates from 10 to 37 percent.
Do I owe capital gains tax when I sell my home?
Often not. If you owned and lived in the home as your main residence for at least two of the five years before the sale, you can exclude up to $250,000 of gain, or $500,000 for married couples filing jointly. Gain above that amount, and any gain tied to depreciation you claimed, is taxable.
How much in capital losses can I deduct?
Capital losses first offset capital gains in full. If losses exceed gains, you can deduct up to $3,000 a year against other income, or $1,500 if married filing separately. Unused losses carry forward to future years with no expiration.
What is the difference between short-term and long-term capital gains?
Short-term capital gains generally apply when you sell an asset held for one year or less and are taxed at ordinary federal income tax rates. Long-term capital gains generally apply to assets held for more than one year and may qualify for the lower long-term capital gains rates of 0%, 15%, or 20%, depending on taxable income and filing status.
How can I reduce my capital gains tax?
Common strategies may include holding an asset for more than one year to qualify for long-term capital gains treatment, using available capital losses to offset gains, and taking advantage of applicable exclusions or deductions. The right approach depends on the asset, holding period, income, and overall tax situation.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Selling an Asset This Year?
Book a free consultation and we will work out the timing and the tax.