
What is GAAP?
GAAP, Generally Accepted Accounting Principles, is the U.S. accounting rulebook. Developed and maintained by the Financial Accounting Standards Board (FASB), GAAP provides detailed, rules-based guidance for how U.S. companies must record and report their financial activity. GAAP covers revenue recognition (ASC 606), inventory valuation (including LIFO and FIFO methods), intangible asset accounting, lease treatment (ASC 842), financial statement presentation, and extensive disclosure requirements.
All U.S. publicly traded companies are required by the Securities and Exchange Commission (SEC) to report under GAAP. Most private U.S. companies also follow GAAP, either by choice, lender requirement, or investor expectation. GAAP's rules-based nature means there is detailed specific guidance for many industries and transaction types, which reduces ambiguity but also produces a very lengthy body of standards.
The GAAP vs IFRS debate matters most when you're raising capital internationally or planning a cross-border acquisition. For domestic U.S. operations, GAAP is the only real option. The bigger risk I see is companies misapplying GAAP because they don't understand where GAAP and IFRS differ.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is IFRS?
IFRS, International Financial Reporting Standards, is the global accounting framework developed and maintained by the International Accounting Standards Board (IASB). Currently adopted by more than 140 countries including the European Union, Canada, Australia, and the United Kingdom, IFRS provides a unified framework that allows financial statements to be compared across borders.
IFRS covers the same fundamental domains as GAAP, revenue recognition (IFRS 15), inventory (IAS 2), leases (IFRS 16), intangibles (IAS 38), and financial instruments (IFRS 9), but takes a more principles-based approach. Rather than prescribing specific rules for every scenario, IFRS establishes broad principles and requires companies to apply professional judgment to specific situations. This gives preparers more flexibility but also more responsibility for consistent, faithful application.
GAAP vs IFRS: Similarities
Despite their differences, GAAP and IFRS share a common foundation. Both standards embrace accrual accounting and the matching principle, revenues and expenses are recognised when earned or incurred, not when cash changes hands. Both aim for transparent, faithful representation of a company's financial position. Both focus on providing decision-useful information to investors, lenders, and other external stakeholders. Convergence efforts between FASB and IASB have also brought the two standards closer together on major topics like revenue recognition and lease accounting.
GAAP vs IFRS: Key Differences
| Area | GAAP | IFRS |
|---|---|---|
| Governing body | FASB (U.S.) | IASB (International) |
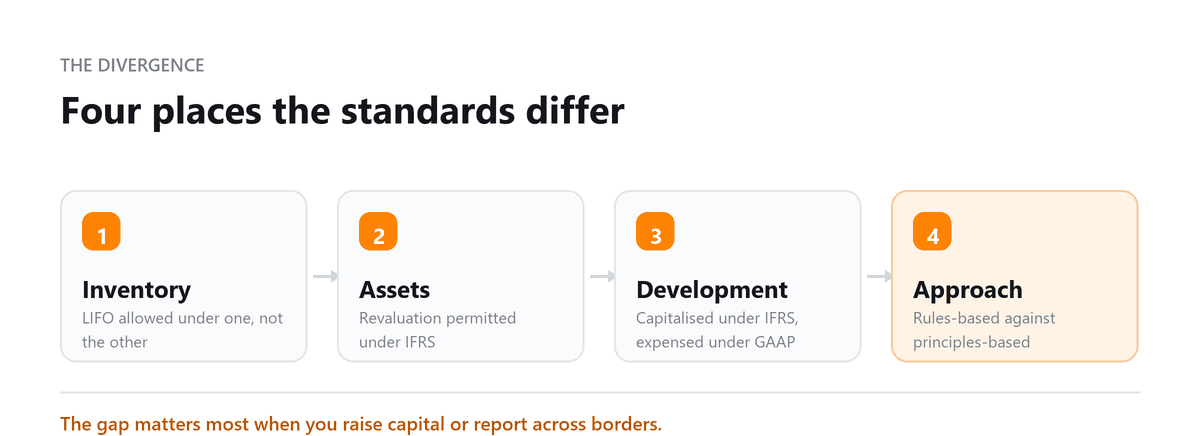
| Approach | Rules-based (detailed industry guidance) | Principles-based (flexible interpretation) |
| Inventory | LIFO allowed | LIFO prohibited |
| R&D costs | Always expensed | Development costs can be capitalised |
| Revenue recognition | ASC 606 (5-step model) | IFRS 15 (similar 5-step model) |
| Lease accounting | ASC 842 | IFRS 16 |
GAAP vs IFRS: Revenue Recognition
Revenue recognition was one of the most significant convergence achievements between FASB and IASB. Both ASC 606 (GAAP) and IFRS 15 use the same five-step model: identify the contract with a customer; identify the performance obligations within the contract; determine the transaction price; allocate that price to each performance obligation; and recognise revenue when (or as) each obligation is satisfied. The conceptual framework is nearly identical.
Where differences remain are in application guidance. GAAP includes significantly more industry-specific guidance, for software, real estate, entertainment, and other sectors, while IFRS relies on broader principles that companies apply to their specific circumstances. In practice, this can lead to different revenue recognition outcomes for the same transaction under each standard.
Choosing Between GAAP vs IFRS
For most U.S. businesses, the choice is straightforward: U.S. public companies registered with the SEC must report under GAAP, there is no option. Private U.S. companies are not legally required to follow GAAP, but most lenders, investors, and buyers expect GAAP-based financial statements and will request reconciliation if another basis is used.
IFRS becomes relevant for U.S. businesses in specific situations: if you have international operations that require local IFRS-based reporting, if you're seeking investment from overseas investors accustomed to IFRS, or if you're planning a cross-border acquisition or listing. Multinational companies often prepare GAAP financial statements for U.S. regulatory purposes and IFRS-based statements for international stakeholders.
The Future of GAAP and IFRS: Convergence or Divergence?
FASB and IASB launched their formal convergence project under the Norwalk Agreement in 2002, with the goal of producing a single set of high-quality global accounting standards. Significant progress was made, the aligned revenue recognition standards (ASC 606 / IFRS 15) and lease standards (ASC 842 / IFRS 16) are direct products of this collaboration. However, full convergence has not been achieved and is not imminent.
Key areas of divergence remain, most notably inventory accounting (GAAP permits LIFO; IFRS prohibits it) and certain financial instruments treatments. Political, regulatory, and economic differences between U.S. and international standard-setting environments make complete unification unlikely in the near term. The two bodies continue to coordinate on new standards but no longer pursue active convergence as a formal project.
Additional Considerations
Switching between accounting standards is not a trivial exercise. Transitioning from GAAP to IFRS (or vice versa) requires restating historical financial statements, retraining accounting staff, updating accounting systems and controls, and communicating changes to lenders and investors. The process typically takes 12 to 24 months and carries significant cost.
The choice of standard also affects key financial ratios. Companies using LIFO under GAAP will report lower inventory values and higher COGS during inflationary periods compared to IFRS companies using FIFO or weighted average. Debt-to-equity, return on assets, and inventory turnover ratios can all differ meaningfully between GAAP and IFRS companies in the same industry. Analysts comparing cross-standard companies must adjust for these structural differences.
Conclusion
GAAP and IFRS represent two distinct but equally rigorous approaches to financial reporting. For U.S.-based businesses, GAAP is the default and in many cases the only option. Understanding where the two standards diverge, particularly on inventory, R&D, and certain revenue situations, is essential for any business operating internationally, raising cross-border capital, or evaluating a foreign acquisition target.
Book a free consultation and we will tell you which standard applies where.
Frequently Asked Questions
Does my U.S. small business need to worry about IFRS?
Probably not if you operate only in the U.S., GAAP is the required standard. IFRS becomes relevant if you have foreign investors who expect IFRS-based reporting, you're considering a foreign acquisition, or you're preparing for a cross-border listing.
What is the biggest practical difference between GAAP and IFRS for inventory?
GAAP allows LIFO (Last In, First Out) inventory accounting, which can lower taxable income during inflationary periods. IFRS prohibits LIFO entirely. This means U.S. companies using LIFO would need to restate inventory values if they ever converted to IFRS.
Are GAAP and IFRS converging into one global standard?
Convergence efforts began in earnest in 2002 (Norwalk Agreement) and produced alignment on key areas like revenue recognition (ASC 606 / IFRS 15) and leases. Full convergence is unlikely in the near term due to political and economic differences between standard-setting bodies.
How does the choice of accounting standard affect financial ratios?
Different standards produce different balance sheet values for inventory, intangibles, and leases, directly affecting ratios like debt-to-equity, return on assets, and inventory turnover. Analysts comparing GAAP and IFRS companies must adjust for these differences.
Can a U.S. company voluntarily adopt IFRS?
U.S. public companies registered with the SEC must use U.S. GAAP. Private U.S. companies have more flexibility and technically could use IFRS, but most lenders and investors in the U.S. expect GAAP-based statements. Adoption of IFRS by private U.S. companies is rare.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Reporting Across Borders?
Book a free consultation and we will tell you which standard applies where.