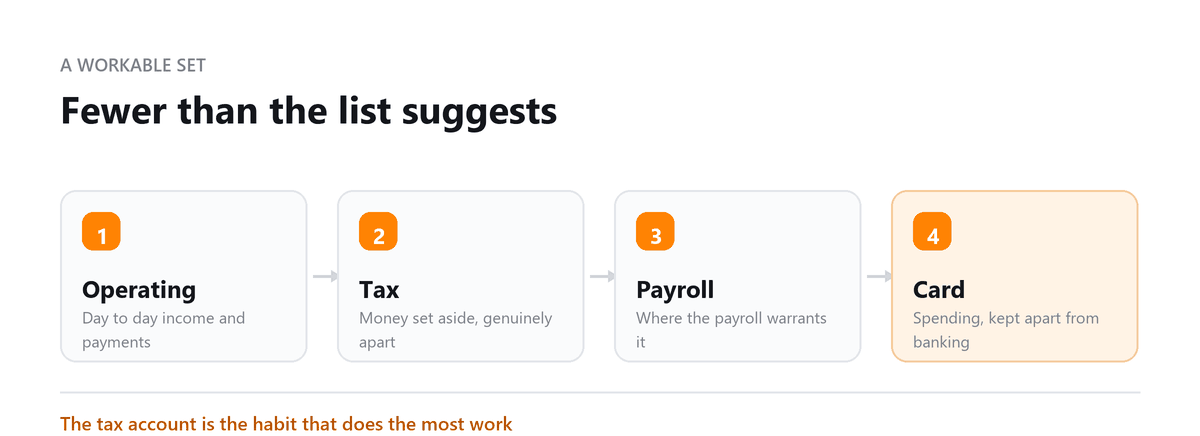
Most small businesses will need just one business bank account, and would benefit from a second. The other four types on this list exist, they're useful, and the vast majority of readers of this page will never open one.
Worth saying that plainly, because listicles on this topic tend to imply you're missing something by not holding a money market account and a sweep facility. You aren't, unless you have the cash balances that make them worth the setup.
This guide covers all six types of business accounts, what each actually does, and for each whether you're the business that needs it.
The underused one is the simplest: a second account for tax. Not a clever structure, just a savings account that a fixed percentage of every payment goes into the day it arrives. Businesses get caught short on quarterly estimates constantly, and it's almost never because they didn't earn enough. It's because the tax money was in the operating account and the operating account got spent. Separating it removes the problem entirely and costs nothing.
Ankit Sagatani, MBA, B.Com · LinkedInWhat makes an account a business account
A business bank account is held in a business entity's name rather than an individual's. It is subject to different fee structures, deposit insurance limits, and terms compared to personal accounts. Business accounts must be opened with business documentation (EIN, Articles of Incorporation, operating agreement).
All US business bank accounts at federally insured institutions carry FDIC insurance up to $250,000 per depositor per bank meaning your business deposits are protected up to that limit if the bank fails.
Fee structures and transaction limits differ from personal accounts, generally not in your favour. Deposit insurance works the same way:
One thing to establish before you assume coverage: several of the platforms small businesses now use aren't banks. They're fintech companies holding deposits at partner institutions, with insurance passing through that arrangement. It generally works, and it has failed the 2024 Synapse collapse left account holders without access to funds for an extended period.
Types of Business Bank Accounts
1. Business Checking Account
The core transaction account for day-to-day business operations. Used for: paying vendors, employees, and contractors; receiving customer payments; processing payroll; paying taxes; and managing operating expenses. Most businesses need at least one business checking account as their primary operating account.
- Best for: all businesses, this is the foundational account
- Key feature: unlimited (or high-volume) transactions; debit card access; ACH and wire transfer capability
- Typical cost: $0-$25/month (neobanks free; traditional banks charge $10-$25/month, usually waivable with minimum balance)
- Cost: free at several fintech providers; $10 to $25 monthly at traditional banks, usually waivable on a minimum balance.
- Should you have one: yes.
2. Business savings
A separate account for money you're deliberately not spending: tax reserves, an operating buffer, cash set aside for something specific.
This is the second account most small businesses should hold, and the tax reserve is the reason. Move a fixed share of every payment received into it the moment it arrives somewhere around 25 to 30% of net profit covers federal obligations for most owners, more where state income tax applies. The quarterly estimate is then already funded rather than being a negotiation with your operating balance.
The old six-withdrawal-per-month federal limit was lifted in 2020, though some institutions still apply their own. Not usually a constraint for a reserve account you're not touching.
- Yield: varies considerably by provider and rate environment.
- Should you have one: almost certainly, if you're setting aside for tax, which you should be.
3. Business money market
Sits between checking and savings. Typically better yield than a standard savings account, with limited cheque-writing or card access, and rates that tier upward with balance.
Relevant once you're holding meaningful idle cash, conventionally $25,000 or more, that you want earning something without locking it away.
Should you have one: only if you have that balance sitting idle. Below it, a savings account does the same job with less complexity.
4. Business certificate of deposit
Cash locked for a fixed term, three months to five years, at a fixed rate, with a penalty for early access.
Suits seasonal businesses parking off-season cash, or saving toward a known future purchase.
Best for: businesses with seasonal revenue who can lock away off-season cash, or businesses saving for a specific future capital expenditure
Two cautions before you consider one. If the business carries any revolving debt, a credit line, card balances, paying that down almost always beats a CD rate. And small business cash flow is less predictable than owners expect, so locking funds you turn out to need means paying a penalty to access your own money.
Should you have one: rarely, and not before you have a comfortable liquid reserve.
5. Merchant account
Not really a bank account in the sense the others are. It's the facility that lets you accept card payments funds pass through it before settling into your checking account, usually one to two business days later.
If you take cards, you have one, whether or not you think of it that way. Stripe, Square and similar providers bundle it into their service rather than presenting it separately.
- Best for: any business accepting card payments in person or online
- Cost: typically 1.5 to 3.5% per transaction all-in for card-present and online payments, which covers interchange, network fees and the processor's margin. What's worth checking is how your provider structures deposits some batch multiple invoices into one payout and net fees from the total, which creates reconciliation work every month.
- Should you have one: if you accept cards, yes, and you already do.
6. Business sweep account
A checking account that automatically moves surplus above a threshold into an interest-bearing account overnight, then back the next morning to cover payments.
The point is earning on cash that would otherwise sit idle overnight, without anyone managing transfers. Generally a premium feature at commercial banks, and generally only worth the setup with six-figure idle balances.
- Best for: high-cash-flow businesses wanting to maximise yield on idle overnight cash without manually managing transfers
- Should you have one: not until you're consistently holding well over $100,000 that isn't doing anything.
What most businesses actually need
One checking account, plus one savings account for tax.
That's it, for the large majority of businesses reading this. Add a money market when idle cash makes it worthwhile, consider a sweep at much larger balances, and treat CDs as a specific decision rather than a default.
If you're holding more than $250,000 at one institution, that's the point to think about spreading deposits across banks, or using an insured cash sweep programme that distributes across a network to extend coverage.
How to Open a Business Bank Account
Required documents for most US business bank accounts:
- EIN (Employer Identification Number) from the IRS
- Articles of Incorporation or Organisation (for LLCs and corporations)
- Operating Agreement (LLC) or Bylaws (corporation)
- Government-issued ID for each owner with 25%+ ownership
- Business address (registered agent address may suffice for neobanks)
Book a free consultation and we will restructure it with you.
Frequently Asked Questions
How many business bank accounts do I need?
One checking account at minimum. The setup worth aiming for is checking plus a savings account holding tax reserves, which solves the most common cash problem small businesses have. Beyond that, add accounts when a specific need arises separate revenue streams, a sweep facility at larger balances rather than because a list suggested it.
Is my business bank account insured?
If it's at an FDIC-insured bank, yes, up to $250,000 per depositor per bank. If you're using a fintech platform rather than a bank, coverage passes through a partner institution and depends on that arrangement functioning as intended which has failed before. Check how your provider holds deposits, and if you hold substantial balances, don't keep them all in one place.
Can I run everything through one account?
You can, and most of the risk isn't regulatory, it's that tax money and operating money become indistinguishable. Businesses get caught short on quarterly estimates because the reserve was spent on operations without anyone deciding to spend it. A separate savings account for tax prevents it and costs nothing.
Do I need separate accounts for separate businesses?
If they're separate legal entities, yes. Two LLCs sharing one account undermines the separation both entities depend on for liability protection. Separate DBAs under one sole proprietorship can share, though separate accounts make the bookkeeping considerably easier.
Which account should hold my tax reserve?
A plain business savings account. You want it separate enough that spending it requires a deliberate transfer, liquid enough to move on the quarterly due dates, and earning something while it sits. Money market accounts work too at larger balances; CDs don't, because the money is needed on fixed dates.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Banking Set Up Badly?
Book a free consultation and we will restructure it with you.