
For employees and employers in US, it is essential to adhere to the FICA tax requirements to ensure the accurate payroll process and avoid any federal penalties. In other words, the taxes cover social security and Medicare contributions that should be paid both by employees and employers at the rate of 7.65%. Moreover, a company owner can be held responsible for the Trust Fund Recovery Penalty in case of failing to comply with the law.
To avoid such undesirable outcomes and maintain the cash flow, it is crucial to keep track of the yearly changes and limits of wages and taxes.
FICA the Federal Insurance Contributions Act is the US law that requires both employees and employers to contribute to Social Security and Medicare through payroll deductions. FICA taxes are withheld from every employee's paycheck and matched dollar-for-dollar by the employer, funding the country's social insurance programmes.
For small business owners, FICA compliance is non-negotiable: failure to withhold and remit FICA taxes triggers the IRS Trust Fund Recovery Penalty, a personal liability that survives bankruptcy.
The single fastest way small business owners trigger a Trust Fund Recovery Penalty is treating withheld FICA taxes as short-term operating cash during tight revenue months, the IRS views unremitted payroll taxes as civil theft, not standard debt.
Ankit Sarawagi, CPA, CA, MBA · LinkedInFICA Tax Rates (2025/2026)
| Tax | Employee Rate | Employer Rate | Total Rate |
|---|---|---|---|
| Social Security | 6.2% | 6.2% | 12.4% |
| Medicare | 1.45% | 1.45% | 2.9% |
| Total FICA | 7.65% | 7.65% | 15.3% |
| Additional Medicare Tax | 0.9% (employee only above threshold) | 0% (employer does not match this) | 0.9% |
Social Security Wage Base
Social Security tax (6.2% employee + 6.2% employer) applies only up to the annual wage base. Once an employee's cumulative wages for the year exceed the wage base, Social Security tax stops is no longer withheld from that employee and the employer stops matching. Medicare tax (1.45% + 1.45%) has no wage base cap, it applies to all wages.
| Year | Social Security Wage Base |
|---|---|
| 2023 | $160,200 |
| 2024 | $168,600 |
| 2025 | $176,100 |
| 2026 | $184,500 |
Additional Medicare Tax (0.9%)
High earners pay an Additional Medicare Tax of 0.9% on wages above certain thresholds. The employer does NOT match this additional tax, only the employee pays it. Employers are required to withhold the additional 0.9% from wages once they exceed $200,000 in a calendar year, regardless of filing status. The thresholds at which the full additional tax applies (on combined income) vary by filing status:
| Filing Status | Additional 0.9% Medicare Threshold |
|---|---|
| Single / Head of Household / Qualifying Widow(er) | $200,000 |
| Married Filing Jointly | $250,000 |
| Married Filing Separately | $125,000 |
Important: Employers withhold based on the $200,000 single-employee threshold regardless of the employee's filing status. If an employee's additional tax obligation differs (e.g., MFJ couple where each earns $160,000, combined $320,000 > $250,000 threshold), they reconcile via Form 8959 on their individual return.
How FICA Tax is Calculated, Worked Example
| Employee | Annual Wages | Social Security Tax (Employee) | Medicare Tax (Employee) | Additional Medicare | Total Employee FICA |
|---|---|---|---|---|---|
| Employee A | $60,000 | $60,000 x 6.2% = $3,720 | $60,000 x 1.45% = $870 | $0 (under $200k threshold) | $4,590 |
| Employee B | $200,000 | $176,100 x 6.2% = $10,918 (capped at SS wage base) | $200,000 x 1.45% = $2,900 | $0 (exactly at threshold) | $13,818 |
| Employee C | $300,000 | $176,100 x 6.2% = $10,918 (capped) | $300,000 x 1.45% = $4,350 | $100,000 x 0.9% = $900 (above $200k) | $16,168 |
Who is Exempt from FICA?
- Student employees working at the college or university they attend (under certain conditions)
- Non-resident aliens on certain visa types (F-1, J-1, M-1, Q-1 students and scholars)
- Some state and local government employees covered under alternative retirement plans
- Members of certain religious groups that have filed Form 4029 for an exemption
- Self-employed individuals pay a Self-Employment Tax (SE Tax) of 15.3% instead of FICA, this is the equivalent of both employee and employer FICA shares; they can deduct the employer-equivalent half on Schedule 1
FICA Tax and the Trust Fund Recovery Penalty
FICA taxes withheld from employee wages are held 'in trust' by the employer until deposited with the IRS. If the employer fails to deposit these funds, the IRS may assess the Trust Fund Recovery Penalty (TFRP): a personal liability equal to 100% of the unpaid trust fund taxes against any 'responsible person' (owner, officer, accountant, bookkeeper) who wilfully failed to ensure the deposits were made. This penalty bypasses the corporate liability shield and survives business closure or bankruptcy.
During initial onboarding audits, Profitjets identifies unremitted FICA tax exposure and miscalculated wage-cap withholdings in over 34% of small business clients.
For instance when we at Profitjets onboarded an e-commerce client who had fallen behind on six months of payroll deposits, resulting in a daunting $42,000 Trust Fund Recovery Penalty notice from the IRS targeting the founder personally.
We stepped in immediately, audited their historical Form 941 filings, established that a third-party payment processing lag caused the delay, and negotiated an installment agreement that halted personal enforcement actions while transitioning them to an automated payroll schedule.
Where It Shows Up on a Payslip
Employees frequently ask about these deductions, and the payslip rarely explains them clearly. Being able to answer removes a recurring conversation.
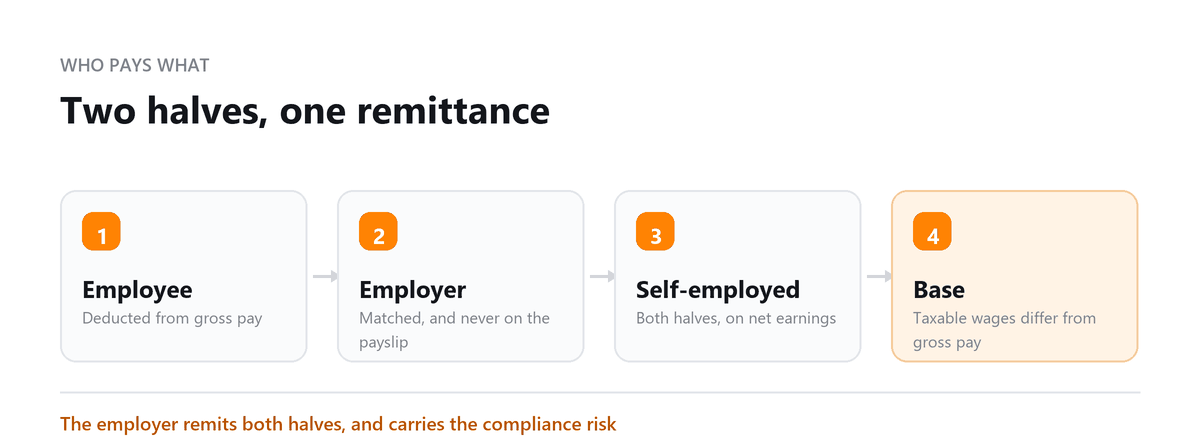
- The employee's share is deducted from gross pay and appears as a deduction
- The employer's matching share does not appear on the payslip at all, because it is not the employee's money
- The two together are remitted by the employer, which is why the employer carries the compliance risk
- Taxable wages for these purposes can differ from gross pay, because some pre-tax deductions reduce one and not the other
That last point is the source of most confusion. An employee comparing the boxes on their annual statement will often find they do not agree with each other, and that is usually correct rather than an error.
The Self-Employed Pay Both Halves
Someone working for themselves pays the equivalent of both the employee and the employer share, which is the single biggest financial shock for people leaving employment to work for themselves.
It is charged on net earnings rather than on gross receipts, so every legitimate business expense reduces it as well as reducing income tax. A portion of it is itself deductible in arriving at income, which softens the effect without removing it.
For a business owner taking income partly as salary and partly in another form, how the business is structured and classified affects how much of the profit is subject to this charge at all. That is a genuine planning question with its own obligations attached, and it is worth modelling properly rather than assuming a structure change is automatically better.
Common Errors in Small Business Payroll
The calculation is mechanical, and the errors come from setup rather than arithmetic.
Benefits and deductions configured with the wrong tax treatment, so amounts that should be excluded are included or the reverse. An employee who works in more than one entity within a group, where each employer applies limits to its own payments. Bonuses and commissions treated differently from regular pay when they should not be. And owners drawing money in a way that was never run through payroll at all.
The catch-all is a quarterly reconciliation of the payroll reports to the wages and payroll tax accounts in the ledger. An hour each quarter finds problems while they are still correctable, rather than at year end when correcting them means amended returns. Current rates and wage bases are published by the IRS each year.
Book a free consultation and we will tie them back to the ledger.
FAQs
What is the FICA tax rate for 2026?
The combined FICA tax rate is 15.3%, consisting of 12.4% Social Security and 2.9% Medicare. Employees generally pay 7.65%, while employers match the same amount. Social Security applies only up to the annual wage base, while Medicare applies to all covered wages. The 2026 Social Security wage base should be verified with the Social Security Administration.
Do self-employed people pay FICA taxes?
Self-employed individuals generally pay self-employment tax instead of FICA through payroll. The self-employment tax rate is 15.3%, representing both the employee and employer portions of Social Security and Medicare taxes. They can generally deduct the employer-equivalent portion when calculating adjusted gross income.
What is the difference between FICA and self-employment tax?
FICA taxes apply to employees and are split between the employee and employer. Self-employment tax generally applies to individuals who work for themselves, meaning they are responsible for both portions of Social Security and Medicare taxes.
Is Medicare tax subject to a wage limit?
No. The 2.9% Medicare tax generally applies to all covered wages without a Social Security-style wage base. Higher-income employees may also be subject to the 0.9% Additional Medicare Tax on wages above applicable IRS thresholds.
Who is responsible for paying FICA taxes?
Both employees and employers generally share responsibility for FICA taxes. Employers withhold the employee's share from wages and contribute an equal employer share, then deposit and report the applicable taxes to the IRS.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Payroll Taxes Not Reconciling?
Book a free consultation and we will tie them back to the ledger.