
The Federal Unemployment Tax Act (FUTA) is a federal payroll tax imposed on businesses to finance unemployment insurance programs. Contrary to the Federal Insurance Contributions Act (FICA), which covers both employers and employees, taxes under FUTA are paid solely by businesses, and they cannot be deducted from employees salaries.
This tax concerns the first $7000 earned by every employee, and the amount of FUTA tax due depends on the number of credits for which the employer is entitled. As such, it is essential to comprehend how the FUTA taxes are filed and what rules dictate their deposits.
FUTA is an employer-only tax, it is not withheld from employee wages. Understanding FUTA correctly matters because the effective rate (after SUTA credit) is low, but non-compliance and credit reduction states can increase the cost unexpectedly.
The single most common FUTA surprise for new employers is learning that paying state unemployment tax late invalidates their federal tax credit, turning a $42 per employee bill into a $420 bill, a mistake completely avoided by setting up automated quarterly SUTA payment schedules.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is FUTA Tax?
FUTA (Federal Unemployment Tax Act) imposes a payroll tax on employers to fund the federal portion of unemployment insurance benefits. Together with state unemployment insurance (SUTA), it provides the funding pool from which laid-off workers receive unemployment benefits. Key facts:
| FUTA Parameter | Detail |
|---|---|
| Rate | 6.0% on the first $7,000 of each employee's wages per year |
| Maximum tax per employee (before credit) | $7,000 x 6.0% = $420 |
| Who pays | Employer only, FUTA is NOT withheld from employee wages |
| SUTA credit | Employers who pay state unemployment insurance (SUTA) on time receive a credit of up to 5.4% against FUTA |
| Effective FUTA rate (with full SUTA credit) | 6.0% - 5.4% = 0.6% |
| Maximum FUTA per employee (with full credit) | $7,000 x 0.6% = $42/employee/year |
| Wage base | $7,000, has not changed since 1983; most employees earn well above this amount, meaning FUTA is capped at $42/year per employee regardless of total wages |
| Filing form | Form 940, filed annually by January 31 |
How the SUTA Credit Works
The 5.4% SUTA credit is the most important thing employers must understand about FUTA. If an employer pays their full state unemployment tax (SUTA) on time, they receive a 5.4% credit against FUTA, reducing the effective FUTA rate from 6.0% to 0.6%. This credit is available regardless of the employer's actual SUTA rate, an employer paying 2.7% SUTA still gets the full 5.4% FUTA credit.
FUTA Quarterly Deposits
Although Form 940 is filed annually, FUTA taxes must be deposited quarterly if the liability exceeds $500:
| Quarter | Months Covered | Deposit Due Date |
|---|---|---|
| Q1 | January, March | April 30 |
| Q2 | April, June | July 31 |
| Q3 | July, September | October 31 |
| Q4 | October, December | January 31 (with Form 940) |
If accumulated FUTA liability at any quarter-end is $500 or less, the employer can carry it forward to the next quarter without depositing. If it exceeds $500, a deposit is required by the due date above.
Profitjets files corrected Form 940 returns for nearly 1 in 5 new clients due to previously missed or miscalculated SUTA credits.
Which Employees Are Subject to FUTA?
| Category | FUTA Applicable? |
|---|---|
| Regular W-2 employees | Yes, on first $7,000 of wages per employee per year |
| 1099 independent contractors | No, FUTA applies only to employees (W-2), not contractors |
| Corporate officers (shareholders of corporations) | Yes, if they receive wages/salary |
| Household employees (nannies, caregivers in a private home) | Yes, if paid $1,000+ in a calendar quarter, reported on Schedule H, not Form 940 |
| Agricultural/farm workers | Separate FUTA rules apply, consult IRS Publication 51 |
| Certain family members employed in the business | Special rules may exempt spouse, child under 21, or parent, see IRS Publication 15 |
FUTA Exempt Wages
Not all compensation paid to employees is subject to FUTA. Common FUTA-exempt payments include:
- Fringe benefits: employer contributions to qualified pension plans, 401k, health insurance premiums, and HRA contributions
- Dependent care assistance (up to $5,000/year under a qualified plan)
- Business expense reimbursements under an accountable plan
- Tips not reported to the employer
- Workers' compensation payments
During client onboarding, Profitjets identifies that 22% of small businesses operating in FUTA credit reduction states fail to adjust their quarterly payroll accruals, leading to surprise year-end Form 940 tax bills averaging $1,250 per 10 employees.
Form 940: FUTA Annual Return
| Form 940 Element | Detail |
|---|---|
| Filing deadline | January 31 following the calendar year (February 10 if all FUTA deposits were made on time) |
| Who must file | All employers who paid $1,500+ in wages during any quarter, or had one or more employees for at least part of a day in 20 different calendar weeks |
| What it reports | Total FUTA wages, exempt wages, FUTA tax before credit, SUTA credit claimed, credit reductions (if applicable), net FUTA tax, deposits made |
| Payment with Form 940 | If any FUTA liability remains after quarterly deposits, pay the balance with the return |
| State unemployment agencies | Form 940 is separate from state unemployment filings, employers also file state Form UI (varies by state name and number) quarterly |
FUTA Credit Reduction States, What They Are and Why They Matter
When a state's unemployment trust fund runs out of money to pay benefits (as happened in many states during the 2008 recession and the 2020 COVID pandemic), the state borrows from the federal unemployment trust fund. If the state has not repaid that loan by November 10, it becomes a 'credit reduction state' employers in that state lose part of their 5.4% FUTA credit.
Example: A state with a 0.3% credit reduction means employers in that state pay an effective FUTA rate of 0.9% (0.6% base + 0.3% reduction) instead of the standard 0.6%. With a $7,000 wage base, this translates to $63/employee/year instead of $42.
Profitjets onboarded a mid-sized logistics client with a remote workforce in California who didn't realize the state's ongoing federal UI loan status had triggered a FUTA credit reduction. They were accruing FUTA at the standard 0.6% (126/worker) rate. We recalculated their multi-state liabilities, adjusted their payroll tax accruals prior to the annual Form 940 deadline, and prevented an unexpected Q4 cash drain."
Yes, since this is specifically for 2026, the FAQs should explicitly say 2026 and use the 2026 figures rather than leaving the rates generic.
One important correction: the $7,000 FUTA wage base and 6.0% gross rate remain the applicable federal figures for 2026. The maximum standard FUTA liability is therefore $420 per employee before the maximum 5.4% credit, or $42 with the full credit. Credit-reduction states can have a higher effective rate. (U.S. Department of Labor)
FAQs
Credit Reduction States
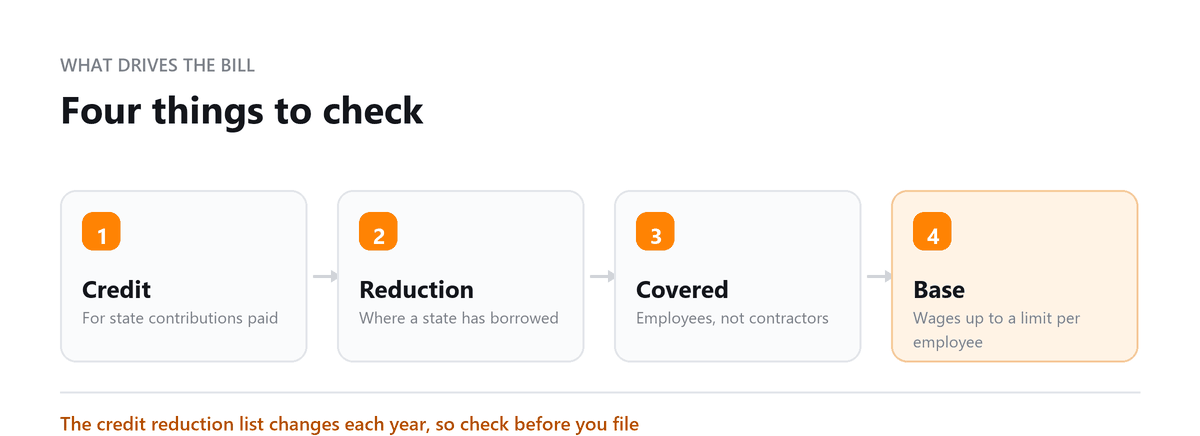
The effective federal rate most employers pay assumes a credit for state unemployment contributions. Where a state has borrowed from the federal government to fund its own unemployment programme and not repaid within the allowed period, that credit is reduced for employers in that state.
The effect is an additional amount due with the annual return, calculated on wages paid in the affected state. It is not optional and it is not something the employer did wrong. It is a consequence of the state's own borrowing position.
The list of affected states is published each year and changes, sometimes with states entering and leaving it. For an employer with staff in several states, checking the list before preparing the annual return avoids an unexpected balance, and budgeting for it in an affected state avoids a cash surprise.
Who Is Covered, and Who Is Not
The tax applies to wages paid to employees, and several categories sit outside it in ways that catch small employers.
- Genuine independent contractors are outside it, which makes classification a direct cost question as well as a compliance one
- Certain family employment arrangements are treated differently, particularly in unincorporated businesses
- Some categories of organisation have their own treatment, including certain exempt organisations
- Some types of payment to employees are excluded from the wage base even where the employee is covered
The classification question is the one with real money attached, and it is decided by how the work is actually controlled rather than by what the arrangement is called. The current exclusions are set out in the IRS instructions for the annual return.
Reconciling the Annual Return
The annual return reports wages and tax for the year and should agree with what was deposited during it. Where it does not, the difference has to be explained rather than simply paid.
The common causes are wages allocated to the wrong state, the wage base per employee applied incorrectly where someone worked in more than one state or for more than one entity in a group, and payments excluded from the base that should have been included.
Reconciling the annual return to the quarterly state filings and to the payroll records, before submitting, is what catches these. It also catches the credit reduction issue, since an employer who did not know about it will find the return producing a larger balance than expected.
Book a free consultation and we will check your FUTA position.
FAQs
What is the FUTA tax rate for 2026?
The 2026 FUTA tax rate is 6.0% on the first $7,000 of each employee's FUTA-taxable wages. Employers that qualify for the full 5.4% state unemployment tax (SUTA) credit generally have an effective FUTA rate of 0.6%, or up to $42 per employee per year. Employers in FUTA credit reduction states may owe more.
Does FUTA apply to independent contractors?
No. FUTA applies to employees, not properly classified independent contractors. Employers must still review worker classification carefully because misclassifying an employee as a 1099 contractor can create liability for FUTA, other employment taxes, and potential penalties.
Who pays FUTA tax?
Employers pay FUTA tax; it is not withheld from employee wages. For 2026, employers generally calculate FUTA on the first $7,000 of applicable wages paid to each employee during the year. The employer may then claim an eligible SUTA credit against the federal tax.
When are FUTA tax deposits due in 2026?
FUTA deposits are generally required quarterly when the accumulated FUTA liability exceeds $500. For 2026, the standard deposit deadlines are April 30, July 31, October 31, and January 31, 2027. If the liability is $500 or less, it can generally be carried forward to the next quarter.
When is Form 940 due for the 2026 tax year?
Form 940 for the 2026 tax year is generally due January 31, 2027. Employers that deposited all FUTA taxes when due generally receive an additional 10 days, making the filing deadline February 10, 2027. Any remaining FUTA tax liability should be paid by the applicable deadline.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Employing Across State Lines?
Book a free consultation and we will check your FUTA position.