
For most of the small business owners, managing their financial workflows often feels overwhelming. Two terms that they repeatedly encounter in the process are bookkeeping and accounting. They serve significant purposes when used correctly at different stages of the business. This article helps learn the differences, measurable outcomes and why understanding in detail is essential for your business growth.
When a small business owner approaches asking what they opt for, the answer is often both, but instead at various stages in the financial cycle based on their business objectives. We often guide our clients that the distinction is vital than most of the business owners realize. At Profitjets, we help businesses with accuracy in bookkeeping and precise accounting services.
Bookkeeping and accounting serve completely different purposes. A great bookkeeper gives you clean data, an accountant turns that data into strategy. You need both to grow a business properly, and confusing the two is one of the most expensive mistakes a founder can make.
Ankit Sarawagi, CPA, CA, MBA · LinkedInBookkeeping and Accounting: Definition
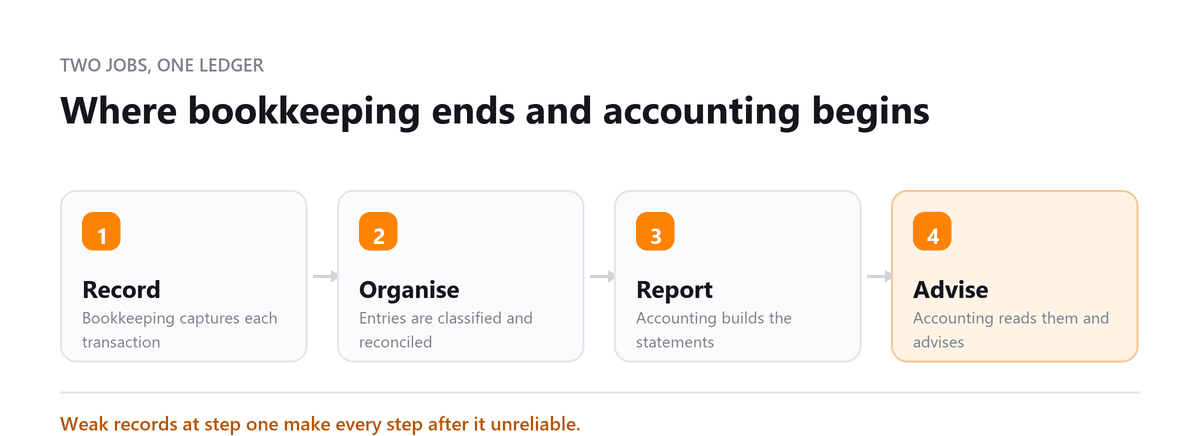
Bookkeeping and Accounting are two sides of the financial coin, but they play distinct roles. Bookkeeping is meticulously recording and organizing every financial transaction, like a daily data weave. It ensures accurate records and compliance.
Conversely, Accounting transforms that data into insightful narratives, revealing trends and informing critical decisions. It's the art of storytelling with numbers, guiding your business toward informed growth. Both work hand-in-hand, with bookkeeping laying the foundation and accounting building upon it, painting a clear picture of your financial health and empowering you to navigate the exciting, sometimes complex world of business finances.
Imagine your business finances as a car. Bookkeeping is the diligent mechanic, meticulously keeping the engine humming. Every transaction is a wrench turn, and every receipt is a diagnostic reading. They ensure your financial machine runs smoothly, day in and day out.
Accounting, on the other hand, is the visionary architect. They translate the mechanic's detailed blueprints into a magnificent structure: a clear vision of your financial future. They analyze trends, identify opportunities, and build robust economic models that guide your business toward sustainable growth.
At Profitjets, we have worked with more than 500 clients and the trajectory is stable, businesses that choose both the services at the right phase measurably scale faster than the ones that opt for one and wait till the problem influences the decision.
Bookkeeping and Accounting, Differences
Even though Bookkeeping and Accounting go hand-in-hand, there are significant differences in their roles:
| Feature | Bookkeeping | Accounting |
|---|---|---|
| Focus | Recording and organizing financial transactions | Analyzing and interpreting financial data |
| Data Handling | Detailed, day-to-day entries | Aggregated, summarized information |
| Skills | Data entry accuracy and basic accounting knowledge | Advanced financial analysis, interpretation, and reporting |
| Outputs | Ledgers, journals, invoices, and receipts | Financial statements, reports, and tax forms |
| Value Addition | Ensures compliance and accuracy | Provides insights for informed decision-making |
Bookkeeping is the foundation, ensuring your financial records are accurate and compliant. Accounting builds upon that foundation, providing the critical insights you need to:
- Track your financial performance: Monitor income, expenses, and profitability to understand your business's health.
- Make informed decisions: Analyze economic trends to guide investment, pricing, and operational strategies.
- Stay tax compliant: Prepare accurate tax returns and avoid costly penalties.
- Secure funding: Present compelling financial reports to attract investors or lenders.
Basic Principles of Bookkeeping and Accounting
Understanding the fundamental principles of bookkeeping and accounting is crucial for any business owner, regardless of size or industry. These principles act as a compass, guiding you through the financial maze and ensuring your financial records are accurate, reliable, and compliant:
Here are some fundamental principles to navigate by:
1. The Accounting Equation
This fundamental principle forms the basis of all accounting systems:
Assets = Liabilities + Owner's Equity
Every transaction affects at least two accounts in this equation. Understanding this relationship helps maintain balance and integrity in your financial records.
2. Double-Entry System
Each transaction is recorded twice, with a debit in one account and a credit in another. This ensures that every transaction is tracked and accounted for, preventing errors and omissions.
3. Accrual vs. Cash Basis Accounting
Accrual accounting records income and expenses as earned or incurred, regardless of when the money is collected or paid. Only transactions involving the exchange of funds are recorded in cash-based accounting. Your company's needs and legal requirements will determine which approach is best.
4. Objectivity and Verifiability
Financial records should be based on objective evidence, such as invoices, receipts, and contracts. Verifiable documents support the accuracy and reliability of your records.
5. Going Concern Assumption
This principle assumes your business will continue to operate in the foreseeable future. This affects how assets are valued and allows for long-term financial planning.
6. Materiality Principle
Focus on recording and reporting material transactions that significantly impact your financial statements. Minor transactions can be grouped for efficiency.
7. Consistency Principle
Use consistent accounting methods and procedures throughout your financial records to ensure accuracy and comparability over time.
8. Full Disclosure Principle
All relevant financial information should be disclosed in your financial statements, including both positive and negative aspects. Transparency builds trust with stakeholders.
9. Internal Control
Implement internal controls to safeguard your assets, ensure accurate recordkeeping, and prevent fraud. This includes procedures like segregation of duties and regular reconciliations.
10. Continuous Improvement
Stay updated on changes in accounting regulations and best practices. Regularly review your systems and processes to ensure they are efficient and effective.
Managing your books will be a smooth process with Profitjets. Let our bookkeeping services handle your books and provide you with insights to make informed decisions about your business.
Bookkeeping and Accounting Best Practices
Whether you're a seasoned entrepreneur or just starting your financial journey, implementing best practices in both bookkeeping and accounting is crucial for your business's health and growth. Here are some critical practices to embrace:
Bookkeeping Best Practices
- Accurately and consistently record every transaction: This is the bedrock of sound bookkeeping. Use a reliable accounting system and diligently record sales, expenses, payments, and receipts.
- Reconcile accounts regularly: Compare bank and credit card statements with your records to identify and fix any discrepancies.
- Automate as much as possible: Utilize online banking and accounting software to automate repetitive tasks like bill payments and data entry.
- Separate personal and business finances: To avoid confusion and potential legal issues, keep your personal and business finances distinct.
- Document everything: Maintain a clear record of all financial transactions, including receipts, invoices, and contracts.
Accounting Best Practices
- Generate regular financial reports: Create and analyze key financial reports, such as income statements, balance sheets, and cash flow statements, to track your financial performance.
- Monitor your accounts receivable and payable: Manage customer invoices and vendor bills regularly to maintain a healthy cash flow.
- Utilize budgeting and forecasting: Create and maintain realistic budgets to track your spending and forecast future financial needs.
- Stay updated on tax regulations: Familiarize yourself with relevant tax laws and deadlines to avoid penalties. Consider seeking professional guidance for complex tax matters.
- Perform internal audits: Regularly review your financial records to identify and address any errors or potential risks.
Bookkeeping and Accounting: Books to Read
Books for Learning Bookkeeping
- "The Complete Idiot's Guide to Bookkeeping" by Steven D. Book, Perfect for beginners with no prior bookkeeping knowledge
- "Accounting Principles, Part 1" by Debra J. Scott and Ronald F. Meigs, A widely-used college-level textbook providing a clear explanation of accounting fundamentals
Books for Learning Accounting
- "Financial Accounting & Reporting" by Jerry J. Weygandt, Paul D. Kimmel, and Donald E. Kieso, The gold standard college-level textbook for financial accounting
- "Accounting Made Easy" by Alan R. Gower, A straightforward and practical guide that demystifies accounting concepts for beginners
Remember, your business's financial success hinges on understanding and utilizing the distinct powers of bookkeeping and accounting. Embrace the power of data, let the numbers guide your decisions, and watch your business flourish.
Book a free consultation and we will cover the records and the reporting together.
Bookkeeping and Accounting FAQs
Can a bookkeeper do accounting work?
A bookkeeper can handle many day-to-day financial tasks, recording transactions, reconciling accounts, and generating basic reports. However, they are not qualified to prepare tax returns, provide financial advice, or sign off on audited financial statements. Those tasks require a licensed accountant or CPA.
Do I need both a bookkeeper and an accountant for my small business?
For most growing businesses, yes. A bookkeeper keeps your day-to-day records clean and current. An accountant uses those records for tax filing, financial planning, and strategic advice. The two roles complement each other, having both means nothing falls through the cracks.
Which comes first, bookkeeping or accounting?
Bookkeeping always comes first. Accounting depends entirely on the records a bookkeeper produces. Without accurate, up-to-date books, an accountant has nothing meaningful to work with. Think of bookkeeping as the raw data and accounting as the analysis.
Is bookkeeping a good career in 2026?
Yes, demand for skilled bookkeepers remains strong, especially as businesses outsource financial tasks rather than hire in-house. Cloud accounting has shifted the role from manual data entry toward advisory and analysis, making it more strategic and better paid than it was a decade ago.
What is the difference between a bookkeeper and an accountant's qualifications?
Bookkeepers typically hold a certification from NACPB or AIPB and are trained in recording and organising financial data. Accountants hold a degree in accounting and often a CPA licence, which qualifies them to prepare tax returns, perform audits, and provide certified financial advice.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Need Both Handled by One Team?
Book a free consultation and we will cover the records and the reporting together.