
Law firms are widely operating under distinct financial and compliance regulations when compared to other firms. Legal practices handle funds from clients settlement processes, retainers and trust funds. The funds often require clear financial records of the transaction details from the specific revenue firms. Segregating the funds and keeping it untouched from the operational expense is mandatory to ensure integrity for the law firms.
All the funds from the trust accounts hold the second party ownership which is the client. Law firms are not regulated ownership status. Any mishandling will lead to professional accountability of the firms. Multiple expense tracking is often complex for the firms with strict compliance requirements. Bookkeeping and accounting practices ensure information of the clear financial data of the law firm.
When compared to other businesses, law firms are required to maintain intensive regulatory measures that often require professional bookkeeping services. To understand and analyze the returns clear data on the financial transaction makes it seamless. This blog covers the bookkeeping and accounting information that law firms require to maintain their financial management efficiently.
Trust accounting is not optional for law firms, it is a professional obligation. The rules around client funds are strict, the audits are real, and the consequences of a violation can end a career. Law firms need bookkeeping that treats trust accounts as the highest priority, not an afterthought.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhat is Bookkeeping for Law Firms?
Law firm bookkeeping involves the systematic recording and management of all financial transactions for the firm. Key areas include:
- Client billing: recording time entries, expenses billed to clients, and issuing invoices, accurately and on time
- Expense management: tracking operating costs for the firm (rent, staff, software, professional development)
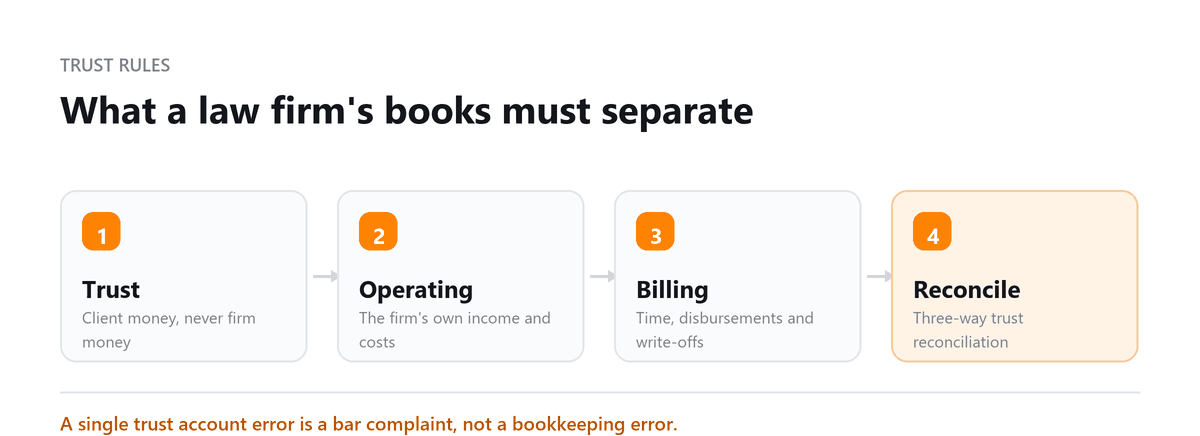
- Trust account management: maintaining accurate, separate records for every client's funds held in trust, subject to strict bar association rules
- Payroll: managing attorney and staff compensation, benefits, and associated tax obligations
What is Accounting for Law Firms?
While bookkeeping records the transactions, accounting analyses them. Law firm accounting covers:
- Financial reporting: producing P&L statements, balance sheets, and cash flow reports that reflect the firm's true financial position
- Tax preparation: ensuring the firm meets all federal, state, and local tax obligations, including estimated quarterly payments
- Financial analysis: evaluating practice area profitability, partner performance, and billing realisation rates
- Budgeting and forecasting: planning for future revenue, hiring, and capital needs based on historical financial data
Bookkeeping vs Accounting for Law Firms
The distinction matters for understanding what roles a law firm needs:
- Bookkeeping = data entry and record maintenance: recording every transaction, reconciling accounts, managing trust ledgers, producing reports
- Accounting = analysis and strategy: interpreting the financial data, preparing tax returns, providing financial advice, and ensuring overall compliance
Small firms may combine both functions in one person or outsourced provider. Larger firms typically separate the roles, a bookkeeper or practice manager handles day-to-day records, and a CPA handles tax and strategic financial analysis.
Why Financial Management Matters for Law Firms
- Financial Clarity: Know exactly what the firm earns, what it costs to run, and which practice areas or partners generate the most profit.
- Improved Cash Flow: Legal billing cycles can be slow. Disciplined bookkeeping supports faster invoicing, better collections, and more predictable cash flow.
- Reduced Compliance Risk: Trust account violations, tax errors, and payroll mistakes carry severe consequences in the legal profession, proper bookkeeping minimises these risks.
- Increased Profitability: Understanding realisation rates (the percentage of billed time that is actually collected) allows firm management to address inefficiencies.
- Stronger Client Trust: Transparent billing practices and accurate client trust account management build the confidence that clients need in their legal counsel.
Bookkeeping Tips for Law Firms
- Automate where possible: Use legal billing software that connects to accounting software to eliminate double data entry.
- Use cloud-based accounting software: Enables real-time access and is more secure than desktop-only solutions.
- Invest in time tracking: Every billable minute needs to be captured. Leakage in time tracking directly reduces firm revenue.
- Maintain strict separation of finances: Firm operating accounts and client trust accounts must never be commingled, this is a bar rule, not just best practice.
- Reconcile trust accounts every month: Most bar associations require monthly three-way trust reconciliations (bank statement, trust ledger, client sub-ledgers).
- Document everything: Maintain complete records of client billing, matter costs, trust transactions, and all financial decisions.
- Seek professional guidance from legal industry specialists: A CPA with law firm experience understands trust accounting rules, billing practices, and partnership taxation.
- Stay informed on legal industry regulations: Bar rules regarding trust accounting vary by state, stay current with your jurisdiction's requirements.
Best Accounting Software for Law Firms
| Software | Key Feature |
|---|---|
| Clio Manage | Integrated billing, time tracking, trust accounting, and financial reporting, purpose-built for law firms of all sizes |
| CosmoLex | Full accounting and practice management in a single platform, eliminates the need for a separate accounting system |
| Bill4Time | User-friendly billing and time tracking, popular with smaller practices and solo attorneys |
| Xero | Cloud-based, customisable reports, strong bank reconciliation, used by firms that want accounting flexibility alongside a billing tool |
Common Law Firm Bookkeeping Mistakes
- Inaccurate time tracking: Unbilled or under-billed time is direct revenue lost, implement time tracking tools and enforce daily time entry.
- Mixing personal and business finances: Especially problematic for small and solo firms, maintain strict account separation from day one.
- Neglecting trust accounting reconciliation: Failure to perform monthly three-way reconciliations is a bar violation in most jurisdictions, not just a bookkeeping lapse.
- Procrastinating on tax filings and estimated payments: Law firms, especially partnerships and S-corps, have complex filing obligations. Missing deadlines creates penalties.
- Lack of documentation: Every financial decision should be documented. Undocumented expenses cannot be defended in an audit.
- Ignoring internal controls: Law firms with no financial controls, no account access separation, no second approvals for large disbursements, are vulnerable to misappropriation.
At Profitjets, law firms are among the most compliance-sensitive clients we work with and for good reason. The consequences of getting trust accounting wrong extend far beyond financial reporting. We have worked with firms that came to us after discovering reconciliation issues, inconsistent trust account records, or bookkeeping processes that lacked the controls required by their state bar. In many cases, implementing proper trust accounting procedures immediately improved compliance confidence and reduced administrative risk.
We also regularly see firms that have strong legal practices but limited visibility into the financial performance of individual matters, attorneys, or practice areas. Once bookkeeping and reporting systems are properly structured, partners gain clearer insights into profitability, billing efficiency, realization rates, and cash flow. These insights support better business decisions while helping firms maintain the high compliance standards expected within the legal profession.
Book a free consultation and we will set up compliant three-way reconciliation.
Frequently Asked Questions
What is IOLTA trust accounting for law firms?
IOLTA (Interest on Lawyers' Trust Accounts) is a programme where client funds held in trust are placed in interest-bearing accounts, with the interest going to legal aid organisations. All client funds must be kept separate from firm operating funds, and IOLTA accounts are subject to strict bar association oversight and monthly reconciliation requirements.
Do law firms need a separate bookkeeper and accountant?
It depends on size. Solo practitioners and small firms often use one outsourced provider that handles both functions. Mid-size and large firms typically employ a practice manager or bookkeeper for day-to-day records and engage a CPA for tax filings, financial analysis, and strategic advice.
How are law firm partners taxed?
Partnership income (including most law firms structured as LLPs or general partnerships) flows through to partners who report their share on personal tax returns. Partners pay self-employment tax on their distributive share of income. The firm itself does not pay income tax, each partner is responsible for their own estimated quarterly payments.
What is a billing realisation rate and why does it matter?
The realisation rate is the percentage of billed time that is actually collected. A firm with a 75% realisation rate is losing 25 cents of every dollar billed, to write-offs, discounts, and uncollected invoices. Tracking and improving realisation is one of the highest-ROI financial management actions for any law firm.
What are the consequences of trust accounting violations?
Consequences range from formal reprimand and financial penalties to suspension and disbarment, depending on the jurisdiction and severity of the violation. Even unintentional mishandling of client funds can result in serious professional consequences, which is why trust accounting must be treated as the highest-priority bookkeeping function.
Conclusion
Law firm financial management demands more than standard bookkeeping skills, it requires expertise in trust accounting rules, legal billing practices, and the specific tax treatment of legal partnerships. The firms that invest in proper systems and qualified professionals are better positioned to grow, stay compliant, and serve their clients with integrity.
Profitjets provides bookkeeping and accounting services for law firms, including trust account management, billing reconciliation, and monthly financial reporting. Get in touch to find out how we support legal practices.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Want Trust Accounting Done Right?
Book a free consultation and we will set up compliant three-way reconciliation.