
Law firms hold money belonging to clients, and the rules governing that are stricter than anything in ordinary commercial bookkeeping.
The obligation is not only accuracy but demonstrability: being able to show, at any point, that what is held matches what is owed to each client individually. That is a different standard and it shapes the whole system.
This covers client trust accounts, the rule against mixing funds, the three-way reconciliation, how firm revenue is recognised, reporting on settlements, case disbursements, and the software built for it.
Law firm bookkeeping has requirements that don't exist anywhere else in small business accounting. Trust account management and IOLTA compliance are not optional, violations can mean disbarment. Here's what every attorney needs to know about managing their firm's finances.
IOLTA Accounts: The Foundation of Attorney Trust Accounting
IOLTA stands for Interest on Lawyers' Trust Accounts. It's a type of pooled trust account where client funds are held separately from the lawyer's own money. Interest earned goes to state legal aid programs.
- Mandatory in all 50 states for client funds held in small amounts or for short periods
- Client funds held for longer periods or in larger amounts may earn interest directly for the client
- IOLTA accounts must be at approved financial institutions (usually banks)
- Never commingle client funds with the firm's operating funds, ever
Client money and firm money never touch, and the person who moves it should not be the person who proves it is correct. In a small firm that means somebody else reviews and signs the reconciliation, and the review is evidenced.
Ankit Sagatani, MBA, B.Com · LinkedInThe No-Commingling Rule
Commingling means mixing client funds with attorney funds. It is an ethics violation in every state, regardless of intent.
- Client retainers go into the trust account, not the operating account
- Earned fees are moved to the operating account only after they are earned
- Overpayments by clients must be refunded from trust, not operating funds
- Your own money (for bank fees) cannot stay in trust longer than necessary
Pro Tip: Some states require you to deposit a small amount of firm funds into the IOLTA account to cover bank fees. Keep it minimal and document it clearly.
Three-Way Trust Reconciliation
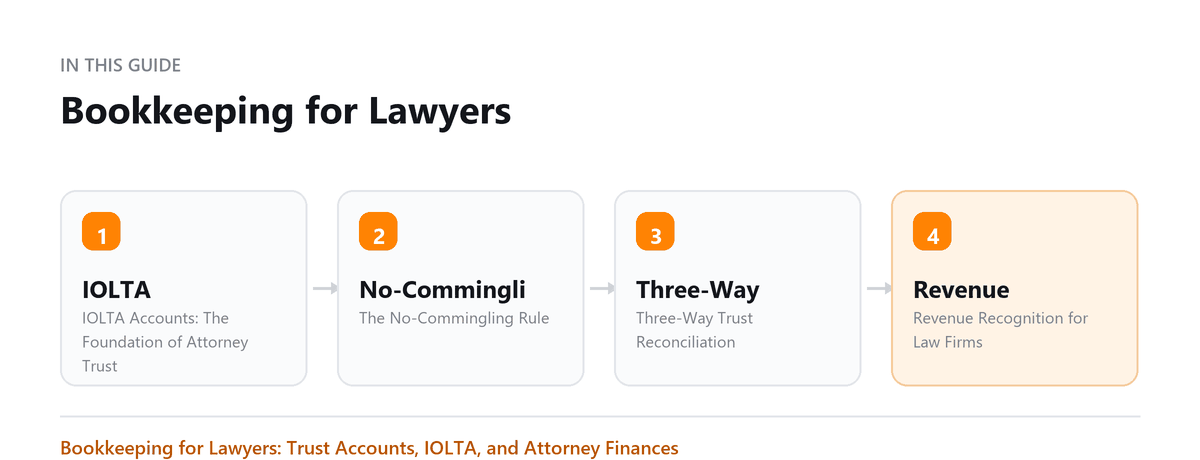
Every month, you must reconcile three records and prove they all agree:
- Bank statement balance (what the bank shows)
- Trust account ledger balance (total of all client sub-ledger balances)
- Individual client ledger balances (each client's running total)
If any of these three disagree, you have an error that must be found and corrected before month-end. Most state bars require these reconciliations to be documented and retained.
Revenue Recognition for Law Firms
Hourly Billing
Revenue is recognized when hours are worked and billed. Retainers are a liability until earned. Move retainer funds from trust to operating account only when the work is done.
Contingency Fees
Revenue is recognized when the case settles or judgment is entered. Settlement funds must flow through trust, you take your percentage; the client receives the rest.
Fixed Fees
Recognize over the period of service. If you bill a flat $5,000 for a transactional matter, recognize it proportionally as work is completed, not all on receipt.
1099 Reporting for Legal Settlements
Legal settlement proceeds paid through an attorney are subject to complex 1099 reporting rules.
- Gross proceeds paid to an attorney: report on Form 1099-MISC, Box 10 (over $600)
- Report to both the attorney and the IRS
- Damages for physical injury are generally not taxable to the plaintiff, but still may need reporting
- Punitive damages and back pay are taxable, always
- Work with your CPA to understand the reporting obligation for each settlement type
Case Cost Disbursements
When you advance costs on behalf of a client (filing fees, expert witnesses, deposition transcripts), these are either expenses or client receivables, depending on whether you expect reimbursement.
- If client will reimburse: record as 'client costs receivable' (an asset), not as your expense
- If you absorb the cost: record as a firm expense
- Document every disbursement with a receipt and client matter number
- Track by client in your matter management software or a detailed spreadsheet
Software for Law Firm Bookkeeping
| Software | Best For |
|---|---|
| QuickBooks Online + Clio | Most common setup: QBO for accounting, Clio for matter management + time tracking |
| LEAP | Integrated practice management + accounting for small firms |
| Cosmolex | Built-in trust accounting compliance tools |
| MyCase | Good for smaller firms; integrates with QBO |
| Tabs3 | Legacy law firm billing software with strong trust accounting |
Common Law Firm Bookkeeping Mistakes
- Using the same bank account for trust and operating funds
- Not doing three-way reconciliation monthly
- Recording retainers as revenue before they're earned
- Missing 1099 filings for vendors and contractors
- Not tracking case cost disbursements as client receivables
- Using online bank transfers to move trust funds without documentation
Book a free consultation and we will bring them current.
Frequently Asked Questions
What happens if I commingle client funds?
Commingling is an ethical violation that can result in suspension or disbarment, depending on intent and harm. Even accidental commingling must be corrected immediately and may require disclosure to your state bar.
Do I need a separate trust account for every client?
No. IOLTA accounts are pooled, one account, multiple client sub-ledgers. Each client has their own running balance tracked in your ledger, but the bank account is shared. Separate accounts are only required for large, long-term client deposits earning meaningful interest.
Can I use QuickBooks for law firm trust accounting?
Yes, but carefully. QBO doesn't enforce trust accounting rules, you have to set it up correctly. Many firms use Clio or Cosmolex for trust accounting and sync to QBO for tax and financial reporting. A bookkeeper experienced in law firm accounting is essential.
How long do I need to keep trust account records?
Typically 7 years, but state bar rules vary. Some states require longer retention. Keep bank statements, reconciliations, client ledgers, and all supporting documents.
Who in the firm should be doing the trust reconciliation?
Not the person who makes the payments, which is the one structural control that matters most here. Whoever moves money out of the account should not be the person who proves the account is correct, because that combination is what allows an error or a misappropriation to persist unnoticed. In a small firm where the same person does both, the reconciliation should at least be reviewed and signed off by a partner who did not prepare it.
Free consultation
Books Behind?
Book a free consultation and we will bring them current.