Operating a homeowners association comes with its own challenges in managing community obligations. Homeowners association boards(HOA) board regulates the residential community of mid-sized town homes that should maintain accurate financial records. As HOA is a member serving organization, it has become mandatory to maintain clean records. Under HOA, every houseowner needs a clear financial picture on how their interests are handled, funds are operated and regulations are maintained.
As HOA needs to safeguard the board of directors and maintain a long-term relationship with homeowners, financial transparency has become more essential to operate. Bookkeeping services handle the record of financial transactions with clear, accurate and reconciled books and help strategize how HOAs can implement plans to save up deductions. Keeping the beneficiaries audit-ready will ensure trust and confidence in maintaining the financial health.
Contrary to conventional businesses, HOAs handle vendor payrolls, operational expenses, secure ongoing funding and satisfy houseowners expectations. Governance is required by the board members to evaluate and assess the clear financial data. Good bookkeeping services will help neglect the disputes and shortfalls affecting members trust in the organization.
This guide briefs the bookkeeping services for small and mid sized HOA Homeowners Association to enhance financial clarity
An HOA's books belong to the community, which means every homeowner has a stake in how accurate they are. The HOAs that maintain clean, transparent records consistently have lower disputes, better community trust, and fewer problems when it is time for an audit or a reserve study.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhat is an HOA?
A homeowners association (HOA) is a non-profit organisation that manages a shared living space, typically a residential community, condominium complex, or planned neighbourhood. HOAs are responsible for:
- Maintaining common areas such as parks, pools, and landscaping
- Enforcing community rules and regulations set out in the governing documents
- Collecting dues from homeowners to fund community maintenance and operations
- Managing security, repairs, and vendor contracts on behalf of residents
Because HOAs handle money collected from all homeowners, financial accountability is central to every aspect of HOA governance.
Why Bookkeeping is Required for HOAs
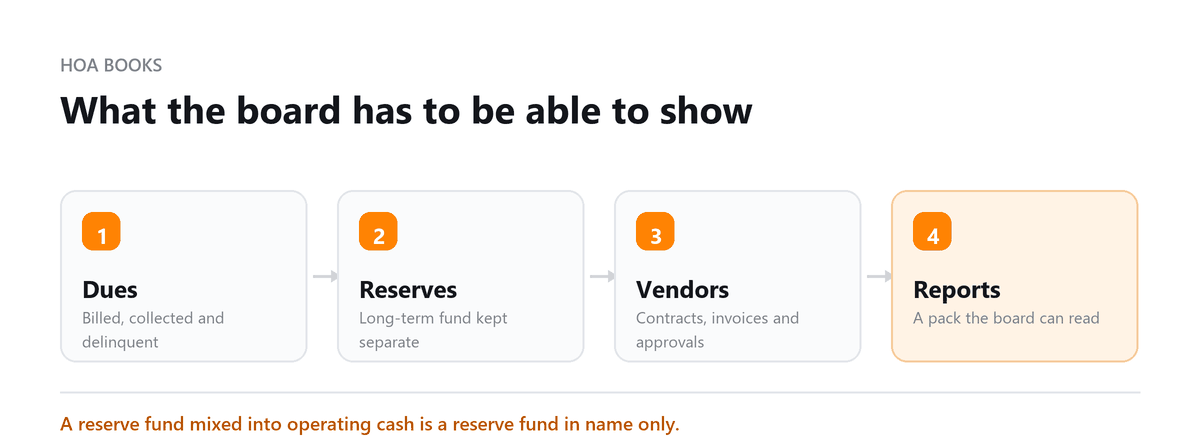
HOAs are legally required to maintain accurate financial records in most US states. Beyond legal compliance, good bookkeeping serves four critical purposes:
- Transparency: Homeowners have the right to inspect HOA financial records. Accurate books make that process straightforward and build community confidence.
- Decision-Making: Boards need reliable data to plan maintenance schedules, set annual budgets, and make capital improvement decisions.
- Compliance: Many states require HOAs to file annual financial reports, maintain reserve studies, and follow specific accounting standards.
- Streamlined Operations: Well-maintained records reduce the time and cost of annual audits, legal disputes, and management transitions.
According to the Community Associations Institute (CAI), underfunded reserves remain one of the most common financial challenges facing homeowners associations. Associations that maintain accurate financial records and conduct regular reserve studies are generally better positioned to avoid special assessments and unexpected funding shortfalls.
Advantages of Good Bookkeeping for Small HOAs
Small HOAs often operate with volunteer board members and limited administrative resources. Good bookkeeping delivers outsized benefits in this environment:
- Reduced Workload: Organised records mean less time spent hunting for documents and reconciling discrepancies at year-end.
- Improved Cash Flow: Clear visibility into dues collection and upcoming expenses prevents the association from being caught short.
- Better Budgeting: Historical financial data makes annual budget planning faster and more accurate.
- Simplified Tax Preparation: HOAs must file federal tax returns. Clean books make this far less burdensome.
- Increased Property Values: Communities with well-managed finances and properly funded reserves are more attractive to buyers, which supports property values throughout the association.
At Profitjets, we have helped HOA boards untangle years of disorganized financial records, reconcile incomplete dues histories, and establish reporting systems that provide clear visibility into community finances. Many associations rely on volunteer board members who care deeply about their communities but may not have professional accounting experience. Implementing structured bookkeeping processes helps ensure every transaction is documented, every assessment is accounted for, and every homeowner can understand where association funds are being used.
We have also seen firsthand how financial transparency reduces conflict within communities. When homeowners have access to accurate reports and reserve fund information, questions are answered more quickly and concerns are addressed with facts rather than assumptions. Strong bookkeeping practices help boards make better decisions, prepare for major capital projects, and demonstrate responsible stewardship of community resources.
Practical Tips for HOA Bookkeeping
- Establish clear financial policies: Document how dues are collected, how expenses are approved, and how funds are held, and make these policies available to all homeowners.
- Maintain consistent record-keeping: Record every transaction in a dedicated accounting system, not a spreadsheet or paper ledger.
- Reconcile bank accounts monthly: Match your accounting records against bank statements every month without exception.
- Conduct regular board financial reviews: The full board should review financial reports at every meeting, not just the treasurer.
- Consult a certified accountant: Engage a CPA with HOA experience for annual reviews, tax filings, and reserve study guidance.
- Use online resources and HOA-specific software: Dedicated platforms reduce manual effort and improve accuracy.
- Stay informed on HOA regulations: Financial reporting requirements vary by state. Make sure your practices remain compliant.
Best HOA Bookkeeping Software
| Software | Best For | Key Features |
|---|---|---|
| Yardi Voyager | Mid-to-large HOAs | Comprehensive property management platform with robust accounting, budgeting, and reporting modules |
| AppFolio | Growing HOAs | Cloud-based solution combining accounting, resident management, and community communication tools |
| HOA Start | Small HOAs | User-friendly interface focused on dues management and online payment processing for smaller communities |
| MRI Living | Small-to-medium HOAs | Cloud platform with integrated accounting, resident management, and maintenance tracking |
Book a free consultation and we will set the association's books up properly.
Frequently Asked Questions
Does a small HOA need a professional bookkeeper?
Not necessarily, but it is strongly advisable. A volunteer treasurer can manage basic dues collection and expense recording, but a professional bookkeeper or CPA ensures the books are accurate, compliant, and defensible if a homeowner disputes the financials.
How often should HOA finances be reviewed?
At a minimum, the full board should review a financial report at every monthly meeting. A more detailed review, including bank reconciliation and budget variance analysis, should happen quarterly, with a full annual audit or review by an independent CPA.
What financial records must an HOA keep?
HOAs should retain bank statements, dues payment records, invoices, contracts, meeting minutes with financial decisions, annual budgets, and tax filings. Most state laws require records to be kept for at least three to seven years.
Can an HOA use QuickBooks?
Yes. QuickBooks Online is a workable option for small HOAs that cannot afford dedicated HOA software. However, purpose-built platforms like HOA Start or AppFolio offer features such as homeowner portals and dues tracking that QuickBooks does not provide out of the box.
What happens if an HOA has poor bookkeeping?
Poor bookkeeping can lead to budget shortfalls, underfunded reserves, homeowner disputes, state compliance violations, and, in the worst cases, board member personal liability. It also makes the HOA difficult to audit and expensive to manage.
Conclusion
For small HOAs, good bookkeeping is not a luxury, it is the foundation of community trust, legal compliance, and long-term financial health. With the right software, consistent practices, and professional guidance where needed, even a volunteer-run HOA can maintain financial records that satisfy every homeowner and pass any audit.
Profitjets works with HOA boards to build the bookkeeping systems and processes that make financial management straightforward, so boards can focus on serving their communities rather than searching for receipts.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
On an HOA Board?
Book a free consultation and we will set the association's books up properly.