
Nonprofits don't track money the way businesses do. There's no profit to measure and no owners to report to. Instead, a nonprofit answers to donors, grantors, board members, and regulators, all of whom want to know the same thing: was the money used the way it was meant to be? A $50,000 grant set aside for a youth program can't quietly cover rent, and an audit or grant report will show whether it did.
Nonprofit accounting is built around that accountability. Instead of equity, nonprofits report net assets, split between funds that donors have restricted and funds the organization can use freely. Expenses are shown by function, so readers can see how much goes to programs compared with administration and fundraising. Contributions, pledges, and grants each follow their own recognition rules, and most organizations must file an annual Form 990 that's available to the public.
Getting it right protects more than compliance. Clean nonprofit books make grant applications stronger, audits smoother, and board decisions better informed. Changes taking effect in 2026, including a new charitable deduction for donors who don't itemize, may also shift giving patterns, which makes accurate tracking of contributions and restrictions even more important.
Expert Quote
This guide covers what nonprofit accounting is, how it differs from for-profit accounting, fund accounting and net asset classifications, and practical tips for keeping nonprofit books accurate.
Non-profit accounting has one job that for-profit accounting doesn't: proving that every restricted dollar went where the donor said it should go. That's fund accounting in one sentence. The consequences of getting it wrong aren't just financial, you can lose a major grant, trigger an audit, or lose your 501(c)(3) status entirely.
Anu Gupta, CA, EA, B.Tech · LinkedInWhat is Non-Profit Accounting?
Non-profit accounting is a specialized accounting system built around accountability rather than profitability. Where for-profit accounting tracks how effectively a business generates returns for its owners, non-profit accounting tracks how responsibly an organization receives and deploys funds entrusted to it by donors, grant-makers, and the public. The core mechanism is fund accounting: maintaining separate ledgers for each category of funds based on the restrictions placed on their use.
GAAP compliance is required under ASC 958; transparent financial controls are essential both for IRS compliance and for maintaining the donor trust that sustains fundraising.
Why Are Accounting and Bookkeeping Important for Non-Profits?
Financial clarity directly enables mission execution. A non-profit that does not know which program grants are fully spent, which are underspent, and which are at risk of clawback cannot allocate staff time effectively. Donor trust, which is the foundation of fundraising, depends on transparent, accurate reporting: donors who see clear accounting of how their gifts were used give again; those who do not, do not. Data-informed program decisions require accurate cost allocation across programs, and maintaining 501(c)(3) status requires the fiscal responsibility that sound accounting systems enforce.
How Does Non-Profit Bookkeeping Differ from Small Business?
| Factor | For-Profit Business | Non-Profit Organization |
|---|---|---|
| Primary goal | Maximize profit for owners | Maximize mission impact |
| Revenue tracking | By product/service | By fund (restricted vs. unrestricted) |
| Financial statements | Income statement, balance sheet | Statement of financial position, statement of activities |
| Tax status | Taxable entity | 501(c)(3) exempt (but must file Form 990) |
| Accounting basis | Accrual (GAAP) | Accrual (GAAP, non-profit version) |
| Donor compliance | N/A | Restricted fund tracking required |
How to Do Non-Profit Accounting
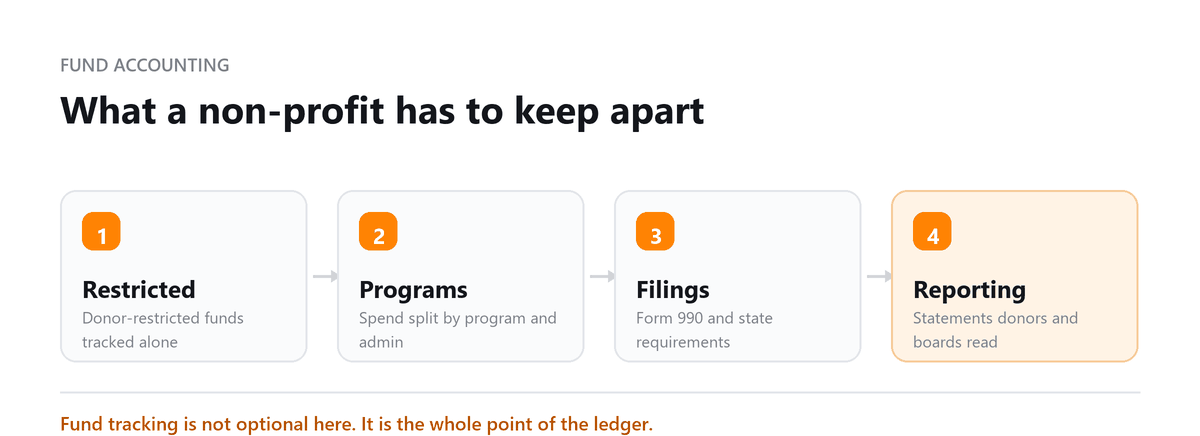
- Adopt fund accounting: maintain separate accounts and ledgers for each restricted grant or donation purpose, distinguishing clearly between unrestricted operating funds, temporarily restricted funds (purpose or time restrictions), and permanently restricted funds (endowments).
- Follow GAAP (non-profit edition): ASC 958 governs non-profit financial reporting, including how revenue is recognized, how net assets are classified, and what must be disclosed in financial statements.
- Implement internal controls: segregate financial duties so no single person controls a complete transaction cycle, require dual approval for disbursements above defined thresholds, and conduct regular reconciliation reviews.
- Use specialized accounting software: general small-business accounting software often cannot handle fund accounting correctly. Purpose-built platforms (Aplos, Blackbaud Financial Edge, MIP Fund Accounting) or properly configured QuickBooks with class tracking are recommended.
- Consult certified non-profit accounting professionals who understand ASC 958, Form 990 requirements, UBIT rules, and state charitable reporting obligations.
What Does a Non-Profit Bookkeeper Do?
A non-profit bookkeeper manages the financial records with mission accountability as the primary objective. Day-to-day responsibilities include tracking all revenue by fund and restriction type, recording expenses by program and general administrative category, managing grant drawdown schedules, ensuring that restricted funds are spent only on permitted activities, and maintaining the documentation trail that satisfies grant audits. The role also encompasses maintaining accounting software, enforcing internal controls, and providing the financial data needed for program cost allocation and impact measurement.
Non-Profit Bookkeeping Examples
Fund accounting in practice: A restricted grant of $50,000 is received for a specific literacy program. The credit is recorded in restricted net assets (not unrestricted operating revenue); the cash debit goes to the general bank account. As program expenses are incurred, staff time allocated to the program, materials purchased, they are debited to the program expense account and credited to cash. When all grant conditions are satisfied, the amount is released from restriction: debit net assets released from restriction, credit restricted revenue.
The grant funder can trace every dollar from receipt to expenditure through this chain of entries. (Update all example dates to December 31, 2025 or December 31, 2026 per the YELLOW flag above.)
Non-Profit Taxes and Forms
- Section 501(c)(3) exemption: qualifying non-profits are exempt from federal income tax on income related to their exempt purpose, but must apply for and maintain this status through compliance with IRS requirements.
- Form 990 Series: the annual information return required of most tax-exempt organizations. Form 990 for larger organizations (publicly available and reviewed by donors and watchdog groups); Form 990-EZ for organizations under $200,000 in gross receipts; Form 990-N (e-postcard) for very small organizations under $50,000.
- UBIT (Unrelated Business Income Tax): income from activities not substantially related to the organization's exempt purpose is taxable, even for a 501(c)(3). Organizations with regular unrelated business income file Form 990-T.
- Employment taxes: non-profits with employees must withhold federal income tax, Social Security, and Medicare from employee wages and file quarterly Form 941 returns, the tax-exempt status does not extend to payroll tax obligations.
- State reporting: most states require annual filings with the state attorney general's office or a charitable registration authority, with financial statements attached. Requirements vary significantly by state and revenue level.
How Profitjets Helps Non-Profits
Profitjets currently lists Nonprofit Organizations among the industries it serves and specifically offers nonprofit bookkeeping support for fund tracking, grant management, and donor financial reporting. The company does not publicly state a verified number of nonprofits served or a Form 990 accuracy rate, so those figures should be confirmed internally before publication.
Conclusion
Non-profit accounting is a specialized discipline where the stakes extend beyond financial accuracy to mission credibility, donor trust, and legal compliance. Fund accounting, ASC 958, Form 990, and UBIT rules require professional expertise that most general accounting practitioners do not maintain. Non-profits that invest in proper accounting infrastructure, the right software, the right professional support, and robust internal controls, protect their 501(c)(3) status, build donor confidence, and free leadership to focus on mission rather than financial reconstruction.
Book a free consultation and we will set fund accounting up properly.
FAQs
What is fund accounting and why do non-profits use it?
Fund accounting is a system that tracks financial resources by the restrictions placed on them, separating unrestricted funds (general operating money) from temporarily restricted funds (grants for specific purposes) and permanently restricted funds (endowments). Non-profits use it to demonstrate accountability to donors and grant-makers that restricted money was used as intended.
Is a non-profit required to have an audit?
Many non-profits must have an independent audit if they receive federal grants (Single Audit under Uniform Guidance), exceed state charity registration thresholds (varies by state), or have lender requirements. Some states require audits for organizations above certain revenue levels, check your state attorney general's office for requirements.
What is Form 990 and who files it?
Form 990 is the IRS annual information return for tax-exempt organizations. Most 501(c)(3) organizations file it, with the version depending on revenue: Form 990-N (e-postcard) for organizations with gross receipts under $50,000; Form 990-EZ for organizations under $200,000; Form 990 for larger organizations. It is publicly available, donors and watchdog groups review it.
Can a non-profit make a profit?
Yes, the word 'non-profit' refers to the organization's purpose, not its financial results. Non-profits can have revenue that exceeds expenses. The restriction is that any surplus must be reinvested in the mission rather than distributed to owners or shareholders. Consistent surpluses help build reserves and financial resilience.
What accounting software is best for non-profits?
QuickBooks Online (Non-Profit edition) is widely used for smaller organizations. Aplos, Blackbaud Financial Edge, and MIP Fund Accounting are purpose-built for non-profit fund accounting. The key features to look for: fund/class tracking, grant management, donor reporting, and Form 990 preparation support.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Want Books Your Board Can Read?
Book a free consultation and we will set fund accounting up properly.