
Managing a rental property is mainly focused on creating and compounding wealth. It produces a recurring income source to manage all the financial needs. Still managing ownership on the properties needs clear financial records to streamline growth.
Owning rental property can be an effective way to build long-term wealth, generate recurring income, and diversify an investment portfolio. However, successful property ownership requires more than collecting rent each month. Every rental payment, maintenance expense, mortgage interest charge, insurance premium, property tax bill, and capital improvement contributes to the property's true financial performance. Without accurate bookkeeping and accounting, it becomes difficult to understand profitability, maximize tax benefits, or make informed investment decisions.
Many landlords focus primarily on occupancy rates and rental income, but these metrics only tell part of the story. The real financial picture emerges when revenue is measured alongside operating expenses, maintenance costs, financing obligations, depreciation, and vacancy periods. A property that appears profitable on the surface may produce significantly different results once all costs are properly accounted for. Accurate bookkeeping provides the visibility needed to evaluate performance, plan future investments, and avoid costly surprises.
One area where accurate accounting becomes especially valuable is tax planning. Rental property ownership offers significant deductions and depreciation benefits, but those benefits are only available when supported by detailed records and proper documentation. Landlords who maintain organized books are typically better positioned to claim legitimate deductions, prepare for tax season efficiently, and make strategic decisions about future acquisitions or property improvements.
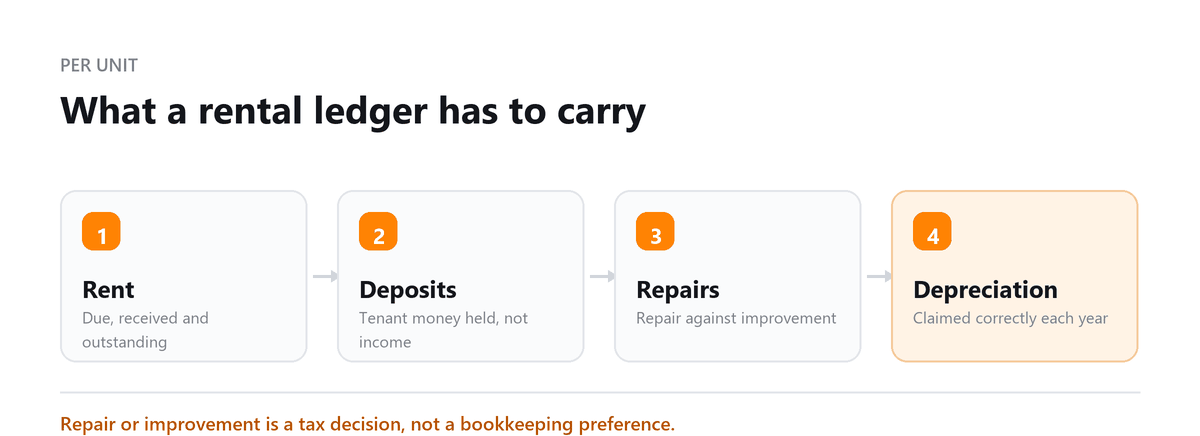
Rental property accounting gets complicated fast, especially once you have multiple properties. Depreciation schedules, repair vs capital improvement classification, security deposit handling, these are not intuitive decisions, and getting them wrong has real tax consequences.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhat is Bookkeeping for Rental Properties?
Rental property bookkeeping means maintaining accurate, up-to-date financial records for every property you own. This includes:
- Recording all income: monthly rent payments, security deposits received, late payment fees, pet fees, and any other charges collected from tenants
- Tracking all expenses: mortgage interest, property taxes, insurance premiums, repairs and maintenance, property management fees, HOA dues, utilities, and professional services
- Managing depreciation: calculating and recording annual depreciation for each property and any significant capital improvements
- Bank reconciliation: matching your accounting records against bank statements to catch errors and unauthorised transactions
- Tenant records: maintaining records of each tenancy, lease terms, payment history, security deposit balances, and correspondence
What is Accounting for Rental Properties?
Accounting takes the bookkeeping records further to provide strategic financial insight:
- Financial statements: producing income statements and balance sheets that show the true profitability and net worth of the portfolio
- Tax preparation: filing Schedule E for rental income and expenses, claiming depreciation, and managing capital gains reporting on property sales
- Profitability analysis: comparing actual returns against projections and benchmarks to identify which properties are performing well
- Cash flow forecasting: planning for future expenses, rent increases, vacancies, and capital improvements based on historical data
Why Financial Management Matters for Rental Property Owners
- Financial Clarity: Know exactly how much each property earns, what it costs to operate, and what your true net return is after all expenses and taxes.
- Improved Cash Flow: Accurate tracking of rent collection, upcoming expenses, and maintenance reserves helps you avoid cash shortfalls.
- Reduced Tax Liability: Rental properties offer significant tax advantages, depreciation, mortgage interest, operating expenses, but only if properly documented.
- Simplified Tax Filing: Organised records make Schedule E preparation straightforward and reduce the risk of errors that trigger audits.
- Increased Property Value: Well-documented financials support refinancing, sale transactions, and 1031 exchanges by providing the clean historical records buyers and lenders require.
According to the IRS, residential rental property owners can generally depreciate residential rental buildings over 27.5 years, making depreciation one of the most valuable tax benefits available to landlords. Profitjets recommends maintaining detailed fixed asset records to ensure these deductions are properly captured and supported. Replace with a verified Profitjets client statistic if available.
Bookkeeping Tips for Rental Property Owners
- Automate where possible: Connect property management software to accounting software to eliminate manual rent payment recording.
- Maintain strict financial separation: Open a dedicated bank account for each property or at minimum for the rental portfolio.
- Document every transaction: Keep leases, invoices, receipts, and contractor agreements organised by property and by year.
- Reconcile every account monthly: Do not wait until tax time to find discrepancies.
- Categorise expenses correctly: The distinction between repairs (fully deductible in the year incurred) and capital improvements (depreciated over multiple years) has significant tax implications.
- Stay current on tax regulations: Rental income tax rules, short-term rental treatment, and depreciation rules can change, engage a CPA to stay compliant.
- Seek professional help for complex matters: Cost segregation studies, 1031 exchanges, and multi-state rental operations all benefit from specialist expertise.
Best Accounting Software for Rental Property Owners
| Software | Best For |
|---|---|
| AppFolio | Individual landlords, user-friendly interface, rent collection, maintenance request management |
| Buildium | Growing portfolios, comprehensive cloud-based property and financial management |
| Xero | Versatile use, robust accounting features with strong reporting and bank reconciliation |
| QuickBooks Online | Customisable accounting, widely used, many CPAs familiar with the platform |
| TenantCloud | Integrated property management and accounting, good for landlords who want one system |
| Zoho Books | Affordable option for multi-property management with strong automation features |
Common Rental Property Bookkeeping Mistakes
- Mixing personal and rental property finances: Undermines record clarity and creates tax complications, always maintain separate accounts.
- Not documenting everything: Missing invoices and receipts mean missing deductions. Adopt a consistent habit of capturing documentation immediately.
- Miscategorising repair and capital improvement expenses: Repairs are deducted in full this year; improvements are depreciated over years. Getting this wrong affects multiple tax returns.
- Delaying tax filings: Rental income must be reported annually. Late filings on properties with multiple deductions and depreciation schedules create cascading complications.
- Improper security deposit handling: Security deposits held in trust are not income until forfeited. They should be held in a separate account and recorded as a liability, not revenue.
- Lacking internal controls: Even a small rental portfolio benefits from basic controls, documented processes for rent collection, expense approval, and monthly reconciliation.
At Profitjets, we work with landlords ranging from first-time investors with a single rental property to experienced owners managing large multi-property portfolios. While the complexity increases with the number of properties, the core principle remains the same: every financial transaction must be tracked accurately and consistently. We often see property owners who are diligent about collecting rent but lack complete records for repairs, maintenance, mileage, home office expenses, or capital improvements. Those missing records can significantly impact tax reporting and overall profitability.
We've also seen landlords discover substantial differences between their estimated returns and their actual returns once proper accounting systems were implemented. In many cases, the issue wasn't poor property performance, it was incomplete financial tracking. With organized books and property-level reporting, investors gain a clearer understanding of cash flow, return on investment, maintenance trends, and tax-saving opportunities.
Book a free consultation and we will set up per-property reporting.
Frequently Asked Questions
Is rental income taxable?
Yes. Rental income is taxable at your ordinary income tax rate and must be reported on Schedule E of your personal return. However, a range of deductions, mortgage interest, depreciation, repairs, insurance, management fees, and more, can significantly reduce your taxable rental income.
What expenses can landlords deduct?
Landlords can deduct: mortgage interest, property taxes, insurance, repairs and maintenance, property management fees, utilities paid by the landlord, legal and professional fees, advertising costs, and depreciation. Capital improvements are depreciated over time rather than deducted immediately.
How does depreciation work for rental properties?
Residential rental properties are depreciated over 27.5 years using the straight-line method. This means 1/27.5 of the property's cost basis (excluding land) is deducted each year. Depreciation reduces taxable income even in years when the property generates positive cash flow.
What is the difference between a repair and a capital improvement?
A repair maintains the property in its current condition (e.g., fixing a broken window, repainting) and is fully deductible in the year it occurs. A capital improvement adds value or extends the property's useful life (e.g., new roof, kitchen renovation) and must be depreciated over multiple years.
Do landlords need to keep security deposits in a separate account?
Yes, in most states, landlords are legally required to hold security deposits in a separate account and cannot use them as operating funds. Security deposits are a liability on your books (money you owe back to the tenant) and only become income if legally forfeited.
Conclusion
Rental property ownership is a long-term wealth-building strategy, and like any long-term investment, it rewards those who manage the details carefully. Proper bookkeeping ensures you claim every deduction you are entitled to, stay compliant with tax obligations, and have the financial visibility to make smart decisions about your portfolio.
Profitjets provides bookkeeping and accounting services tailored to rental property owners, from single-property landlords to multi-unit portfolio investors. Get in touch to find out how we can simplify your rental property finances.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Own More Than One Rental?
Book a free consultation and we will set up per-property reporting.