Many people would decline a raise, overtime pay, and even a bonus because, if they do, they will not have to pay as much federal income tax. That is wrong thinking, partly because it implies that the new tax bill--the amount of tax due would be substantially lower if the taxpayer's income fell just below a higher tax bracket. Actually, that simply is not the way the federal government's progressive income tax works.
What is happening is that the taxpayer is looking at his total tax bill as a single number--a $10,000 income, say and thinking that this will be taxed at one particular rate, such as 25 percent.
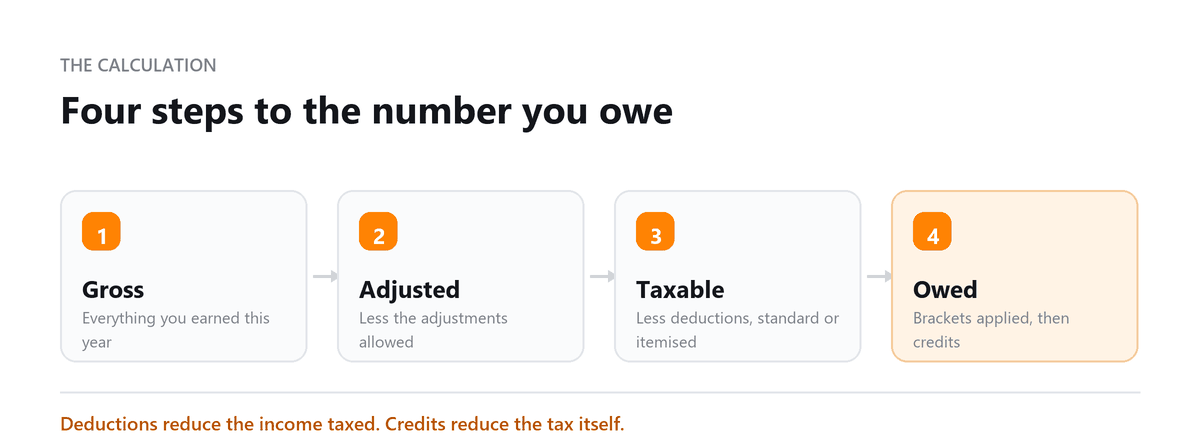
In fact, the progressive tax system is graduated--it has a series of steps, and the steps are applied to your taxable income. The calculation really is that simple: You take your gross income, subtract adjustments and exemptions, apply a series of graduated rates to the various slices of income, and then subtract tax credits.
Once you are comfortable with the way the tax code works, you can see how to take advantage of the different methods of reducing your tax bill: contributions to certain types of retirement funds and health savings accounts, for example, or itemized deductions.
Expert Perspective
This guide walks through how federal income tax is calculated step by step, the 2026 brackets, how FICA taxes differ from income tax, a full worked example, and practical ways to reduce what you owe.
The biggest misconception I hear is that your bracket is the rate on all your income. Someone in the 22 percent bracket assumes they're handing over 22 percent of everything, when their actual rate across all their income is often closer to 12 or 13 percent. I've had clients hesitate over a year-end bonus because of it. Once they see that only the extra dollars are taxed at 22 percent, and that a retirement contribution can pull some of those dollars back out, the decision gets much easier.
Ankit Sarawagi, CPA, CA, MBA · LinkedInThe Federal Income Tax Calculation at a Glance
| Step | Calculation | Result |
|---|---|---|
| 1 | Add up income from all sources | Gross income |
| 2 | Subtract adjustments to income | Adjusted gross income (AGI) |
| 3 | Subtract the standard or itemized deduction, plus other qualifying deductions | Taxable income |
| 4 | Apply the tax brackets to taxable income | Tax before credits |
| 5 | Subtract credits and add other taxes | Total tax |
| 6 | Compare with what you've already paid | Refund or balance due |
Step 1: Calculate Your Gross Income
Gross income includes income from almost every source, not just your paycheck. The most common types are:
Wages and salaries, reported on Form W-2, including bonuses and taxable fringe benefits.
Self-employment income, meaning net profit from a business or freelance work, reported on Schedule C.
Investment income, such as interest, dividends, and capital gains from selling investments.
Rental and royalty income, reported on Schedule E.
Other income, including gambling winnings, unemployment benefits, a taxable share of Social Security benefits, and alimony received under a divorce finalized before 2019.
Some income is excluded and never enters the calculation, such as gifts and inheritances you receive, most municipal bond interest, and life insurance proceeds paid to a beneficiary.
Step 2: Subtract Adjustments to Find Your AGI
Adjustments to income, often called above-the-line deductions, reduce your gross income to your adjusted gross income. You get them whether or not you itemize, which makes them especially valuable.
Common adjustments include:
Deductible traditional IRA contributions. The 2026 limit is $7,500, plus a $1,100 catch-up if you're 50 or older. Deductibility phases out at higher incomes if you or your spouse are covered by a workplace retirement plan.
Self-employed retirement contributions. SEP-IRA, Solo 401(k), and SIMPLE IRA contributions made by business owners.
HSA contributions made outside of payroll. The 2026 limits are $4,400 for self-only coverage and $8,750 for family coverage, plus $1,000 if you're 55 or older.
Half of self-employment tax, for anyone with self-employment income.
Self-employed health insurance premiums, subject to eligibility rules.
Student loan interest, up to $2,500, phasing out at higher incomes.
Your AGI matters well beyond this step. It's used to determine eligibility for many credits and deductions, so lowering it can unlock other tax benefits too.
Step 3: Subtract Your Deductions to Find Taxable Income
Next, subtract either the standard deduction or your itemized deductions, whichever is larger.
The Standard Deduction for 2026
| Filing Status | Standard Deduction |
|---|---|
| Single or married filing separately | $16,100 |
| Married filing jointly | $32,200 |
| Head of household | $24,150 |
Taxpayers who are 65 or older, or blind, get an additional standard deduction on top of these amounts.
Itemized Deductions
Itemizing makes sense when your qualifying expenses add up to more than the standard deduction. The main itemized deductions are mortgage interest, charitable contributions, medical expenses above 7.5 percent of AGI, and state and local taxes. The state and local tax deduction is capped at $40,400 for 2026 for most filers, with a lower cap for higher incomes.
Other Deductions Taken at This Stage
Two further deductions are subtracted here, and neither requires itemizing.
The qualified business income deduction allows many owners of sole proprietorships, partnerships, LLCs, and S corporations to deduct up to 20 percent of qualified business income, subject to limits at higher incomes.
New deductions for 2025 through 2028, created by legislation passed in 2025, include deductions for qualified tips, qualified overtime pay, interest on certain new car loans, and an additional deduction for taxpayers 65 and older. Each has its own dollar limits and income phase-outs.
What remains after all of this is your taxable income.
Step 4: Apply the Federal Income Tax Brackets
Federal income tax uses progressive brackets. Your taxable income is divided into slices, and each slice is taxed at its own rate.
2026 Federal Income Tax Brackets
| Rate | Single Filers | Married Filing Jointly |
|---|---|---|
| 10% | $0 to $12,400 | $0 to $24,800 |
| 12% | $12,401 to $50,400 | $24,801 to $100,800 |
| 22% | $50,401 to $105,700 | $100,801 to $211,400 |
| 24% | $105,701 to $201,775 | $211,401 to $403,550 |
| 32% | $201,776 to $256,225 | $403,551 to $512,450 |
| 35% | $256,226 to $640,600 | $512,451 to $768,700 |
| 37% | Over $640,600 | Over $768,700 |
These seven rates were made permanent by 2025 legislation. The income thresholds are adjusted for inflation every year.
Marginal Rate vs Effective Rate
Your marginal rate is the rate on your last, highest dollar of income. It's the bracket you're "in."
Your effective rate is your total income tax divided by your income. It's always lower than your marginal rate, because most of your income was taxed at lower rates on the way up.
Long-term capital gains and qualified dividends follow separate brackets, with rates of 0, 15, or 20 percent, so they're taxed differently from wages and business income.
Step 5: Subtract Credits and Add Other Taxes
Tax credits reduce your tax dollar for dollar, which makes them more valuable than deductions. A $1,000 deduction might save you $220 in the 22 percent bracket. A $1,000 credit saves you $1,000.
Common credits include the Child Tax Credit, which is $2,200 per qualifying child for 2025 and adjusted for inflation after that, the Earned Income Tax Credit, education credits, and the credit for child and dependent care expenses. Businesses may also qualify for credits like the research credit.
After credits, other taxes are added to reach your total tax. For business owners, the most significant is self-employment tax. Others include the additional Medicare tax and the net investment income tax for higher earners.
Step 6: Compare Your Tax With What You've Already Paid
Finally, your total tax is compared with what you've already paid through paycheck withholding and quarterly estimated tax payments. If you've paid more than your total tax, you get a refund. If you've paid less, you owe the difference when you file.
FICA Taxes: How They Differ From Income Tax
Employees also pay FICA taxes, which fund Social Security and Medicare. These are separate from federal income tax and work very differently.
| Tax | Employee Rate | Employer Rate | 2026 Earnings Limit |
|---|---|---|---|
| Social Security | 6.2% | 6.2% | First $184,500 of wages |
| Medicare | 1.45% | 1.45% | No limit |
| Additional Medicare tax | 0.9% | None | Wages over $200,000 single or $250,000 married filing jointly |
FICA rates are flat rather than progressive, they apply from the first dollar of wages, and the standard deduction and itemized deductions don't reduce them. Traditional 401(k) contributions lower your income tax but not your FICA tax, while certain pre-tax benefits, like health insurance premiums paid through an employer plan, reduce both.
Self-employed people pay both halves themselves as self-employment tax, a combined 15.3 percent calculated on 92.35 percent of net earnings, with the Social Security portion stopping at the annual earnings limit.
A Worked Example: Single Filer, 2026
Maria is single, earns a $91,100 salary, has no adjustments to income, and takes the standard deduction.
- Step 1: Gross income: $91,100
- Step 2: Adjusted gross income: $91,100
- Step 3: Taxable income: $91,100 − $16,100 standard deduction = $75,000
- Step 4: Apply the brackets
| Bracket | Income Taxed in This Bracket | Tax |
|---|---|---|
| 10% | $12,400 | $1,240 |
| 12% | $38,000 ($12,401 to $50,400) | $4,560 |
| 22% | $24,600 ($50,401 to $75,000) | $5,412 |
| Total federal income tax | $11,212 |
Maria's marginal rate is 22 percent. But her effective rate on taxable income is about 14.9 percent, and her effective rate on her full $91,100 salary is about 12.3 percent.
Now suppose Maria contributes $6,000 to a traditional 401(k). Her taxable income drops to $69,000, and all $6,000 comes out of her 22 percent bracket. Her federal income tax falls by $1,320, to $9,892.
How to Reduce Your Federal Income Tax
Contribute More to Retirement Accounts
For 2026, you can defer up to $24,500 into a 401(k), 403(b), or most 457 plans, plus an $8,000 catch-up if you're 50 or older, or $11,250 if you're between 60 and 63. Traditional contributions reduce taxable income in the year you make them.
Use a Health Savings Account
If you're enrolled in a high-deductible health plan, HSA contributions reduce taxable income, grow tax-free, and can be withdrawn tax-free for qualified medical expenses. Contributions made through payroll also avoid FICA taxes.
Check Whether Itemizing Now Makes Sense
With the higher SALT cap, some taxpayers who took the standard deduction in past years may now come out ahead by itemizing, especially homeowners in higher-tax states. It's worth running both calculations.
Offset Gains With Losses
Selling investments at a loss can offset capital gains, and up to $3,000 of net capital losses can offset ordinary income each year, with any remainder carried forward.
Plan the Timing of Income and Deductions
Deferring income into the next year, or accelerating deductions like charitable gifts into the current year, can keep more income out of a higher bracket. This works best when you expect your income or tax rate to change from one year to the next.
Claim Every Credit You Qualify For
Because credits reduce tax dollar for dollar, missing one costs more than missing a deduction of the same size. Review eligibility for family, education, and business credits each year.
Conclusion
Federal income tax isn't one rate applied to one number. It's a sequence: gross income, less adjustments, less deductions, taxed in slices, reduced by credits. Moving into a higher bracket only affects the dollars in that bracket, and your effective rate is almost always well below your marginal rate.
Understanding each step shows you where the real planning opportunities are, like retirement contributions, HSAs, itemizing when it pays, and credits, so you can make decisions about raises, bonuses, and savings with a clear picture of what they'll actually cost or save.
Book a free consultation and we will run the numbers properly.
Frequently Asked Questions
What is the federal income tax rate for 2026?
There are seven rates: 10, 12, 22, 24, 32, 35, and 37 percent. Which rates apply depends on your taxable income and filing status. Because the system is progressive, your overall effective rate is lower than your top bracket.
If I'm in the 22 percent bracket, do I pay 22 percent on all my income?
No. Only the portion of your taxable income that falls within the 22 percent bracket is taxed at 22 percent. The income below that is taxed at 10 and 12 percent. That's why a raise that moves you into a higher bracket always leaves you with more after-tax income, not less.
What is FICA, and how is it different from income tax?
FICA covers Social Security and Medicare taxes withheld from wages, at 6.2 percent and 1.45 percent for employees, with employers paying a matching share. Unlike income tax, FICA rates are flat, start with the first dollar of wages, and aren't reduced by the standard deduction or itemized deductions.
Why was my bonus taxed at such a high rate?
Employers often withhold federal income tax on bonuses at a flat 22 percent, and FICA is withheld on top of that. That's only withholding, though, not your final tax. When you file, the bonus is combined with the rest of your income and taxed through the normal brackets, so any over-withholding comes back as a refund.
What is the difference between a tax deduction and a tax credit?
A deduction reduces the income your tax is calculated on, so what it saves you depends on your marginal rate: a $1,000 deduction in the 22 percent bracket saves $220. A credit reduces the tax itself, so a $1,000 credit cuts your bill by $1,000 regardless of bracket. That is why a credit is usually worth more than a deduction of the same size.
Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Calculation Checked?
Book a free consultation and we will run the numbers properly.