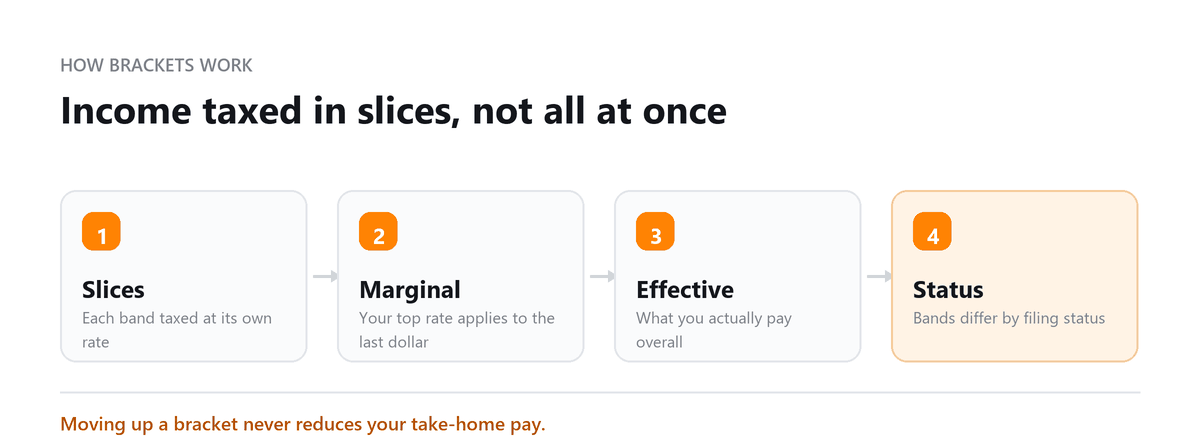
Every year, someone turns down overtime or worries about a raise because it might "push them into a higher tax bracket." It's one of the most persistent tax myths, and it costs people real money. Moving into a higher bracket never reduces your take-home pay, because the higher rate only applies to the dollars inside that bracket. Everything you earned below it is taxed exactly as it was before.
The confusion is understandable. Tax brackets are usually shown as a simple table, and it's easy to read "22 percent" and assume it applies to your whole income. In reality, the federal income tax system is progressive. Your taxable income is split into layers, and each layer is taxed at its own rate, starting at 10 percent and rising only as income climbs.
The brackets also shift every year. The IRS adjusts the income thresholds for inflation, so the same salary can land slightly differently from one year to the next. Legislation passed in 2025 made the current seven rates permanent, but the dollar ranges will keep moving.
This page brings together the current brackets, the prior year's brackets for anyone still filing, and a clear explanation of how to use them.
This guide covers the 2026 federal income tax brackets for all filing statuses, the 2025 brackets for returns being filed now, the standard deduction, how marginal and effective rates work,
2025 Federal Income Tax Brackets, Single Filers
| Tax Rate | Taxable Income (Single) | Tax Owed |
|---|---|---|
| 10% | $0 to $11,925 | 10% of taxable income |
| 12% | $11,925 to $48,475 | $1,192.50 + 12% over $11,925 |
| 22% | $48,475 to $103,350 | $5,578.50 + 22% over $48,475 |
| 24% | $103,350 to $197,300 | $17,651.50 + 24% over $103,350 |
| 32% | $197,300 to $250,525 | $40,199.50 + 32% over $197,300 |
| 35% | $250,525 to $626,350 | $57,231.50 + 35% over $250,525 |
| 37% | Over $626,350 | $188,769.75 + 37% over $626,350 |
Knowing your bracket tells you very little on its own. Your marginal rate tells you what the next dollar of income costs, or what the next deduction saves, and that's what should drive decisions about bonuses, retirement contributions, and business expenses. Your effective rate tells you what you actually pay across all your income, which is almost always far lower than people expect. Owners who understand both stop fearing a higher bracket and start using it to time income and deductions properly.
Ankit Sarawagi, CPA, CA, MBA · LinkedIn2025 Federal Income Tax Brackets, Married Filing Jointly
| Tax Rate | Taxable Income (MFJ) | Tax Owed |
|---|---|---|
| 10% | $0 to $23,850 | 10% of taxable income |
| 12% | $23,850 to $96,950 | $2,385 + 12% over $23,850 |
| 22% | $96,950 to $206,700 | $11,157 + 22% over $96,950 |
| 24% | $206,700 to $394,600 | $35,302 + 24% over $206,700 |
| 32% | $394,600 to $501,050 | $80,398 + 32% over $394,600 |
| 35% | $501,050 to $751,600 | $114,462 + 35% over $501,050 |
| 37% | Over $751,600 | $202,154.50 + 37% over $751,600 |
Standard Deduction (2025 Tax Year)
| Filing Status | 2025 Standard Deduction |
|---|---|
| Single | $15,000 |
| Married Filing Jointly | $30,000 |
| Head of Household | $22,500 |
| Married Filing Separately | $15,000 |
Marginal Rate vs Effective Rate
Your marginal tax rate is the rate on your last dollar of income. Your effective rate is your total tax divided by total income, always lower than your marginal rate due to the progressive structure.
Example: A single filer with $80,000 taxable income (TY2025) is in the 22% bracket. But their effective tax rate is approximately 15.6%, not 22%, because only income above $48,475 is taxed at 22%.
How to Calculate Your Federal Income Tax
Step 1: Work Out Your Taxable Income
Start with gross income from all sources, subtract adjustments such as deductible IRA and HSA contributions and half of self-employment tax, then subtract the standard deduction or your itemized deductions. Eligible business owners can also subtract the qualified business income deduction.
Step 2: Find Your Bracket
Use the table for the correct year and your filing status, and find the row that contains your taxable income.
Step 3: Apply the Formula in That Row
Take the fixed dollar amount shown, then add the percentage of income above the start of that bracket. For $80,000 of 2026 taxable income as a single filer, that's $5,800 plus 22 percent of $29,600, or $12,312.
Step 4: Subtract Credits and Add Other Taxes
Tax credits reduce the result dollar for dollar. Other taxes, such as self-employment tax, are added separately and don't use these brackets.
Income Taxed at Different Rates
Not all income runs through the ordinary brackets.
Long-term capital gains and qualified dividends are taxed at 0, 15, or 20 percent, depending on your taxable income. For 2026, the 0 percent rate generally applies up to $49,450 of taxable income for single filers and $98,900 for married couples filing jointly.
Net investment income tax of 3.8 percent applies to investment income for higher earners, above $200,000 for single filers and $250,000 for joint filers.
Self-employment tax of 15.3 percent applies to net self-employment earnings on top of income tax.
C corporation profit is taxed at a flat 21 percent at the corporate level.
Conclusion
The federal income tax system has seven rates, from 10 to 37 percent, but no one pays their top rate on all their income. Each layer of taxable income is taxed at its own rate, so your effective rate is always lower than your bracket suggests.
Use the right year's table, apply it to taxable income rather than gross income, and use your marginal rate to judge the real value of extra income and deductions. The rates are now permanent, but the thresholds change every year, so check the current table whenever you plan or file.
Book a free consultation and we will show you what you actually pay.
Frequently Asked Questions
What are the 2026 federal income tax brackets?
For single filers, the rates are 10 percent up to $12,400, 12 percent up to $50,400, 22 percent up to $105,700, 24 percent up to $201,775, 32 percent up to $256,225, 35 percent up to $640,600, and 37 percent above that. The tables above show the thresholds for every filing status.
Did tax brackets change for 2026?
The seven rates stayed the same and were made permanent by 2025 legislation, but the income thresholds were adjusted upward for inflation. For example, the 10 percent bracket for single filers now covers up to $12,400, compared with $11,925 in 2025.
What's the difference between marginal and effective tax rates?
Your marginal rate applies only to the top slice of your taxable income and shows the tax on your next dollar earned. Your effective rate is your total tax divided by your income, showing what you pay overall. Because of the progressive system, your effective rate is always lower.
Will a raise push me into a higher bracket and lower my take-home pay?
No. Only the portion of income that falls into the higher bracket is taxed at the higher rate. Your after-tax income always rises when your pre-tax income rises. Your paycheck withholding may change, but your total tax is calculated through the brackets when you file.
Which brackets do I use if I'm filing my return on extension in 2026?
Use the 2025 brackets. The bracket year always matches the year the income was earned, not the year you file. Returns for 2025 income use the 2025 tables, even when filed in October 2026.
Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Your Real Rate Worked Out?
Book a free consultation and we will show you what you actually pay.