
Even experienced filers make mistakes on 1099 forms. The IRS distinguishes between two error types and correcting the wrong way can create more problems than the original mistake.
A contractor calls in February to say the amount on their 1099 is wrong. A notice arrives from the IRS listing names and taxpayer ID numbers that don't match its records. Or the bookkeeper notices that office rent went out on a 1099-NEC instead of a 1099-MISC. None of these are unusual. Form 1099 pulls a full year of payments into a handful of forms, usually under January deadline pressure, and small data problems add up.
Most errors fall into a few categories: wrong payment amounts, wrong or missing recipient information, the wrong form type, forms that should never have been filed, and forms that were never filed at all. How you fix each one depends on the type of error. Some are corrected with a single corrected return. Others need the original form effectively reversed and a new one filed.
Leaving mistakes in place gets expensive. The IRS can charge penalties for each incorrect or late information return, a name and TIN mismatch can require you to start backup withholding, and recipients can end up with notices proposing tax on income they didn't receive. The good news is that penalties are lower when errors are corrected quickly, and very small dollar errors often don't need correcting at all.
This guide covers the most common 1099 filing mistakes, how to correct a form that's already been filed, how to respond to IRS mismatch notices, and how penalties work.
Understanding the Two Error Types
The IRS classifies 1099 corrections into two types based on what was incorrect:
| Error Type | What Was Wrong | Correction Method |
|---|---|---|
| Type 1 | Dollar amount, code, or checkbox, but payee name/TIN were correct | File a corrected return with the right figures |
| Type 2 | Payee name or TIN was wrong, or form was filed for the wrong person | Two-step correction: (1) file zeroed-out corrected form for the wrong payee; (2) file a new original return for the correct payee |
Never use a Type 1 correction method for a Type 2 error, f
iling only a corrected form with a new TIN will leave the original erroneous record active in IRS systems.
IRS Guidelines for Correcting Forms
- File corrected forms as soon as you discover an error, the penalty for late correction is lower than for non-correction
- Provide a corrected copy to the recipient on the same day you file with the IRS
- If you e-filed the original, you must e-file the correction (for filers of 10+ returns)
- If you paper-filed the original, you may paper-file the correction
- Use Form 1096 as a transmittal when submitting paper corrected returns
Filing Deadlines
| Action | Deadline (TY2025 returns) |
|---|---|
| Send 1099-NEC to recipients | January 31, 2026 |
| File 1099-NEC with IRS | January 31, 2026 |
| Send 1099-MISC to recipients | January 31, 2026 |
| File 1099-MISC paper to IRS | February 28, 2026 |
| File 1099-MISC electronically to IRS | March 31, 2026 |
| Internal preliminary reporting review | Recommended by December 15, 2025 |
Updated Penalty Schedule for 2025
| When Filed / Corrected | Per-Form Penalty |
|---|---|
| Within 30 days of original deadline | $60 per form |
| 31 days late to August 1 | $130 per form |
| After August 1 or not filed at all | $330 per form |
| Intentional disregard of filing requirement | $660 per form (no annual cap) |
Small business exception: businesses with average annual gross receipts of $5 million or less over the prior 3 years have lower annual caps on the first three penalty tiers. The intentional disregard penalty ($660/form) has no cap for any filer.
Common Mistakes That Trigger Corrections
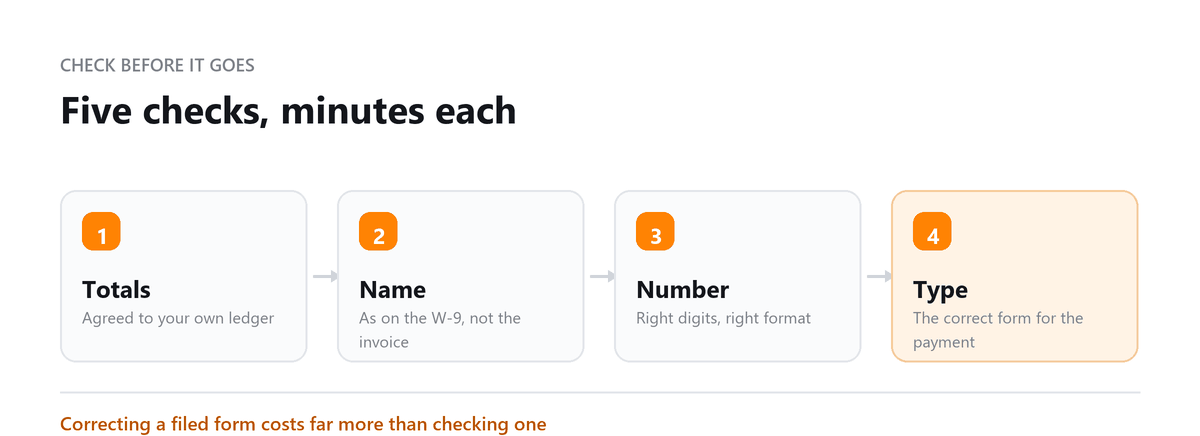
- Wrong TIN: Using a social security number when an EIN is required (or vice versa)
- Transposed amounts: Dollar figure entered in wrong box (e.g., Box 1 vs Box 7 on 1099-MISC)
- Missing 1099-NEC: Overlooking cash payments to contractors who were not set up as vendors in accounting software
- Wrong form version: Filing 1099-MISC for contractor payments instead of 1099-NEC (the separate forms have been required since 2020)
- No W-9 collected: Unable to issue correct TIN because W-9 was never obtained, triggers backup withholding obligation (24%) on future payments
Profitjets compliance audits reveal that 22% of newly onboarded vendor portfolios contain unverified W-9 details that require formal Type 1 or Type 2 corrections prior to year-end reporting.
2025 Traps: 1099-K and 1099-DA
1099-K: For the 2025 tax year, the reporting threshold is $20,000 and more than 200 transactions per platform not the lower $2,500 threshold originally scheduled to phase in. The One Big Beautiful Bill Act (signed July 4, 2025) repealed the planned reduction and restored the original higher threshold, retroactive to 2022.
Payment apps like PayPal, Venmo, Stripe, Square, and Etsy will only issue a 1099-K if both thresholds are crossed on that platform. Businesses that also separately issue 1099-NEC or 1099-MISC for the same contractor should still reconcile carefully to avoid double-reporting the same income, since the underlying income is taxable either way.
Step-by-Step: Fixing Paper vs Electronic Submissions
Paper correction:
- Obtain a blank 1099 form for the correct tax year (print from IRS.gov or order free forms via IRS.gov/orderforms)
- Check the 'CORRECTED' box at the top
- Enter the payee's correct information and correct amounts
- Attach Form 1096 (transmittal) and mail to the correct IRS processing center
- Send a corrected copy to the recipient simultaneously
Electronic correction:
- Log in to the IRS FIRE system or use your 1099 e-file software
- Submit a 'C' (correction) record type for Type 1 errors
- For Type 2 errors: submit a zeroed 'G' (correction) record for the wrong payee, then a new original 'A' record for the correct payee
By executing automated Taxpayer Identification Number (TIN) matching before official deadlines, Profitjets helps client organizations eliminate up to 95% of avoidable 1099 late-correction penalties.
During an onboarding audit for a growing agency client, we discovered they had filed 14 Form 1099-NEC returns with mismatched EINs and swapped entity names. Because their internal team attempted to fix this using a standard single-form adjustment, the initial incorrect records remained active in the IRS system, triggering automated CP2100 B-Notices and impending penalty notices.
We stepped in to execute the proper two-step Type 2 correction process zeroing out the original records before submitting clean, newly validated filingswhich cleared the system mismatch and eliminated over $4,700 in potential penalty liability.
Most 1099 corrections come back to one of two causes. Either the vendor record in the accounting system didn't match the W-9, or payments made by card or payment app were included even though the processor already reported them. Both are easy to prevent with a proper vendor setup process, and both are far more painful to unwind after the forms are filed and the IRS has already matched them.
Ankit Sarawagi, CPA, CA, MBA · LinkedInFrequently Asked Questions
Book a free consultation and we will get the filings clean.
FAQs
How do I correct a 1099 that's already been filed?
File a corrected form marked "CORRECTED" with the IRS and send a copy to the recipient. Errors like a wrong amount or an incorrect checkbox can generally be fixed with one corrected return. Other errors, such as a wrong taxpayer ID number, a wrong payee name, or using the wrong type of form, may require more than one step, particularly for paper filers. Follow the current IRS General Instructions for Certain Information Returns for the exact procedure for your error type.
What is a B-notice, and what do I have to do?
A B-notice is part of the IRS backup withholding process. When the IRS finds that a recipient's name and taxpayer ID number don't match its records, it sends the payer a notice, often a CP2100 or CP2100A, listing the mismatches. You generally must send a first B-notice and a blank Form W-9 to each affected payee within 15 business days. If you don't receive a corrected W-9 within 30 business days, you must begin backup withholding at 24 percent on future payments.
A second mismatch within three years requires the payee to get their number validated by the Social Security Administration or the IRS.
Is there a penalty for filing an incorrect 1099?
Yes. Incorrect returns are generally penalized the same way as late returns, with a penalty for each form. The amount is lower if you correct the error within 30 days after the due date or by August 1, and higher if you correct it later or not at all. Penalties are adjusted for inflation each year and are significantly higher for intentional disregard of the filing rules.
Do I have to correct a very small error on a 1099?
Often not. Under a de minimis safe harbor, errors in a dollar amount of $100 or less, or $25 or less for tax withheld, generally don't need to be corrected and won't trigger a penalty. The exception is when the recipient asks for a corrected form, in which case you must issue one.
What should I do if I forgot to send a 1099 entirely?
File it and send the recipient's copy as soon as possible. The penalty for a late information return is tiered, so it grows the longer the form goes unfiled. Filing voluntarily before the IRS contacts you generally keeps the penalty lower and gives the recipient time to report the income correctly.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Corrections Piling Up?
Book a free consultation and we will get the filings clean.