
Every entrepreneur has experienced the thrill of a month that went spectacularly bad. Their biggest customer paid three weeks late, the van they rely on had a transmission repaired, and the quarterly tax payment was due on Friday. With no cash on hand, the options are unappealing: cashing out of a credit line at an expensive rate, negotiating with suppliers, delaying payroll, or even laying off some workers in the worst case.
With a cash reserve, the stress of such a scenario is alleviated since there is time to come up with a solution to the problem. The delayed customer payment will now be a minor hiccup, the repair funds will come out of the reserve, and no changes to the payroll schedule will need to be made.
The simplest truth is that having too small of a cash reserve is as bad as having too large of one. Too small, and the reserve is depleted during the first rough month. Too large, and the entrepreneur is sitting on cash that could have been invested back into the business. How much is enough? It all depends on the business’s predictability and seasonality.
This guide explains what a business cash reserve is, why it matters, how much different types of businesses typically need, and how to build and maintain one.
What Is a Business Safety Net / Cash Reserve?
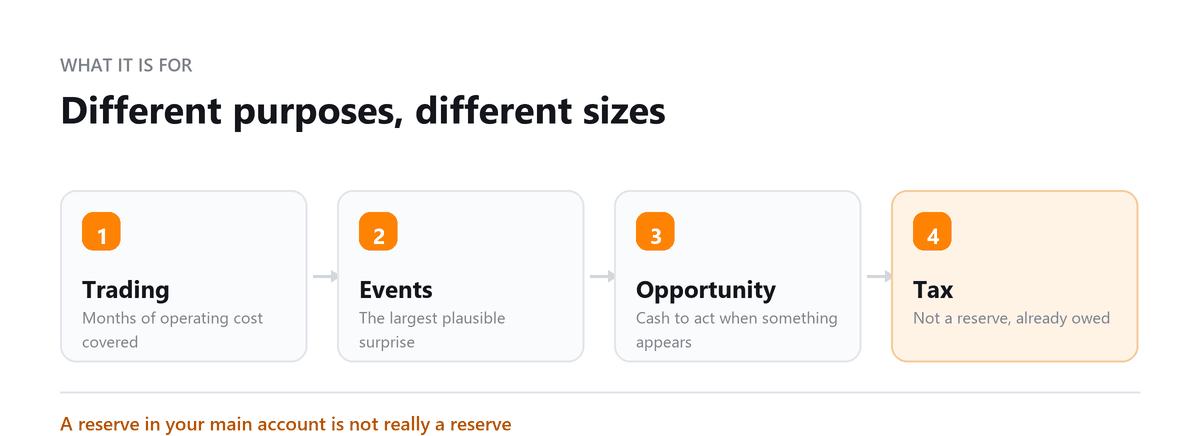
A business cash reserve, sometimes called a safety net, emergency fund, or operating reserve, is money set aside specifically to cover unexpected costs or shortfalls in revenue. It's usually kept in a business savings or money market account where it's easy to reach but separate from everyday spending.
It helps to separate the reserve from two other pools of cash. Operating cash is the money in your checking account used for day-to-day payments like payroll and suppliers. Capital reserves are funds set aside for planned purchases, such as new equipment or a vehicle. A cash reserve is neither of those. It exists for the things you didn't plan for.
Why Your Business Needs a Cash Reserve
Revenue Doesn't Arrive Evenly
Almost every business has months where revenue falls short of plan. Seasonal dips, customers who pay late, lost accounts, and delayed projects all create gaps between the money you expected and the money you received.
Unexpected Costs Happen
Equipment breaks down, emergency repairs come up, legal disputes arise, and sometimes a critical hire can't wait. None of these show up in the budget, but all of them need to be paid.
Growth Consumes Cash First
When a business grows quickly, it usually has to pay for inventory, people, and space before the extra revenue comes in. A reserve helps fund that gap without borrowing at a bad moment.
Lenders and Suppliers Notice
Banks and suppliers look at your cash position when deciding what terms to offer. A business with a healthy reserve generally looks lower-risk and gets better terms than one that's always running close to zero.
It Leads to Better Decisions
Without a reserve, every month becomes a cash management exercise. With one, you can think about strategy instead of scrambling to cover the next set of bills.
How Much Cash Does Your Business Really Need?
| Business Type | Recommended Reserve | Rationale |
|---|---|---|
| Freelancer / sole trader | 3 months of personal + business expenses | Low fixed costs; income is variable month to month |
| Small service business (stable clients) | 2-3 months of operating expenses | Predictable revenue; lower inventory risk |
| Product business (inventory-dependent) | 3-4 months of operating expenses | Inventory purchases require cash ahead of sales |
| Startup (pre-profitability) | 6-12 months of runway | Revenue unpredictable; fixed costs continue regardless |
| Seasonal business | Enough to cover the entire off-season | Revenue may be near-zero for 3-6 months; operating costs continue |
The 'months of operating expenses' measure covers: fixed costs (rent, salaries, insurance, debt service) + average variable costs at a minimal trading level. It does not include owner's draw, that is a separate personal emergency fund consideration.
Most small businesses I work with are holding far less in reserve than they think they are. They look at the bank balance and feel covered, but once you subtract payroll, rent, and what's due to suppliers in the next few weeks, the real buffer is often a matter of days, not months. The businesses that get through a bad quarter calmly are the ones that decided on a reserve target and built it on purpose, not the ones that hoped the balance would be there.
Ankit Sagatani, MBA, B.Com · LinkedInHow to Build and Maintain Your Cash Reserve
- Set a target first: calculate your monthly operating expenses and multiply by your target reserve period (3 months, 6 months, etc.)
- Save 5-10% of net monthly profit into the reserve account until the target is reached automate this transfer so it happens before discretionary spending
- Keep it separate: the reserve should be in a dedicated savings account, not the operating account accessibility but not temptation
- Replenish after use: if you draw on the reserve, treat restoring it to target as a priority before resuming profit distributions
- Review annually: as the business grows, the monthly expense base increases your reserve target should grow with it
Across Profitjets onboarding reviews, approximately 35% of new clients have less than one month of operating expenses held in cash reserves. After 12 months of structured cash-flow planning, budgeting, and reserve management, clients maintain an average of 3.5 months of operating expenses in reserve, giving them a stronger buffer against unexpected costs and revenue fluctuations.
How to Calculate Your Monthly Operating Expenses
To turn those ranges into a dollar figure, start with the cash your business needs to keep running each month. Include fixed costs like rent, salaries, insurance, software, and loan payments, along with the variable costs you'd still have even in a slow month.
Leave out the owner's draw. Your personal emergency fund should be handled separately, so the business reserve is sized purely around keeping the business itself running.
Then multiply by your target. If your business needs $40,000 a month to operate and you're a product business aiming for three months, your reserve target is $120,000.
Book a free consultation and we will work out what you need.
Frequently Asked Questions
Where should I keep my business cash reserve?
Keep it in an interest-earning account you can access without penalties, such as a business savings or money market account at your bank. Some businesses also use fintech platforms that sweep deposits to partner banks. If you go that route, confirm the provider's FDIC coverage arrangements and how quickly you can move money when you need it. Interest rates change often, so compare current rates rather than relying on a figure you saw months ago.
Is a cash reserve the same as a business emergency fund?
For most small businesses, yes. The terms are used interchangeably. What matters more is keeping the reserve separate from your operating account, so you can clearly see how much is available for daily expenses and how much is set aside as a buffer.
Can a line of credit replace a cash reserve?
It can support one, but it's not a true replacement. A credit line is useful for short-term timing gaps, but banks can reduce or freeze lines when business conditions worsen, which is often exactly when you need the money. It also costs interest. The strongest position is a cash reserve for emergencies, with a credit line as a second layer of protection.
Can a business hold too much cash in reserve?
Yes. Once your reserve comfortably covers your target, extra cash sitting idle may be better used paying down expensive debt, investing in growth, or distributed to owners. The goal is enough protection to handle realistic setbacks, not to hoard cash the business could put to work.
What if my business can't afford to build a reserve right now?
Start small. Even a few weeks of operating expenses is far better than nothing. Set aside a modest fixed amount each month, and add larger amounts after strong months or when a big payment comes in. At the same time, work on the cash flow basics, like faster invoicing and better supplier terms, which make building the reserve easier.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
No Reserve at All?
Book a free consultation and we will work out what you need.