The US business bank account takes center stage. Stripe funds cannot be disbursed to, payroll not paid from, and the liability protection of your LLC not secured by an account in the company's name, which is segregated from your personal funds.
For a founder based outside of the US, it is also the point in the incorporation process where things stop being easy and scripted and start depending on the idiosyncratic whims of a bank employee.
This guide covers the options available, what they cost, and, critically, the reasons why applications can be denied and accounts frozen, often with little transparency.
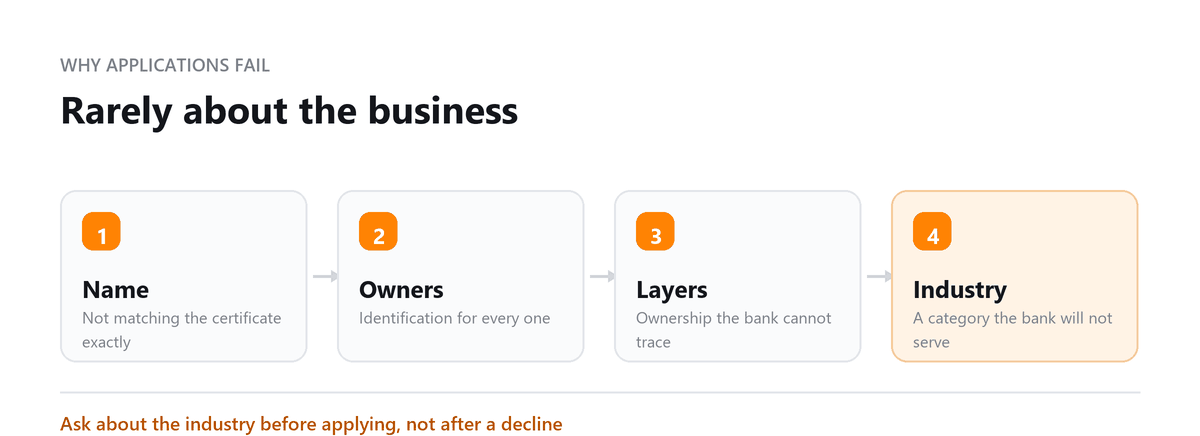
The mistake is treating the bank application like paperwork. It's a risk assessment, and the thing that sinks foreign-founder applications is inconsistency, an address on the formation documents that doesn't match the one on the application, a business description that doesn't match what the website shows, a director's name spelled differently in two places. None of it is dishonest. It just reads as unresolved to a compliance reviewer, and unresolved applications get declined without explanation.
Ankit Sagatani, MBA, B.Com · LinkedInRequirements to Open a US Bank Account for Businesses
All US business bank accounts require basic entity documentation. The exact list varies by bank, but typically includes:
| Document | Purpose |
|---|---|
| Articles of Incorporation / Organisation | Proves the entity is legally formed in the US |
| EIN (Employer Identification Number) | The business's tax ID, required by all banks |
| Operating Agreement / Bylaws | Documents ownership structure and authorised signatories |
| Government-issued ID for each owner/officer | Identity verification, passport accepted for foreign nationals |
| Business address | Some banks accept registered agent address; others require a physical operating address |
| Social Security Number or ITIN (for some banks) | Required by traditional banks; neobanks often accept passport + EIN only |
Benefits of Opening a Bank Account in the United States
- Separate business and personal finances, essential for LLC liability protection and clean tax filings
- Receive US payments from customers, investors, and grants without international transfer friction
- Access US payment processors (Stripe, PayPal, Square) at standard rates, foreign accounts face higher fees
- Issue and receive ACH transfers, the standard for US payroll, vendor payments, and B2B transactions
- Build US business credit history, required for business loans, corporate credit cards, and vendor credit terms
- Hold investor funds in escrow or corporate account for clean cap table management
Which Bank is Best for Business Accounts in the US?
Traditional Banks, Best for Established Businesses with US Presence
| Bank | Monthly Fee | Best For |
|---|---|---|
| Chase Business Complete Banking | $15/month (waivable with $2,000 balance) | Local businesses with branch needs; 4,700+ branches |
| Bank of America Business Advantage | $16/month (waivable) | Businesses wanting full-service traditional banking |
| Wells Fargo Initiate Business Checking | $10/month (waivable) | Small businesses with low transaction volume |
Neobanks, Best for Remote and Foreign-Owned US Entities
| Neobank | Monthly Fee | Best For |
|---|---|---|
| Mercury | $0 | Startups and foreign-owned US entities, fully remote account opening, no SSN required |
| Relay | $0 (or $30/month Pro) | Small businesses wanting organised multi-account banking |
| Brex | $0 (cash management) | VC-backed startups, integrates with cap table and expense management |
| Bluevine | $0 (or $15/month Plus) | Small businesses wanting business checking + competitive APY on balances |
USA Business Banking Fees
Common business banking fees to compare:
| Fee Type | Typical Range |
|---|---|
| Monthly maintenance fee | $0 (neobanks) to $25 (traditional premium accounts) |
| ACH transfer | $0 (most accounts) |
| Wire transfer (domestic) | $15 to $30 per outgoing wire |
| Wire transfer (international) | $25 to $50 per outgoing wire |
| Overdraft fee | $0 (neobanks) to $35 (traditional banks) |
| Cash deposit (at branch/ATM) | Varies; neobanks often do not accept cash deposits |
| Minimum balance requirement | $0 (neobanks) to $25,000+ (premium accounts) |
Why applications fail, and what to do about it
This is the part comparison pages leave out, and it's what actually determines whether you get an account.
Inconsistent information. The most common cause by some distance. An address on your formation documents that differs from the one on the application. A company name spelled slightly differently. A director's name in a different order than on their passport. A business description that doesn't match what your website says you do. None of it is deception; it reads as unresolved, and compliance reviewers decline unresolved applications rather than investigating them.
Fix: before applying, put your formation certificate, EIN letter, operating agreement, passports and website side by side and make every detail match exactly.
Vague business descriptions. "Consulting" or "technology services" invites questions. Specific descriptions that align with your website and your actual customers don't.
High-risk classification. Crypto, gambling, adult content, certain money services, some CBD and pharmaceutical categories, these get declined or offboarded across most platforms regardless of legitimacy. If you're near one of these, establish that before you build a plan around an account.
Address arrangements that look evasive. Virtual addresses are widely used and generally fine. What causes problems is using one while implying a physical operation, or using an address shared with hundreds of other entities without acknowledging it. Be straightforward about the arrangement.
Book a free consultation and we will get the paperwork in order.
Frequently Asked Questions
Can a non-US resident open a US business bank account?
Yes. Traditional banks typically require an SSN or ITIN and often an in-person visit, which rules most out. Platforms like Mercury and Relay onboard remotely using passport identification and the EIN, which makes them the practical route for Indian and other international founders. Verify current eligibility before relying on any of them, since criteria for foreign-owned entities have tightened over time.
How long does it take?
Usually a few business days on the fintech platforms once you have the EIN, longer if the application goes to manual review which foreign-owned entity applications frequently do. Traditional banks may open same-day in branch for a straightforward domestic application, but rarely for a foreign-owned entity. The real timeline is the EIN wait beforehand, not the account opening.
Do I need a US bank account if I use Stripe or PayPal?
Yes, eventually and usually immediately. Stripe needs a US bank account to disburse funds for a US entity. PayPal allows a business account without one initially, but withdrawal requires one. Neither is a substitute for a bank account; they sit on top of it.
What if my application is declined?
You generally won't be told why, which is standard for compliance decisions rather than a slight. Check your documentation for inconsistencies first: mismatched addresses and name variations account for most of it. Then apply elsewhere with the corrected pack. Repeated applications with the same unresolved detail produce the same result, so fix before reapplying.
Can I use my registered agent's address for the bank account?
Some providers accept it, others want an operating address. Where a virtual or agent address is used, declare it as what it is. Problems arise from a mismatch between what's declared and what verification finds, not from the arrangement itself.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Struggling to Open an Account?
Book a free consultation and we will get the paperwork in order.