
Maintaining precise financial records is vital for every business. As small businesses focus on working capital, their monthly reports and balance sheets,their ledgers are the repository for all the financial transactions. Knowing how ledger accounting and ledger bookkeeping serves its purpose each on its own and together is essential for small business owners. When consistently maintained, ledgers become the necessary tools to help navigate the business financial health and standpoint.
This article covers the meaning of ledger accounting, key differences between ledger accounting and bookkeeping and types of ledgers to help small business owners make the right financial decision for their organizational purpose.
When we first onboard clients at Profitjets, we review the overall structure and quality of their ledger after the discovery call. We further detect the gaps and inconsistencies in the repository to help small business owners analyze their exact financial condition. As these issues tend to disrupt the overall financial view without the help of an expert, it's significant to resolve the challenges by structuring a clean, organized ledger.
Most small business owners track their bank balance, but that is not the same as understanding your ledger. The ledger is where you see exactly what is happening with every account, and it is the foundation of every sound financial decision.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is a Ledger?
A ledger is a book, physical or digital, with dedicated sections for individual accounts. Each account tracks its financial journey through debits and credits. Think of it as the master record of all your financial activity, organised by account type so you can see exactly where every dollar has gone.
What is Ledger Accounting?
Ledger accounting is the process of recording, organising, and maintaining these accounts. It serves as the central repository where all journal entries find their permanent home, categorised by specific accounts such as cash, inventory, or salaries payable. Every transaction your business records ultimately flows through the ledger.
Why is Ledger Accounting Important?
Ledger accounting serves three critical functions for any business:
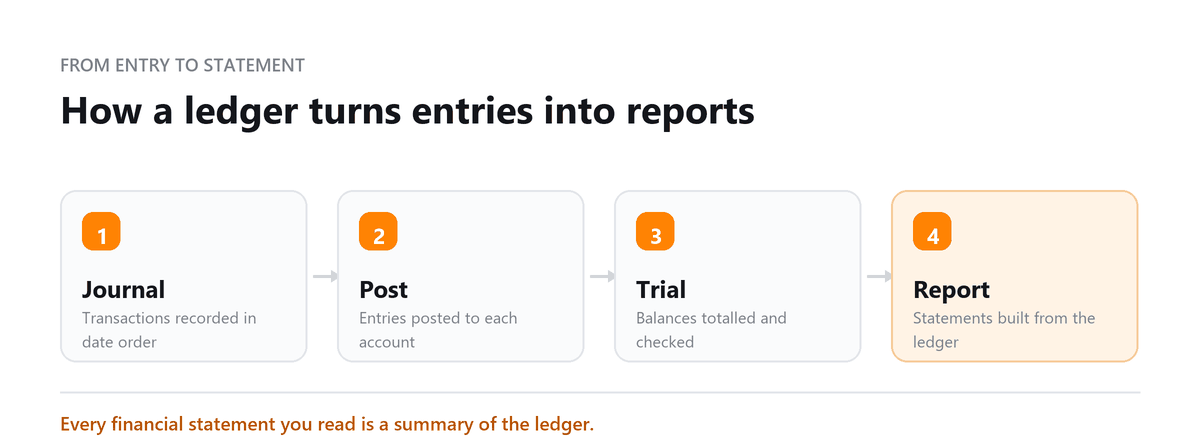
- Creating financial statements, your balance sheet and income statement are built directly from ledger data
- Enabling internal controls, the ledger creates an audit trail that makes errors and fraud far easier to detect
- Supporting business decisions, by analysing ledger data, owners and managers can spot trends and make informed choices
Types of Ledgers
General Ledger
The general ledger is the primary ledger in any accounting system. It contains a summary of all financial transactions across every account category, assets, liabilities, equity, income, and expenses. Every transaction recorded in your books ultimately lands in the general ledger.
Subsidiary Ledgers
Subsidiary ledgers provide detailed tracking for specific areas of the business. For example, an accounts receivable subsidiary ledger lists every individual customer balance that rolls up into the single accounts receivable line on your general ledger. Common examples include accounts payable, accounts receivable, and inventory ledgers.
Ledger Accounting and the Double-Entry System
Ledger accounting is inseparable from double-entry bookkeeping. For every dollar flowing in, another dollar finds its home elsewhere, ensuring the books always balance. Each transaction affects at least two ledger accounts: one is debited and one is credited by the same amount. This self-balancing principle is what makes ledger accounting reliable and auditable.
Ledger Accounting vs. Bookkeeping: What is the Difference?
People often use these terms interchangeably, but they describe different levels of financial work:
| Feature | Ledger Accounting | Bookkeeping |
|---|---|---|
| Focus | Analysis and interpretation of financial data | Recording and classification of financial transactions |
| Output | Financial statements, management reports | Trial balance, organised ledgers |
| Who does it | Accountant or senior bookkeeper | Bookkeeper |
| Timing | Periodic (monthly, quarterly, annual) | Ongoing (daily or weekly) |
Modern Ledger Accounting: Going Digital
Today, very few businesses maintain physical ledgers. Modern accounting software, such as QuickBooks, Xero, and FreshBooks, handles ledger accounting automatically, offering real-time updates, automated calculations, and secure cloud storage. When a sale is recorded, the software debits your cash or accounts receivable account and credits your revenue account instantly, keeping your ledger up to date without manual entry.
Book a free consultation and we will keep the ledger clean and reconciled.
Frequently Asked Questions
What is the difference between a journal and a ledger?
A journal is where transactions are first recorded in chronological order (the book of original entry). A ledger then takes those journal entries and organises them by account. Think of the journal as a diary and the ledger as an organised filing system.
Do I need a general ledger if I use accounting software?
Yes, your accounting software maintains a general ledger automatically in the background. Even if you never look at it directly, every report you run (P&L, balance sheet, cash flow) is pulling data from it. Understanding how it works helps you catch errors faster.
How often should I update my ledger?
Ideally, transactions should be recorded as they happen, or at minimum weekly. The longer you leave it, the harder it becomes to reconcile accounts accurately. Monthly catch-up bookkeeping is common but increases the risk of missed entries.
What happens if my ledger does not balance?
If your ledger does not balance, it means a debit and credit entry are mismatched somewhere. This must be investigated and corrected before producing any financial statements. Common causes include data entry errors, missed transactions, or incorrect account classifications.
Can a small business use a spreadsheet as a ledger?
Yes, a simple spreadsheet can work for a very small business with minimal transactions. However, as the business grows, manual spreadsheet ledgers become error-prone and hard to reconcile. Accounting software is strongly recommended once you have more than a handful of transactions per month.
Conclusion
Ledger accounting is not just a technical accounting concept, it is the foundation of every financial decision your business makes. Whether you are using spreadsheets, cloud software, or working with a professional bookkeeper, understanding how your ledger works gives you clarity, control, and confidence in your numbers. If your ledger is a mess, your financial reporting will be too, and that is a risk no business owner should take.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Your Ledger Kept Accurate?
Book a free consultation and we will keep the ledger clean and reconciled.