Sole traders begin bookkeeping as a basic function in the beginning. They have to take care of everything from start to finish on their own. Without any help from the internal team, sole traders are in a critical role to detect and resolve inaccurate books. When financial processes become more complex, they tend to aim on the main factors that drive the business.
Facilitating the functions to customers, finishing projects on due date and producing ROI. Majority of them keep on delaying the bookkeeping process until the situation is demanding. However the delay compounds to a crisis when the tax season is approaching. Expensive problems keep emerging on taxation deadlines, compliance and errors that are too difficult to resolve in the rush. Good Bookkeeping clearly provides the financial picture to keep track of the money and transactions to strategize better.
This guide clearly explains the bookkeeping for sole traders, explaining the taxes they need to pay, expensive errors and tips to maintain an effective bookkeeping process.
Sole traders have the least financial cushion of any business structure, which makes accurate bookkeeping more important, not less. The numbers in your books are not just compliance data; they are the early warning system for problems that could put your personal assets at risk.
Abhinav Gupta, CPA, CA, MBA · LinkedInWho is a Sole Trader?
A sole trader (also called a sole proprietor in the US) is an individual who owns and operates a business as a single, unincorporated entity. Key characteristics:
- Complete control: All business decisions rest with the owner
- Retain all profits: No shareholders or partners to share income with
- Unlimited personal liability: Business debts and obligations are the owner's personal responsibility
This structure is common for freelancers, tradespeople, consultants, and small service businesses.
Why Accounting Matters for Sole Traders
Because sole traders blend business and personal finances more easily than any other structure, disciplined accounting is essential. Core functions include:
- Invoicing: Creating accurate, professional invoices for all work completed
- Accounts receivable monitoring: Tracking who owes you money and following up on overdue invoices
- Accounts payable tracking: Managing what you owe to suppliers and service providers
- Expense logging: Recording every business expense with supporting documentation
- Depreciation: Accounting for the wear and cost of business equipment over time
- Financial statement analysis: Understanding your income, expenses, and net profit over time
How to Invoice as a Sole Trader
Every sole trader invoice should include the following eight elements:
- Your business name, address, and contact details
- Client name and address
- A unique invoice number (for your records and theirs)
- Invoice date and payment due date
- Clear description of services provided
- Itemised costs for each service or product
- Payment terms (e.g. 14 days, 30 days, late payment policy)
- Total amount due, including any applicable taxes
What Taxes Does a Sole Trader Pay?
Personal Income Tax
Sole traders pay income tax on their net business profit (revenue minus deductible expenses). Common deductible expenses include:
- Operating costs: rent, utilities, office supplies
- Equipment purchases (or depreciation for larger items)
- Accounting and professional fees
- Advertising and marketing costs
- Business insurance
Self-Employment Tax
In addition to income tax, sole traders in the US pay self-employment (SE) tax on net earnings. SE tax covers both the employer and employee portions of Social Security and Medicare contributions. The deductible half of SE tax can be deducted from gross income when calculating income tax.
How Sole Trader Accounting Differs from Other Structures
- Less complex but more personally vulnerable: Errors directly affect personal finances
- Limited resources: No dedicated finance team, the owner often handles everything
- Mixed personal and business spending: Vigilance required to keep finances separate
- Informal processes: Easy to let bookkeeping slip, discipline must be self-imposed
- Tax planning challenges: No corporate tax rate advantage; all profit is taxed as personal income
Setting Up Effective Bookkeeping Systems
Follow these eight steps to build a bookkeeping system that works:
Step 1: Choose Your Approach
Decide between DIY (using software), a part-time bookkeeper, or an outsourced bookkeeping service. The right choice depends on your transaction volume and your comfort with numbers.
Step 2: Open a Dedicated Business Bank Account
Never mix personal and business transactions. A separate account is the single most important bookkeeping action a sole trader can take.
Step 3: Categorise Your Transactions
Every transaction should be assigned to a category: income, office expenses, travel, equipment, marketing, professional services, and so on.
Step 4: Set Up Your Chart of Accounts
Create a simple list of income and expense categories that reflect your specific business activities.
Step 5: Choose Single or Double Entry
Single-entry bookkeeping (one entry per transaction) is simpler and suits most sole traders. Double-entry (debits and credits) is more accurate and required if you ever incorporate.
Step 6: Record Transactions Promptly
Enter transactions weekly, not monthly. The longer you wait, the more context you lose and the more errors creep in.
Step 7: Reconcile Your Accounts
Match your bank statements to your records every month. Identify and investigate every discrepancy.
Step 8: Analyse Your Reports
Produce a monthly income and expense summary. Review it: are costs rising? Is income growing? Are there months where cash flow dips predictably?
Tips for Effective Sole Trader Bookkeeping
- Reconcile monthly, do not let bank statements accumulate
- Track all expenses in real time using a mobile app or cloud software
- Keep business and personal finances strictly separate
- Seek expert guidance from an accountant at least once a year for tax planning
- Evaluate your system periodically, as your business grows, your needs change
- Upgrade your software selectively, add tools only when the business benefit is clear
Best Bookkeeping Software for Sole Traders
| Software | Best For |
|---|---|
| Microsoft Dynamics GP | Diverse industries, CRM, financial reporting, payroll, project accounting |
| OneUp | Entrepreneurs, accounting, invoices, proposals, task management, customer data |
| ZipBooks | Service professionals, invoicing, expense tracking, basic reporting |
| Acumatica Cloud ERP | Growing businesses, financial management, inventory, CRM, HR |
Common Sole Trader Bookkeeping Mistakes
- Mixing business and personal expenses, creates tax headaches and obscures true profitability
- Failing to capture all income, cash payments, barter arrangements, and platform income are all taxable
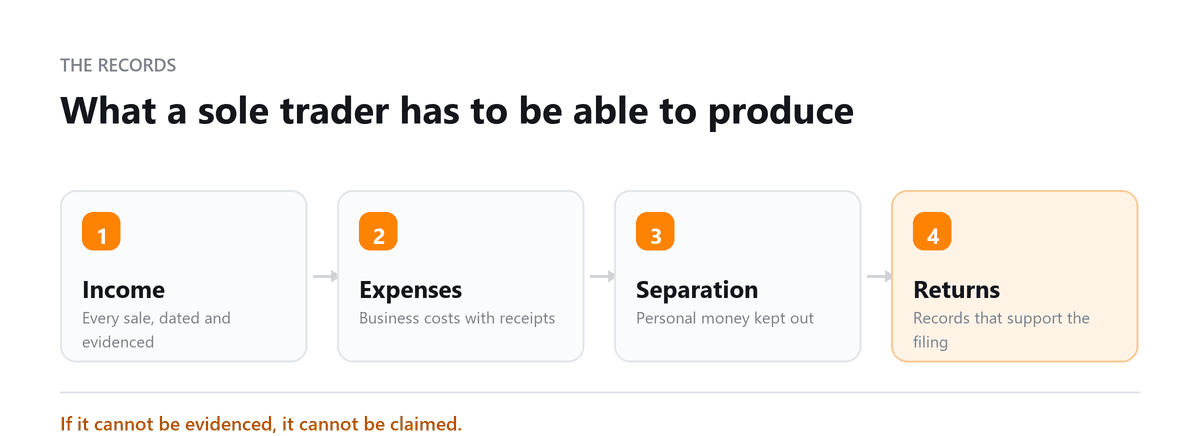
- Insufficient documentation, no receipt means no deduction in the event of an audit
- Delayed data entry, weekly entry takes minutes; monthly entry takes hours
- Inaccurate coding, assigning expenses to the wrong category distorts your financial picture and can cause tax errors
Book a free consultation and we will keep them filing-ready all year.
Frequently Asked Questions
Do sole traders need to keep receipts?
Yes. Every business expense requires documentary evidence to be deductible. Keep digital or physical copies of all receipts, invoices, and bank statements. Most tax authorities require records to be kept for at least five to seven years.
What is the simplest accounting method for a sole trader?
Cash-basis accounting is the simplest method, you record income when you receive it and expenses when you pay them. It is straightforward to manage and suitable for most sole traders with modest transaction volumes.
Do I need accounting software as a sole trader?
A spreadsheet is sufficient for very simple businesses, but cloud accounting software saves significant time as your transaction volume grows, reduces errors, and makes tax filing much easier. Many platforms offer plans designed specifically for sole traders.
Can a sole trader claim a home office deduction?
Yes, provided you use part of your home regularly and exclusively for business. The deduction can be calculated using the simplified method (a flat rate per square foot) or the actual expense method. Keep records of your home's total size and the dedicated business space.
When should a sole trader hire a bookkeeper?
Consider bringing in help when bookkeeping is taking more than a few hours per month, when you are not confident about tax obligations, or when the business is growing faster than your financial systems can keep up with.
Conclusion
Sole trader bookkeeping does not need to be complicated, but it does need to be consistent. A simple, well-maintained system protects your deductions, keeps you compliant, and gives you the financial clarity to grow your business with confidence. Start with the basics, build good habits, and scale your systems as your business grows.
Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Want the Records Kept for You?
Book a free consultation and we will keep them filing-ready all year.