
Bookkeeping is the system of organizing and recording every day transactions of a business. It forms a repository for the business to track their records and make sound informed decisions. Understanding bookkeeping will help small business owners navigate their financial strain with clarity. Bookkeeping helps small business owners to track their financial activity and streamline expansion. Clean Bookkeeping enables them to identify the cash flow constraints and help accelerate their tax filing season without any financial strain.
This article explains the basic terms in bookkeeping that each business owner should know to maintain their financial hygiene in the process. Each term is explained with an example to help you understand better on real life applications. These examples portray a situation that a small business owner might have across defining how the process is documented.
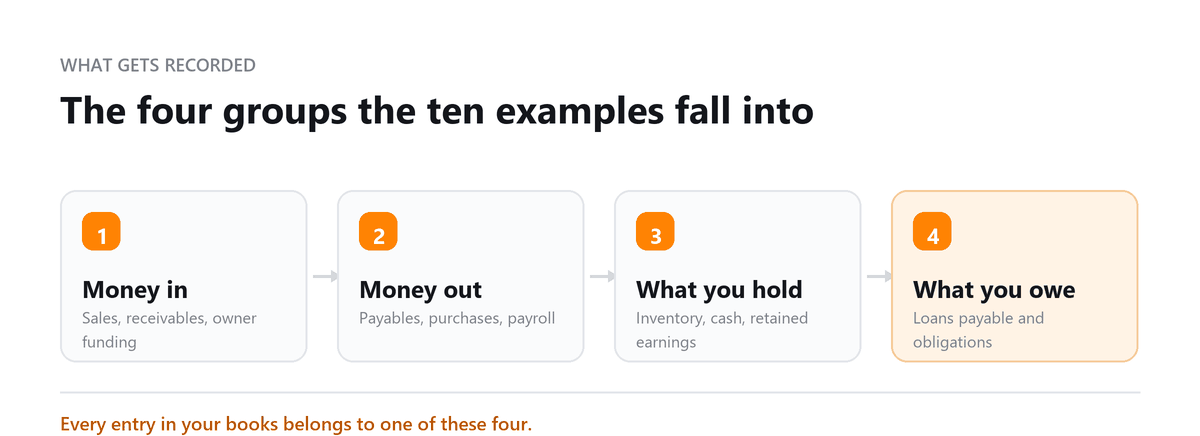
Every bookkeeping example you see in a textbook represents a transaction type your business will face. Once you understand these ten scenarios, the logic behind your financial records clicks into place, and you stop treating your books as a black box.
Ankit Sarawagi, CPA, CA, MBA · LinkedIn1. Accounts Payable
- Definition: Money your business owes to vendors or suppliers for goods or services already received but not yet paid for.
- Example: A retailer receives a $2,000 inventory delivery from a supplier with net-30 payment terms. The invoice is recorded immediately as accounts payable on the balance sheet, it represents a liability until the payment is made at the end of the 30-day period.
2. Accounts Receivable
- Definition: Money owed to your business by customers who have received goods or services but have not yet paid.
- Example: A consulting firm completes a project and sends a $5,000 invoice with a 14-day payment term. The $5,000 is recorded as accounts receivable, an asset, until the client pays and the entry is cleared.
3. Inventory Tracking
- Definition: The value of goods a business holds for sale at any given point in time.
- Example: A product business purchases 100 units at $10 each ($1,000 total). When 60 units are sold, the cost of those 60 units ($600) is moved from inventory (asset) to cost of goods sold (expense). The remaining 40 units ($400) stay on the books as inventory.
4. Sales Records
- Definition: All income generated from the sale of goods or services, recorded to support accurate revenue reporting.
- Example: A bakery sells $800 of product on a Saturday. Each transaction is recorded as a sale, whether cash, card, or invoice, and all sales are summarised to produce the revenue line on the profit and loss statement.
5. Payroll Expenses
- Definition: Wages, salaries, and associated employer costs paid to employees, including tax contributions and benefits.
- Example: A business processes monthly payroll totalling $12,000 in gross wages, $1,500 in employer payroll taxes, and $600 in employer health insurance contributions. All three amounts are recorded as payroll expenses in the month incurred.
6. Purchases and Expenditures
- Definition: Money spent on goods and services required to operate the business, from office supplies to software subscriptions.
- Example: A business buys $150 in office supplies and pays $79/month for an accounting software subscription. Both are recorded as operating expenses, with the correct category applied for reporting and tax purposes.
7. Loans Payable
- Definition: Any borrowed funds that must be repaid, typically over a set term with interest.
- Example: A business takes out a $25,000 equipment loan repayable over 3 years at $800/month. The full $25,000 is initially recorded as a liability (loans payable). Each monthly payment is split: part reduces the principal balance, part is recorded as an interest expense.
8. Retained Earnings
- Definition: The cumulative net income that has been kept in the business rather than distributed to owners as dividends or withdrawals.
- Example: A company earns $80,000 in net profit for the year and distributes $20,000 as owner distributions. The remaining $60,000 is added to retained earnings on the balance sheet, reflecting the reinvested profit available to support future growth.
9. Cash Flow Monitoring
- Definition: The ongoing tracking of actual cash moving in and out of the business, separate from reported profits.
- Example: A business owner records all daily outflows, $120 in petty cash for a supply run, a $450 utility payment, and a $30 bank fee, alongside all inflows. This running record, separate from the P&L, reveals whether the business always has enough cash on hand to meet its obligations.
10. Owner's Equity
- Definition: The owner's financial stake in the business, capital contributed, plus accumulated profits, minus withdrawals.
- Example: A sole trader starts their business by depositing $15,000 of personal funds into the business bank account. That $15,000 is recorded as owner's equity. As the business generates profit and the owner makes further contributions or withdrawals, the equity balance changes accordingly.
Book a free consultation and we will keep every one of them current.
Frequently Asked Questions
What are the basic bookkeeping tasks every small business needs?
The core tasks are: recording all financial transactions, tracking income and expenses accurately, reconciling bank accounts monthly, managing invoices and payments, and preparing regular financial statements. These five tasks form the foundation of sound bookkeeping.
Why is bookkeeping important for small businesses?
Without accurate bookkeeping, you cannot know whether your business is genuinely profitable, whether your cash flow can sustain current operations, or whether you are meeting your tax obligations. Good bookkeeping is the foundation of every sound financial decision.
What is the difference between bookkeeping and accounting?
Bookkeeping is the ongoing recording of financial transactions, the data entry layer. Accounting takes that organised data and uses it for interpretation, financial planning, tax strategy, and formal reporting. Bookkeeping is the input; accounting is the analysis.
Can a small business owner do their own bookkeeping?
Yes, many do, particularly in the early stages using tools like QuickBooks or Xero. The risk increases as the business grows: more transactions, more categories, and more compliance obligations increase the likelihood of errors. Most growing businesses reach a point where outsourcing is more cost-effective than self-managing.
How often should bookkeeping records be updated?
Ideally, transactions should be recorded as they happen or at minimum weekly. Letting records fall behind increases the risk of missed entries, reconciliation errors, and inaccurate reports. Monthly catch-up is a common pattern but creates avoidable risk.
Conclusion
These ten bookkeeping examples cover the transaction types that appear in almost every small business. Understanding each one, what it represents, how it is recorded, and why it matters, gives you a clearer picture of your own financial records and a better foundation for the decisions you make based on them. Good bookkeeping starts with understanding what you are actually tracking.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want These Entries Handled for You?
Book a free consultation and we will keep every one of them current.