
A company purchases $100,000 in equipment and deducts it all in year one on its tax return. However, on its financial statements, the company depreciates the asset over five years.
Taxable income is much less than book income and, as a result, taxes paid is below what the income statement suggests. Nothing is wrong; the company is not losing out on taxes it just has simply deferred payment of taxes to future years and the accounting needs to reflect that reality.
These are called deferred taxes, and they happen because financial statements use Generally Accepted Accounting Principles (GAAP) while tax returns use the Internal Revenue Code, and the two systems often recognize revenues and expenses in different periods.
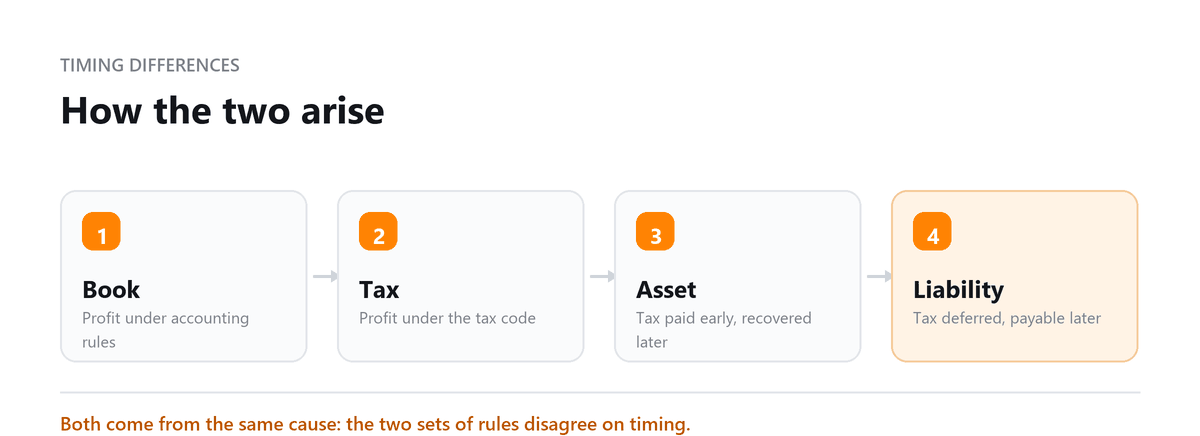
When a company’s financial statements report income or expenses that are different from what is shown on its tax return, it must report either a deferred tax liability or a deferred tax asset.
In practice, these liabilities and assets are theoretical and only mater to the extent that a lender, auditor, potential investor, or buyer reviews the financial statements in detail. When that happens, an analysis of the company’s deferred tax assets and liabilities is critical, because they can offset a company’s losses, deduct a large purchase like equipment, or affect the value of the company’s tax deductions.
This guide explains what deferred tax assets and liabilities are, what creates them, how to calculate and record them, how valuation allowances work, and which businesses actually need to track them.
What Is a Deferred Tax Asset (DTA)?
A deferred tax asset represents future tax savings, it arises when you have paid more tax (or recognised more expense) than your GAAP financial statements require. You will pay less tax in future periods as the timing difference reverses.
Common sources of deferred tax assets:
- Net operating loss (NOL) carryforwards: losses in one year that reduce future taxable income
- Warranty liabilities: expense recognised now for GAAP but not yet deductible for tax
- Bad debt allowances: GAAP estimates losses before they are actually uncollectible
- Deferred revenue: taxed when received but not yet recognised for GAAP
The deferred tax situation growing startups run into most is net operating losses. Founders see years of losses as tax savings waiting to be used, and technically they are a deferred tax asset. But when there's no track record of profit, GAAP usually requires a full valuation allowance, so that asset shows up as zero.
And a big funding round can trigger an ownership change that limits how much of those losses can ever be used. Investors will ask about both, so it's better to know the answers before the data room opens.
Abhinav Gupta, CPA, CA, MBA · LinkedInWhat Is a Deferred Tax Liability (DTL)?
A deferred tax liability represents future tax payments, it arises when taxable income is less than book income now, meaning more tax will be owed in future periods.
Common sources of deferred tax liabilities:
- Accelerated depreciation: Section 179 / bonus depreciation reduces taxable income now; book depreciation is slower
- Installment sales: income deferred for tax purposes but recognised for GAAP
- Prepaid income: taxed when received but deferred for GAAP purposes
How to Calculate Deferred Tax Asset or Liability
Formula: Temporary Difference x Applicable Tax Rate = Deferred Tax Amount
| Example | Temporary Difference | Tax Rate | Deferred Tax |
|---|---|---|---|
| Warranty liability (DTA) | $10,000 | 20% | $2,000 Deferred Tax Asset |
| Accelerated depreciation (DTL) | $15,000 | 25% | $3,750 Deferred Tax Liability |
Key Differences: DTA vs DTL
| Factor | Deferred Tax Asset | Deferred Tax Liability |
|---|---|---|
| Nature | Future tax savings (prepaid tax) | Future tax obligation (tax owed later) |
| Balance sheet | Non-current asset | Non-current liability |
| Arises from | Book expense > Tax deduction now | Tax deduction > Book expense now |
| Examples | NOL carryforwards, warranty reserves | Accelerated depreciation, prepaid income |
| Valuation concern | Must assess 'more likely than not' realisation | Always recognised in full |
Can a Deferred Tax Asset and Liability Exist Simultaneously?
Yes. A company can have both DTAs and DTLs at the same time, from different timing differences. They are typically netted on the balance sheet into a single net DTA or net DTL position.
Deferred Revenue vs Deferred Tax Liability
Deferred revenue is an accounting liability (revenue received but not yet earned for GAAP). A deferred tax liability on that deferred revenue arises because the IRS often taxes cash when received, before GAAP revenue recognition. The two are related but distinct concepts on the balance sheet.
Valuation Allowances on Deferred Tax Assets
A deferred tax asset only has value if the company expects to have enough future taxable income to use it. Under US GAAP, a company must record a valuation allowance to reduce a deferred tax asset if it's more likely than not, meaning a greater than 50 percent chance, that some or all of the asset won't be realized.
Companies weigh positive and negative evidence. A history of recent losses is strong negative evidence and is difficult to overcome, which is why many early-stage and loss-making companies carry a full valuation allowance. Positive evidence can include existing contracts or backlog, deferred tax liabilities that will reverse and create taxable income, and tax planning strategies.
A valuation allowance isn't permanent. Once a company establishes a consistent record of profitability, releasing the allowance can produce a large one-time benefit to earnings, something investors and analysts watch for.
During due diligence, a large valuation allowance is less a red flag than a question. Buyers and investors will want to understand why it exists and what it would take for the company to realize the underlying tax benefits.
Which Businesses Need to Track Deferred Taxes?
Not every business records deferred income taxes.
C corporations that prepare GAAP financial statements generally do, because the corporation itself pays income tax.
S corporations, partnerships, and most LLCs usually don't record federal deferred income taxes, because income and deductions pass through to the owners and are taxed on their personal returns. They may still have entity-level state taxes to consider, including where they've made a pass-through entity tax election.
Cash-basis and tax-basis businesses that don't issue GAAP financial statements typically don't track deferred taxes in their books.
If your business is a C corporation, raising capital, or preparing audited or reviewed financial statements for a lender, deferred taxes are part of getting the numbers right.
Conclusion
Deferred tax assets and liabilities exist because GAAP and tax rules often recognize the same items in different years. A deferred tax liability means tax you've postponed and will pay later. A deferred tax asset means tax you've effectively prepaid or benefits you can use later, but only if the business earns enough to use them. For C corporations and companies seeking investment, financing, or a sale, getting these balances and any valuation allowance right is part of presenting an accurate picture of both earnings and future tax obligations.
Book a free consultation and we will get the accounting right.
Frequently Asked Questions
What is a deferred tax asset in simple terms?
It's a future tax saving. It usually means the business has recognized an expense in its books before it can deduct it for tax, or has losses or credits it can use later. When those differences reverse, the business pays less tax than it otherwise would.
What causes a deferred tax liability?
It usually comes from taking a tax deduction sooner than the expense appears in the books, such as bonus depreciation on equipment, or recognizing income in the books before it's taxed, such as an installment sale. The business pays less tax now and more later.
Is a deferred tax asset good or bad?
It can be valuable, since it represents future tax savings. But it's only worth something if the company will earn enough taxable income to use it. When that's in doubt, a valuation allowance reduces it, which signals uncertainty about future profitability.
Can a funding round affect a startup's deferred tax assets?
Yes. If a startup has a significant ownership change, generally more than a 50 percentage point shift among major shareholders over a three-year period, Section 382 can limit how much of its existing NOLs can be used each year. That can reduce the practical value of those losses and is a common due diligence question.
Do S corporations and LLCs have deferred tax assets or liabilities?
Generally not for federal income taxes, because pass-through entities don't pay federal income tax themselves. The owners report the income and deductions on their own returns. Some may still need to account for entity-level state taxes.

Written by
Abhinav Gupta, CPA, CA, MBA
Abhinav works with business owners across the US on industry-specific bookkeeping, from dental practices and restaurants to construction and e-commerce. He writes about what each trade's books actually need. Connect on LinkedIn
Free consultation
Need Deferred Tax Handled?
Book a free consultation and we will get the accounting right.