
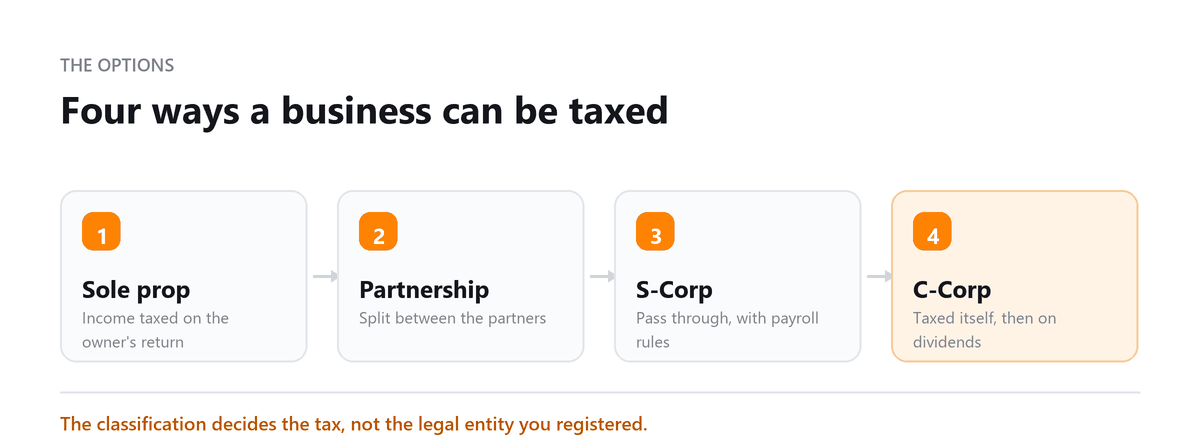
Many business owners assume that forming an LLC or corporation settles how they'll be taxed. It doesn't. The state decides your legal structure. The IRS decides your tax classification, and the two don't always line up. An LLC can be taxed as a sole proprietorship, a partnership, an S corporation, or a C corporation, depending on how many owners it has and what elections it files.
That classification affects nearly everything on the tax side. It determines which return the business files, whether profit is taxed once or twice, how owners get paid, whether self-employment tax applies to all profit or only part of it, and what it costs to stay compliant. Two businesses with identical revenue and expenses can end up with very different tax bills simply because they're classified differently.
The right classification also changes over time. What suits a new freelancer with modest profit may be expensive for the same business a few years later, and what suits a founder raising venture capital rarely suits a family-owned service company. Knowing how each option works makes it much easier to recognize when it's time to revisit the choice.
Expert Perspective
This guide explains the federal tax classifications available to businesses, how LLCs fit in, how to elect or change a classification, and how to decide which one fits your business.
The most common classification mistake I see is timing, in both directions. Some owners elect S corporation status in their first year because they heard it saves tax, then spend more on payroll and a separate return than they save.
Others keep running a very profitable single-member LLC as a disregarded entity for years and pay self-employment tax on every dollar. Over three or four years, either mistake can cost more than most owners realize, and fixing it after the fact is usually harder than making the right call up front.
Anu Gupta, CA, EA, B.Tech · LinkedInLegal Structure vs Tax Classification
It helps to separate two decisions that are often treated as one.
Legal structure is set under state law when you form the business. It determines things like liability protection, ownership rules, and how the business is governed. Common structures include sole proprietorships, general partnerships, LLCs, and corporations.
Tax classification is how the IRS treats the business for federal income tax. It determines which returns are filed and how profit is taxed.
Some legal structures have only one possible tax classification. Others, especially LLCs, can choose.
The Five Federal Tax Classifications
| Classification | Default For | How Income is Taxed |
|---|---|---|
| Sole Proprietorship | Unincorporated single-owner business | Schedule C on personal Form 1040 |
| Partnership | Multi-member LLC, LLP, GP | Form 1065; K-1s to each partner |
| S Corporation | Elected by eligible corps or LLCs | Form 1120-S; K-1s to shareholders |
| C Corporation | Incorporated entities (default) | Form 1120; 21% flat rate |
| Disregarded Entity | Single-member LLC (default) | Same as sole proprietorship |
Sole Proprietorship
A sole proprietorship isn't a separate legal or tax entity. The business and the owner are the same for tax purposes.
The owner reports business income and expenses on Schedule C, attached to Form 1040. Net profit is subject to income tax at the owner's personal rates and to self-employment tax of 15.3 percent on 92.35 percent of net earnings, with the Social Security portion capped at the annual wage base.
It's the simplest classification to run, with no separate business income tax return. It also offers no legal separation between the owner and the business, which is why many owners form an LLC while keeping the same tax treatment.
Disregarded Entity
A single-member LLC is treated as a disregarded entity by default. For federal income tax, the IRS ignores the LLC and taxes its activity directly to its owner. If that owner is an individual, the result is the same as a sole proprietorship: Schedule C on Form 1040 and self-employment tax on net profit.
The owner gets the liability protection of an LLC under state law without a separate federal income tax return.
"Disregarded" doesn't apply to everything, though. A single-member LLC with employees is treated as a separate entity for employment taxes, so it files payroll returns under its own EIN. It's also treated as separate for certain excise taxes.
Partnership
A business with two or more owners that isn't a corporation is taxed as a partnership by default. That includes general partnerships, limited partnerships, limited liability partnerships, and most multi-member LLCs.
The partnership files Form 1065, an information return. It generally pays no federal income tax itself. Instead, it issues a Schedule K-1 to each partner showing their share of income, deductions, and credits, and each partner reports that share on their own return.
Partners are taxed on their share of profit whether or not it's distributed. General partners, and LLC members who actively work in the business, generally owe self-employment tax on their share of business income and on any guaranteed payments for services. Limited partners generally owe it only on guaranteed payments.
Partnerships offer a lot of flexibility. Profits and losses can be allocated among owners in ways that differ from ownership percentages, as long as the allocations follow the tax rules and the partnership agreement.
S Corporation
An S corporation is a corporation, or an LLC taxed as a corporation, that elects to pass its income through to shareholders.
It files Form 1120-S and issues Schedule K-1s. In most cases, it pays no federal income tax at the entity level. Shareholders pay income tax on their share of profit, whether or not it's distributed.
The main tax difference from a sole proprietorship or partnership is how owners who work in the business are paid. They must receive a reasonable salary through payroll, which is subject to Social Security and Medicare taxes. Remaining profit can be distributed without those taxes. For a profitable business, that split can reduce employment taxes meaningfully.
Who Can Elect S Corporation Status
To qualify, a business generally must:
Be a domestic corporation, or an LLC eligible to be taxed as one.
Have no more than 100 shareholders, with family members able to be counted as one.
Have only eligible shareholders, generally individuals who are US citizens or residents, certain trusts, and estates. Partnerships, corporations, and nonresident aliens can't be shareholders.
Have only one class of stock, meaning all shares carry identical rights to distributions and liquidation proceeds. Differences in voting rights are allowed.
Breaking any of these rules can end S corporation status, sometimes without the owners realizing it.
C Corporation
A C corporation is taxed as a separate entity. It files Form 1120 and pays federal income tax on its profit at a flat 21 percent rate.
When the corporation pays dividends, shareholders pay tax on them again, usually at qualified dividend rates of 0, 15, or 20 percent, plus the 3.8 percent net investment income tax for higher earners. That's the double taxation C corporations are known for.
Owners who work in the business are paid wages, which are deductible to the corporation and subject to payroll taxes. Profit left in the business is taxed only once, at 21 percent, until it's distributed. That makes the C corporation attractive for businesses that plan to reinvest most of their earnings, raise money from outside investors, or grow toward an exit.
C corporations also have no limits on the number or type of shareholders and can issue multiple classes of stock, which is why venture-backed startups almost always use them.
How LLCs Are Classified
An LLC is a legal structure under state law, not a tax classification. The IRS assigns it a default classification and allows it to choose a different one.
This flexibility is one of the main reasons LLCs are so popular. An owner can start with simple pass-through taxation and elect S corporation status later, without forming a new entity.
How to Elect or Change a Tax Classification
Form 8832: Entity Classification Election
An LLC that wants to be taxed as a corporation files Form 8832. This form can also be used to move between certain classifications.
Once an eligible entity changes its classification using Form 8832, it generally can't change again for 60 months, except in limited situations.
Form 2553: Electing S Corporation Status
A corporation, or an LLC that qualifies, files Form 2553 to elect S corporation status. An LLC filing Form 2553 is generally treated as having also elected to be taxed as a corporation, so it usually doesn't need to file Form 8832 separately.
For the election to take effect in a given tax year, Form 2553 generally must be filed within two months and 15 days after the start of that year, or at any time during the prior tax year. For a calendar-year business, that usually means by March 15. Every shareholder must sign.
If the deadline is missed, the IRS offers a simplified process to request late election relief in many cases, provided there was reasonable cause and the business has acted consistently with S corporation treatment.
Revoking or Losing S Corporation Status
S corporation status can be revoked with the consent of shareholders holding more than half of the shares, or it can terminate if the business stops meeting the eligibility rules. After a revocation or termination, a business generally must wait five years before electing S status again, unless the IRS consents to an earlier election.
When an S Corporation Election Makes Sense
For many profitable owner-operated businesses, the S corporation election is the most valuable classification change available. But it isn't automatically the right choice.
The election starts to make financial sense once net profit consistently reaches the low six figures. At that level, the payroll tax saved on distributions usually outweighs the added costs of running payroll, filing a separate return, keeping more detailed books, and paying any state fees or entity-level taxes.
Several other factors belong in the decision:
Reasonable salary. The salary has to reflect what the business would pay someone else to do your job. The higher that salary is relative to profit, the smaller the saving.
The qualified business income deduction. Salary paid to yourself isn't qualified business income, so the deduction may shrink after the election.
State taxes. Some states and cities tax S corporations differently or don't fully recognize the election. On the other hand, many states allow S corporations to make a pass-through entity tax election, which can create additional federal savings for owners in higher-tax states.
Future plans. If you expect to raise outside investment, bring in foreign owners, or offer different share classes, S corporation rules may get in the way.
When a C Corporation Makes Sense
A C corporation is usually the better fit for businesses that:
Plan to raise venture capital or bring in institutional investors, who generally require C corporation stock.
Intend to reinvest most profits rather than distribute them to owners.
Want to offer equity compensation across multiple share classes.
May qualify for the qualified small business stock exclusion, which can exclude some or all of the gain on a later sale of qualifying stock.
For owner-operated businesses that pay out most of their profit, the double tax on dividends often makes a C corporation more expensive than a pass-through classification.
Conclusion
Your federal tax classification is separate from your legal structure, and it has a larger effect on your tax bill than most owners expect. Sole proprietorships and single-member LLCs keep things simple but put all profit under self-employment tax.
Partnerships add flexibility for multiple owners. S corporations can reduce employment taxes once profit is high enough, as long as the eligibility rules and reasonable salary requirement are met.
C corporations suit businesses that reinvest heavily or plan to raise outside capital. Revisit your classification as your profit, ownership, and goals change, and model the numbers before making or changing an election.
Book a free consultation and we will check it against your numbers.
Frequently Asked Questions
What is the default federal tax classification for a single-member LLC?
A single-member LLC is treated as a disregarded entity by default. If it's owned by an individual, its income and expenses are reported on Schedule C with the owner's Form 1040, just like a sole proprietorship. It can elect to be taxed as an S corporation or C corporation instead.
What is the C corporation tax rate?
C corporations pay a flat 21 percent federal income tax on taxable income. Dividends paid to shareholders are then taxed again on their personal returns. State corporate income taxes may also apply.
When should I consider an S corporation election?
Generally once your net business profit consistently reaches the low six figures. At that point, the payroll tax savings on distributions usually outweigh the cost of payroll, a separate tax return, and added compliance. Have a CPA model your reasonable salary, state taxes, and effect on the qualified business income deduction before you elect.
Can I change my business's tax classification later?
Yes, in most cases. An LLC can elect corporate or S corporation treatment after it's formed, and an eligible corporation can elect S status. There are timing limits, such as the 60-month restriction after a Form 8832 change and a five-year wait after S status ends, and some changes can trigger tax, so plan them carefully.
Does my tax classification affect my liability protection?
No. Liability protection comes from your legal structure under state law, such as forming an LLC or corporation. Electing S corporation or C corporation tax treatment for an LLC doesn't change the legal protection the LLC provides.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Picked the Right Classification?
Book a free consultation and we will check it against your numbers.