
Ask ten people what a tax exemption is and you'll get ten different answers. Some think of the old per-person exemption that used to appear on every return. Others mean the "exempt" box on their W-4, the tax-exempt status of a nonprofit, or the fact that life insurance payouts aren't taxed. All of these get called exemptions, but they work in completely different ways.
The confusion got worse after 2017. The Tax Cuts and Jobs Act reduced personal and dependent exemptions to zero starting in 2018, and for years that change was scheduled to expire after 2025. Legislation passed in 2025 settled the question by making the elimination permanent. So anyone still expecting a per-person exemption on their return won't be getting one.
That doesn't mean exemptions have disappeared. A long list of income is still excluded from federal tax, the gift tax and alternative minimum tax still have exemption amounts, and some people can legitimately stop federal income tax withholding from their paychecks. Knowing which of these apply to you is often worth more than chasing another deduction.
Expert Perspective
This guide explains how federal tax exemptions work, what happened to personal and dependent exemptions, the exemptions and exclusions still available in 2026, how withholding exemptions work, and how exemptions differ from deductions and credits.
How Do Federal Tax Exemptions Work?
An exemption reduces the amount of income subject to federal tax. Unlike a deduction (which reduces taxable income by an amount), some exemptions fully exclude specific income types from taxation.
The most underused exclusion I see is the one on employer benefits. People compare job offers or plan their year looking only at salary, and they ignore how much tax-free value sits in health premiums, HSA contributions made through payroll, dependent care benefits, and tuition assistance. A few thousand dollars of excluded benefits can be worth more than a raise, because none of it is taxed and some of it avoids payroll tax as well.
Anu Gupta, CA, EA, B.Tech · LinkedInExemptions, Exclusions, Deductions, and Credits
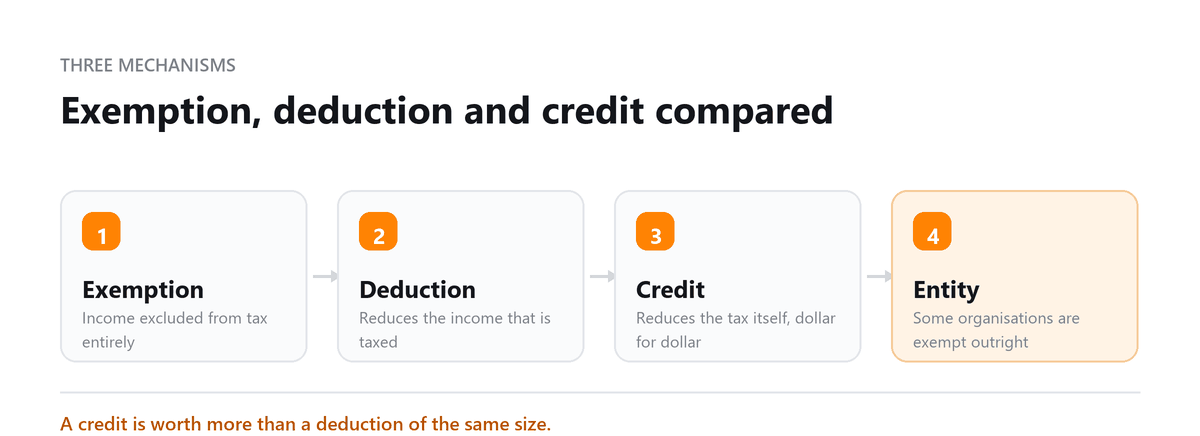
These terms are often used interchangeably, but each one reduces your tax in a different way.
| Term | What It Does | Example |
|---|---|---|
| Exclusion | Keeps certain income out of your gross income entirely | Life insurance proceeds, municipal bond interest |
| Exemption | Historically, a fixed amount subtracted for each person on the return; now mostly used for thresholds and special status | AMT exemption, gift tax annual exclusion, tax-exempt organizations |
| Deduction | Reduces taxable income after income is counted | Standard deduction, mortgage interest, business expenses |
| Credit | Reduces your tax bill dollar for dollar | Child Tax Credit, education credits |
In everyday conversation, "exempt income" usually means excluded income, which never shows up in your taxable income at all.
Personal Exemptions: Eliminated
Before 2018, taxpayers could subtract a personal exemption for themselves, their spouse, and each dependent. In 2017, that was $4,050 per person.
The Tax Cuts and Jobs Act reduced the personal exemption to zero from 2018 through 2025. To partly offset that, the standard deduction was roughly doubled.
The 2025 legislation made the elimination permanent. There's no personal exemption for 2026 or future years. The larger standard deduction, which is $16,100 for single filers and $32,200 for married couples filing jointly in 2026, now does most of the work the personal exemption used to do.
Dependent Exemptions: Replaced by Credits
The exemption for dependents was eliminated along with the personal exemption. Instead, families now rely mainly on tax credits.
The Child Tax Credit. The credit was raised to $2,200 per qualifying child under age 17 starting in 2025, with inflation adjustments after that. Part of it is refundable for families with earned income, meaning it can produce a refund even when no tax is owed.
The Credit for Other Dependents. A nonrefundable $500 credit for dependents who don't qualify for the Child Tax Credit, such as older children or elderly parents you support.
Because credits reduce tax dollar for dollar, many families with children receive more benefit from these credits than they did from the old exemptions. Families in higher brackets with several dependents sometimes receive less.
Dependents still matter even without an exemption. Claiming someone as a dependent can affect your filing status, eligibility for credits, and other tax benefits.
Exemption From Federal Income Tax Withholding
This one is still very much available, though it's often misunderstood.
You can claim exemption from federal income tax withholding on Form W-4 if both of these are true:
You had no federal income tax liability last year, meaning you owed nothing and received a full refund of any tax withheld.
You expect no federal income tax liability this year.
To claim it, write "Exempt" on the Form W-4 in the space provided under Step 4(c), complete Steps 1 and 5, and give it to your employer. Leave the other steps blank.
Keep three rules in mind:
It only lasts one year. You must submit a new Form W-4 claiming exempt status by mid-February of the following year, or your employer will begin withholding again.
It doesn't cover FICA. Social Security and Medicare taxes are still withheld from your wages.
It's easy to misuse. Claiming exempt when you'll actually owe tax can leave you with a large bill, possible underpayment penalties, and in some cases a penalty for a false W-4.
Students with part-time jobs and people with very low annual income are the most common legitimate users.
Income Excluded From Federal Tax in 2026
Many kinds of income are excluded from federal income tax entirely. These are some of the most common.
| Exclusion | What It Covers |
|---|---|
| Gifts and inheritances | Money or property you receive as a gift or inheritance isn't income to you, though income it later earns is taxable |
| Life insurance death benefits | Proceeds paid to a beneficiary because of the insured person's death are generally excluded |
| Municipal bond interest | Interest on most bonds issued by state and local governments is excluded from federal income tax |
| Employer-provided health coverage | Premiums your employer pays for health insurance aren't included in your wages |
| Other employer benefits | Qualifying HSA contributions through payroll, dependent care assistance, and certain educational assistance, each within annual limits |
| Gain on sale of a primary home | Up to $250,000 of gain, or $500,000 for married couples filing jointly, if you owned and lived in the home for at least two of the five years before the sale |
| Qualified scholarships | Amounts used for tuition, fees, and required books, supplies, and equipment by degree candidates, but not room and board |
| Certain veterans' benefits | Disability compensation and many other VA benefits |
| Workers' compensation | Benefits for work-related injuries or illness |
| Child support | Payments received for the support of a child |
| Roth IRA qualified distributions | Withdrawals meeting the age and five-year holding requirements |
Excluded doesn't always mean ignored. Some excluded income still needs to be reported, such as municipal bond interest, which is shown on your return and can affect how much of your Social Security benefits are taxable.
Exemptions That Work as Thresholds
A few exemptions today act as thresholds below which a tax doesn't apply.
The Gift Tax Annual Exclusion
You can give up to $19,000 per recipient in 2026 without filing a gift tax return. Married couples can combine their exclusions to give $38,000 per recipient. Gifts above that amount require a gift tax return, but tax is only owed once you've used up your lifetime exemption.
The Estate and Gift Tax Lifetime Exemption
Legislation passed in 2025 set the combined lifetime estate and gift tax exemption at $15 million per person for 2026, adjusted for inflation in later years. Married couples can effectively shield double that amount. Most families will never owe federal estate or gift tax.
The Alternative Minimum Tax Exemption
The AMT is a parallel tax system meant to make sure higher-income taxpayers with large deductions or certain tax preferences pay a minimum amount. The AMT exemption keeps most taxpayers from ever owing it.
For 2026, the exemption is $90,100 for single filers and $140,200 for married couples filing jointly. The exemption begins phasing out at $500,000 of income for single filers and $1 million for joint filers, and under the 2025 legislation it now phases out faster than before. That means a few more high earners, particularly those exercising incentive stock options, may find themselves subject to AMT.
New Deductions That Are Often Called Exemptions
The 2025 legislation created several temporary tax breaks for 2025 through 2028 that are frequently described as "no tax" on certain income. Technically, they aren't exemptions or exclusions. They're deductions with dollar limits and income phase-outs.
Qualified tips. A deduction for qualifying tip income in occupations that customarily receive tips.
Qualified overtime. A deduction for the premium portion of qualifying overtime pay.
Car loan interest. A deduction for interest on loans for qualifying new vehicles assembled in the US.
Taxpayers 65 and older. An additional deduction on top of the existing extra standard deduction for seniors.
Because these are deductions, the income is still counted and still subject to FICA taxes. The deduction simply reduces how much of it is subject to federal income tax.
Tax-Exempt Status for Organizations
"Federal tax exemption" also refers to organizations that don't pay federal income tax. Charities, religious organizations, educational institutions, and many other nonprofits can qualify under section 501(c) of the Internal Revenue Code.
Most organizations must apply to the IRS to be recognized as tax-exempt. Once approved, they generally don't pay federal income tax on income related to their mission, although they can owe tax on unrelated business income. Most still have to file an annual information return in the Form 990 series, and failing to file for three consecutive years results in automatic revocation of tax-exempt status.
Conclusion
Personal and dependent exemptions are gone for good, replaced by a larger standard deduction and family tax credits. But federal tax exemptions in the broader sense are still very much part of tax planning. Excluded income like employer benefits, home sale gains, and municipal bond interest never reaches your taxable income. Exemption amounts keep most people clear of gift, estate, and alternative minimum tax. And the W-4 withholding exemption helps people with no tax liability keep more of each paycheck.
Knowing which of these apply to you is one of the simplest ways to make sure you're not paying tax you don't owe.
Book a free consultation and we will check what you are missing.
Frequently Asked Questions
Are personal exemptions available in 2026?
No. Personal and dependent exemptions were reduced to zero starting in 2018, and legislation passed in 2025 made that permanent. The larger standard deduction and the Child Tax Credit now provide most of the benefit the exemptions used to.
What's the difference between a tax exemption and a tax deduction?
Today, most "exempt" income is technically excluded, meaning it never counts as income in the first place. A deduction works differently: the income is counted, and the deduction then reduces your taxable income. A credit reduces your actual tax bill after it's calculated.
Can I claim exempt from federal withholding?
Yes, if you owed no federal income tax last year and expect to owe none this year. Write "Exempt" on Form W-4 and renew it by mid-February each year. Social Security and Medicare taxes will still be withheld.
What happens if I claim exempt on my W-4 but end up owing tax?
You'll owe the full amount when you file, and you may also face an underpayment penalty for not paying enough during the year. If you knowingly claim exempt without qualifying, the IRS can also impose a penalty for a false W-4. Update your W-4 as soon as your situation changes.
Is Social Security income exempt from federal tax?
Not always. Up to 85 percent of Social Security benefits can be taxable, depending on your combined income. Many retirees with little income beyond their benefits owe no federal tax on them, while those with other significant income often do. The additional deduction for taxpayers 65 and older can reduce the tax for many retirees through 2028.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Claiming Everything You Can?
Book a free consultation and we will check what you are missing.