
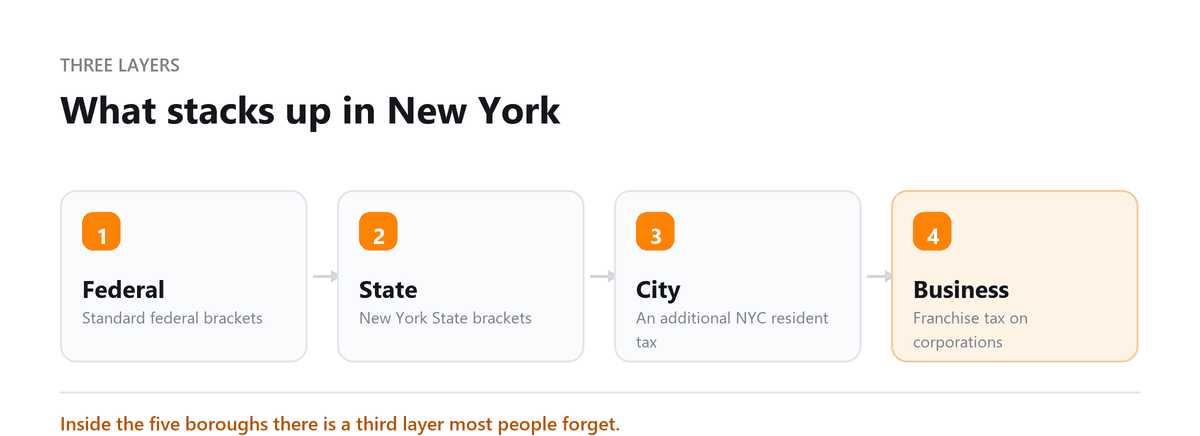
When you‘re balancing progressive IRS Rates with Some Of The Highest State And Local Tax Brackets In The Nation, Federal income tax rates peaked at 37%. The additional New York state income tax was 10.9%, while the city’s local income tax reached 3.876% if you happened to be a resident of the five boroughs.
Since taxes had to be calculated based on all three, it was important to have a thorough knowledge of how they all interacted with one another in order to decrease the amount one would have to pay.
That is why it was always helpful to know how federal, state, and local taxes worked individually but together when it came to dealing with the New York tax system as one dealt with the IRS.
Having an understanding of how the three types of taxation worked could help high earners and business owners keep more of their hard-earned cash from being eaten up by taxes in New York, letting them utilize many strategies to reduce their tax bill by taking advantage of deductions and credits offered by the city, state, and federal government!
Federal Income Tax in New York (2025 Tax Year)
| Rate | Taxable Income, Single Filer (TY2025) |
|---|---|
| 10% | $0 to $11,925 |
| 12% | $11,925 to $48,475 |
| 22% | $48,475 to $103,350 |
| 24% | $103,350 to $197,300 |
| 32% | $197,300 to $250,525 |
| 35% | $250,525 to $626,350 |
| 37% | Over $626,350 |
New York State Income Tax
New York State imposes a graduated income tax on top of federal obligations. NY has one of the highest top state rates in the US:
| NY Income Tax Rate | Taxable Income (Single, TY2025) |
|---|---|
| 4% | $0 to $17,150 |
| 4.5% | $17,150 to $23,600 |
| 5.25% | $23,600 to $27,900 |
| 5.85% | $27,900 to $161,550 |
| 6.25% | $161,550 to $323,200 |
| 6.85% | $323,200 to $2,155,350 |
| 9.65% | $2,155,350 to $5,000,000 |
| 10.3% | $5,000,000 to $25,000,000 |
| 10.9% | Over $25,000,000 |
New York City Income Tax
New York City residents (not commuters) pay an additional NYC income tax:
| NYC Rate | Income Range (Single) |
|---|---|
| 3.078% | $0 to $12,000 |
| 3.762% | $12,000 to $25,000 |
| 3.819% | $25,000 to $50,000 |
| 3.876% | Over $50,000 |
NYC commuters who live outside NYC but work in the city do not pay NYC income tax, but may owe a Metropolitan Commuter Transportation Mobility Tax (MCTMT) on wages over $75,000.
When dealing with tri-layer taxation in NYC, high earners shouldn't just look at rate percentages, they need to focus on entity structural choices (like S-Corp electability or Pass-Through Entity Tax) and strict physical presence tracking to prevent dual-residency claims.
Ankit Sarawagi, CPA, CA, MBA · LinkedInCombined Tax Burden in New York City
New York City residents pay income tax at three levels: federal, New York State, and New York City. Few places in the US stack that many income taxes on the same dollar, which is why the combined bill for a high earner in NYC can be far higher than the federal figure alone suggests.
Example: Single NYC Resident, $200,000 of Taxable Income, 2025
This example assumes $200,000 of taxable income for federal, New York State, and New York City purposes, no credits, and no other income adjustments. Real returns will differ, because New York's standard deduction and some adjustments aren't the same as the federal ones.
| Tax | Approximate Tax | Effective Rate on $200,000 | Top Marginal Rate Reached |
|---|---|---|---|
| Federal income tax | $41,060 | 20.50% | 32% |
| New York State income tax | $12,000 | 6.00% | 6% |
| New York City income tax | $7,630 | 3.80% | 3.88% |
| Combined | $60,690 | 30.30% | 41.90% |
Three points make these numbers easier to read.
The effective rate and the marginal rate tell different stories. Across all $200,000, this person pays about 30 percent. But their next dollar of income is taxed at roughly 42 percent combined, which is the number that matters when weighing a raise, a bonus, or a retirement contribution.
New York taxes higher earners on more than just the top slice. Above certain income levels, New York recaptures the benefit of its lower brackets, so tax is calculated as if more of your income were taxed at your top state rate. That's why the state tax in this example comes out close to a flat 6 percent.
Payroll taxes aren't included. Social Security and Medicare withholding on wages, or self-employment tax for business owners, comes on top of these figures.
How to Reduce Your Federal, New York State, and NYC Tax
Contribute More to Pre-Tax Retirement Accounts
Traditional 401(k), 403(b), and 457 contributions reduce taxable income for federal, New York State, and New York City purposes. At a combined marginal rate above 40 percent, each $1,000 contributed can save more than $400 in income tax.
Use an HSA If You're Eligible
New York follows the federal treatment of health savings accounts, so contributions reduce income for both state and city tax, not just federal. That isn't true in every high-tax state.
Revisit Itemizing Under the Higher SALT Cap
For 2025, the federal deduction for state and local taxes is capped at $40,000 for most filers, reduced for incomes above $500,000. A New Yorker at this income level may pay close to $20,000 in state and city income tax alone, before property taxes, so itemizing can make sense for more people than it did under the old $10,000 cap.
Contribute to New York's 529 Plan
New York allows a state income tax deduction for contributions to its 529 college savings plan, up to $5,000 a year for single filers and $10,000 for married couples filing jointly.
Claim New York and NYC Credits
Depending on your household, you may qualify for the Empire State Child Credit, the New York college tuition credit or itemized deduction, and the NYC school tax credit, which is available to residents below an income limit.
Use the Pass-Through Entity Tax for Business Income
Owners of partnerships and S corporations can elect New York's pass-through entity tax, and the separate New York City version, so state and city income tax is paid at the entity level. That tax is generally deductible on the federal return without counting toward the individual SALT cap.
Plan the Timing of Capital Gains
New York and NYC tax capital gains as ordinary income, with no lower rate. Timing large sales for years with lower income, harvesting losses, and spreading gains over several years can reduce the combined bill.
Be Careful With Residency Changes
Moving to a lower-tax state can make sense at higher incomes, but New York audits residency changes closely. You can be taxed as a statutory resident if you keep a permanent place of abode in New York and spend more than 183 days in the state. Remote workers who move away but keep working for a New York employer can also remain taxable under the convenience of the employer rule. Keep day counts and records documenting the move.
Additional Taxes for NYC Businesses
Two points often catch business owners off guard. An S corporation that pays no entity-level income tax federally still owes NYC General Corporation Tax. And a sole proprietor or freelancer working in NYC can owe Unincorporated Business Tax on top of personal income tax and self-employment tax.
| Tax | Who It Applies To | Key Points |
|---|---|---|
| Business Corporation Tax | C corporations doing business in NYC | Taxed on business income allocated to the city |
| General Corporation Tax | S corporations doing business in NYC | NYC doesn't recognize the federal S election, so S corporations pay city corporate tax |
| Unincorporated Business Tax | Sole proprietors, partnerships, and LLCs taxed as partnerships or disregarded entities doing business in NYC | 4% on net business income allocated to the city, with an exemption and credit that reduce or eliminate it for smaller businesses |
| Sales tax | Sellers of taxable goods and services in NYC | 8.875% combined: 4% state, 4.5% city, and 0.375% Metropolitan Commuter Transportation District surcharge |
| Metropolitan Commuter Transportation Mobility Tax | Employers with payroll, and self-employed individuals with net earnings, above thresholds in the commuter district | Rates depend on location and payroll size, with higher rates in NYC |
| Commercial Rent Tax | Tenants paying high annual rent for commercial space in Manhattan south of 96th Street | Applies only above an annual rent threshold |
Conclusion
New York especially New York City carries one of the highest combined tax burdens in the US. Coordinated federal, NY state, and NYC tax planning is essential for high-income residents and business owners.
Take one of our NYC tech consultants who shifted over to Profitjets in order to shed $280,000 in net self-employment income. By switching their structure from a default LLC to an S-Corporation and electing into the NYS Pass-Through Entity Tax (PTET), we eliminated over $14,000 in unwilled tax drag in year one while simultaneously shrinking their overall effective tax rate and remaining in good standing with the city, state, and federal governments.
Book a free consultation and we will cover all three layers.
FAQs
What is the New York State income tax rate?
New York uses graduated income tax rates ranging from 4% to 10.9%. New York City residents may also pay a separate city income tax. Your actual state tax depends on taxable income, filing status, and applicable deductions and credits.
Do New York City residents pay both state and city income tax?
Yes. New York City residents generally pay New York State income tax plus NYC personal income tax. The city tax rates vary based on taxable income and filing status. For 2025, NYC personal income tax rates range from 3.078% to 3.876%.
Do commuters who work in New York City pay NYC income tax?
Generally, no. People who work in New York City but are not NYC residents are not subject to NYC personal income tax, although they may still owe New York State income tax on New York-source income. Nonresidents may need to file a New York State return when their New York-source income meets the applicable filing requirements.
Do I have to file both federal and New York State tax returns?
You may need to file both if you meet the applicable federal and New York State filing requirements. New York residents and certain nonresidents with New York-source income may have to file a state return. New York nonresidents generally use Form IT-203 to report income subject to New York State tax.
When is the New York income tax return due?
For tax year 2025, New York individual income tax returns are due April 15, 2026. Eligible taxpayers can generally request an automatic six-month extension to October 15, 2026. An extension gives additional time to file, but any tax owed generally still must be paid by the original April 15 deadline.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Related articles
Free consultation
Based in New York?
Book a free consultation and we will cover all three layers.