
This is the partnership's balance sheet as reported on the return, and it is the part of the filing that most often gives away a problem elsewhere.
The figures have to agree with the accounts and with the capital accounts reported for each partner. Where they do not, the cause is usually mundane, but an unexplained difference is one of the clearest signals to a reader that something in the return has not been reconciled.
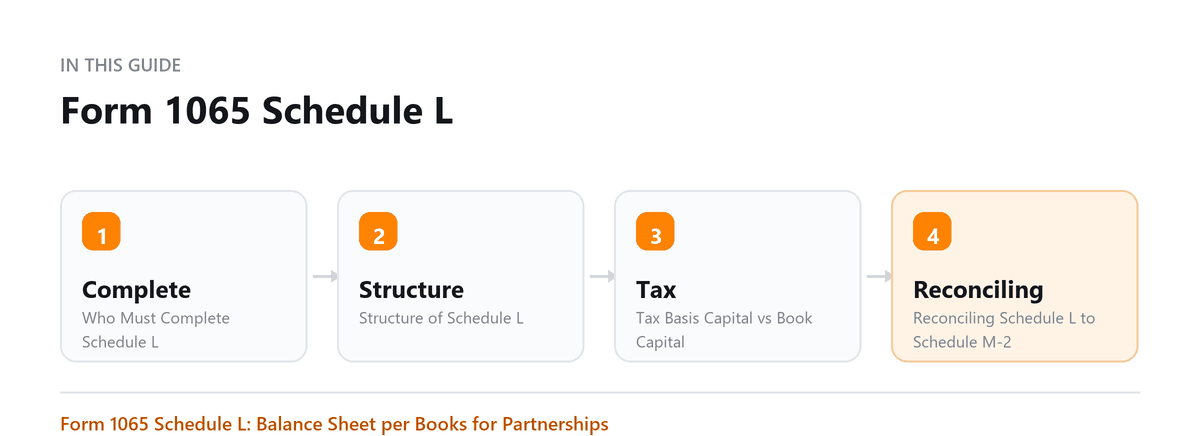
This covers who has to complete it, how it is structured, the difference between the bases capital can be reported on, and how it ties back to the other schedules.
Schedule L is the balance sheet component of Form 1065, the U.S. Return of Partnership Income. It reports the partnership's assets, liabilities, and partners' capital as recorded in the partnership's books at the beginning and end of the tax year. Schedule L is one of the most scrutinized parts of a partnership return because it links to Schedule M-2 (analysis of partners' capital) and must reconcile with the partnership's accounting records.
Who Must Complete Schedule L
Schedule L is required unless ALL three of the following apply:
- The partnership's total receipts for the tax year were less than $250,000
- The partnership's total assets at the end of the tax year were less than $1 million
- Schedule K-1s were furnished to all partners on time
If any of these thresholds are exceeded, Schedule L must be completed. Most operating partnerships of any meaningful size will be required to file Schedule L.
A balance sheet that does not agree with the accounts is the clearest signal that something else in the return is wrong. Find the difference before filing rather than explaining it afterwards. It is almost always mundane: an adjustment made after the return was started, or opening figures that do not match last year's close.
Ankit Sarawagi, CPA, CA, MBA · LinkedInStructure of Schedule L
Assets Section
| Line | What to Report |
|---|---|
| 1, Cash | Bank account balances, petty cash, money market funds |
| 2a, Trade notes and accounts receivable | Amounts owed to the partnership for goods/services delivered |
| 2b, Less allowance for bad debts | Reserve for uncollectible accounts (enter as negative) |
| 3, Inventories | Book value of unsold goods (lower of cost or market) |
| 4, U.S. government obligations | Treasury bills, bonds held as investments |
| 5, Tax-exempt securities | Municipal bonds and other tax-exempt instruments |
| 6, Other current assets | Prepaid expenses, deposits, other short-term assets |
| 7, Loans to partners (current) | Short-term amounts owed by partners |
| 8, Mortgage and real estate loans | Long-term receivables from real estate financing |
| 9, Other investments | Securities, equity investments, non-current receivables |
| 10a, Buildings and other depreciable assets | Gross cost of depreciable property |
| 10b, Less accumulated depreciation | Total depreciation taken to date |
| 11a, Depletable assets | Oil/gas, timber, mineral rights at gross cost |
| 11b, Less accumulated depletion | Total depletion taken |
| 12, Land | Cost of land (not depreciable) |
| 13a, Intangible assets | Goodwill, patents, trademarks, customer lists at gross cost |
| 13b, Less accumulated amortization | Total amortization taken |
| 14, Other assets | Any assets not classified above; attach a statement |
| 15, Total assets | Sum of all asset lines |
Liabilities and Partners' Capital Section
| Line | What to Report |
|---|---|
| 16, Accounts payable | Amounts owed to vendors for goods/services received |
| 17, Mortgages, notes, bonds payable in less than 1 year | Current portion of long-term debt, short-term notes |
| 18, Other current liabilities | Accrued expenses, deferred revenue, taxes payable |
| 19, All nonrecourse loans | Debt for which no partner is personally liable |
| 20, Loans from partners | Amounts the partnership owes to partners |
| 21, Mortgages, notes, bonds payable in 1 year or more | Long-term debt |
| 22, Other liabilities | Deferred rent, long-term accruals; attach statement |
| 23, Partners' capital accounts | Total capital per books; must reconcile with Schedule M-2 |
| 24, Total liabilities and capital | Must equal Line 15, Total assets |
Tax Basis Capital vs Book Capital
Starting with 2020 returns, the IRS requires partnerships to report partners' capital accounts on a tax basis (not GAAP/book basis) on both Schedule L and Schedule K-1. This was a major change and caused significant compliance burdens for partnerships that had historically tracked capital on a book basis.
- Tax basis capital = sum of contributions + share of income - share of losses - distributions (all measured using tax, not book, amounts)
- Negative tax basis capital is permissible and must be disclosed
- Section 704(b) capital (FMV at contribution) is different from tax basis capital
Reconciling Schedule L to Schedule M-2
The ending Partners' Capital (Line 23, Column (d)) on Schedule L must equal the total ending capital on Schedule M-2. If they do not match, the IRS will flag the return. Common reconciling items:
- Book income that differs from taxable income (timing differences)
- Section 704(c) built-in gain/loss allocations
- Guaranteed payment reclassifications
- Basis adjustments under Section 754
Pro Tip: Build a simple reconciliation schedule, book income to taxable income, then book capital to tax basis capital, and keep it with the partnership's workpapers. This reconciliation is auditor gold.
Book a free consultation and we will take the return off your desk.
Frequently Asked Questions
What if the partnership's books are on a cash basis?
Schedule L should still be completed based on the books. For a pure cash-basis partnership, this means no receivables or payables, only cash and other tangible assets.
Can a partner have a negative capital account?
Yes. Under tax basis capital reporting, negative capital accounts are common in partnerships with large debt allocations or cumulative loss allocations. They must be reported as-is.
What if total assets at the start and end of year don't match prior year's ending balance?
Common causes: restatements, different accounting method, or errors in prior years. Attach a statement explaining any opening balance adjustments.
Is Schedule L required for a new partnership in its first year?
Yes, if the filing thresholds are exceeded. The beginning of year columns will all be zero.
How does a 754 step-up appear on Schedule L?
The step-up creates a new asset or increases the basis of existing assets. It appears on the applicable asset line (e.g., increased building basis) with a corresponding adjustment to capital accounts or a new intangible asset.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Filing Handled?
Book a free consultation and we will take the return off your desk.