
Franchise tax requirements can catch small business owners off guard because they apply regardless of whether your business earned a profit. Unlike income tax, state franchise tax is a recurring fee for the privilege of operating, forming, or registering a legal entity within a state. If you manage an LLC, S-Corp, or C-Corp, keeping up with state franchise tax requirements is essential to maintaining your business's legal good standing.
Leaving these obligations unchecked leads to steep late penalties, interest charges, and potential administrative forfeiture. Below, we break down key rules, thresholds, and multi-state strategies.
Franchise tax is a state-level fee or tax imposed on businesses for the privilege of operating within a state. Unlike income tax (which is based on profit), franchise tax may apply even if your business has no profit and the rules differ significantly by state.
The single biggest franchise tax mistake expanding businesses make is assuming that having no physical office in a state means they don't owe franchise tax, completely ignoring how economic nexus and remote employees trigger filing requirements.
Anu Gupta, CA, EA, B.Tech · LinkedInUnderstanding Franchise Tax
Franchise tax is not a tax on royalties or licensing. It is a tax, or annual registration fee, charged by states to allow a business entity (corporation, LLC, LP) to exist and do business in that state. It is separate from and in addition to any state or federal income tax.
· Who pays: corporations, LLCs, partnerships, depending on the state
· Basis: varies by state, can be net worth, paid-in capital, revenue, or a flat fee
· States without franchise tax: Nevada, Wyoming, Montana, Ohio (eliminated 2024), and a few others
State-Specific Franchise Tax Updates for 2026
Texas Franchise Tax
Texas imposes a franchise tax (also called the 'margin tax') on most businesses with Texas nexus:
| Category | 2026 Details |
|---|---|
| No-tax-due threshold | $2.65M annualised revenue (indexed annually) |
| EZ Computation (revenue method) | Available for businesses with revenue at or below $20M |
| Tax rate, most businesses | 0.75% of taxable margin |
| Tax rate, retail and wholesale | 0.375% of taxable margin |
| Filing deadline | May 15 each year |
California Franchise Tax
California imposes an $800 annual minimum franchise tax on virtually all LLCs and corporations:
| Entity | Minimum Franchise Tax |
|---|---|
| LLC (all sizes) | $800/year (plus additional LLC fee if income > $250K) |
| S-Corporation | $800/year minimum (plus 1.5% of net income) |
| C-Corporation | $800/year minimum (plus 8.84% CA corporate income tax) |
· CA franchise tax due date: 15th day of the 4th month of the tax year (April 15 for calendar-year entities)
· First-year exemption: LLCs formed on or after January 1, 2021 are exempt from the $800 tax in their first taxable year
New York Franchise Tax / MFI
New York imposes a Metropolitan Franchise Interest (MFI) payment and quarterly estimated tax requirements on corporations with significant tax liability:
· MFI threshold: applies to corporations whose prior year tax liability exceeded $1,000
· MFI amount: 25% of prior year tax liability, paid in March
· Annual report and franchise tax: NY corporations and LLCs must file an annual report with the NY Department of State and pay franchise tax based on business income or assets
Key Considerations for Small Businesses
· Register in every state where you have nexus, economic nexus thresholds vary but many states use $100,000 revenue or 200 transactions
· Franchise tax is typically not deductible against the same state's income tax, but is deductible as a federal business expense (Schedule C or corporate return)
· Franchise tax obligations continue even during unprofitable years, budgeting for minimum fees is essential
· Multi-state businesses should conduct annual nexus reviews as activities expand
Expanding across state lines without a centralized compliance strategy often leaves growing companies exposed to unfiled returns, compound interest, and license forfeitures.
At Profitjets, our multi-state tax specialists handle full-spectrum nexus reviews, entity registrations, and franchise filings across all 50 states.
Profitjets has managed over 1,200 multi-state franchise tax compliance reviews, identifying an average of $24,500 in unrecorded tax penalties and back-tax exposure for expanding businesses before state audits occur.
Conclusion
Franchise tax applies even when a business is unprofitable. Texas, California, and New York each have distinct structures from Texas's margin tax to California's flat $800 minimum. Multi-state businesses need annual nexus reviews to avoid compliance gaps.
A scaling e-commerce client reached out to Profitjets after expanding remote hiring across four new states. They hadn't realized that hiring remote workers created physical nexus, triggering multi-year back franchise taxes and late filing penalties in California and New York.
We led our team through a Voluntary Disclosure Agreement (VDA) process with both state revenue departments waiving over $18,000 in failure-to-file penalties, settling the core back taxes, and getting their multi-state corporate standing fully restored.
Franchise Tax Falls Due on a Business With No Revenue
Franchise tax is charged for the privilege of existing as a registered entity in a state, which is why it is not an income tax and why it lands on businesses that made nothing at all.
That is the year it gets forgotten. A business that paused, a project entity that never traded, an out-of-state company registered for a contract that ended: each continues to owe while it remains registered, and the correspondence often goes to an address nobody checks any more.
- The liability attaches to registration, so it ends on formal dissolution or withdrawal rather than on ceasing to trade
- An entity registered in several states generally owes in each of them
- The basis of calculation differs by state, with some charging a flat amount and others measuring capital, margin or another value
- Keep the registered agent and address current, because missed notices do not excuse a missed filing
Staying in Good Standing
The consequence of falling behind is not only the amount owed. An entity that does not file or pay can lose its good standing, and the effects of that reach into ordinary business.
A suspended or forfeited entity may be unable to bring or defend a legal action, may find contracts questioned, and will generally fail the checks a lender, a landlord, an insurer or an acquirer runs. Discovering it during a transaction is the expensive version, because reinstatement takes time that the transaction usually does not have.
The routine that prevents it is short: know which states the entity is registered in, hold the filing dates for each in one calendar, keep the registered agent details current, and check standing once a year rather than when someone asks. Rates, bases and deadlines are set by each state and change with legislation, so take the current figures from the state agency directly.
Which States Charge It, and on What Basis
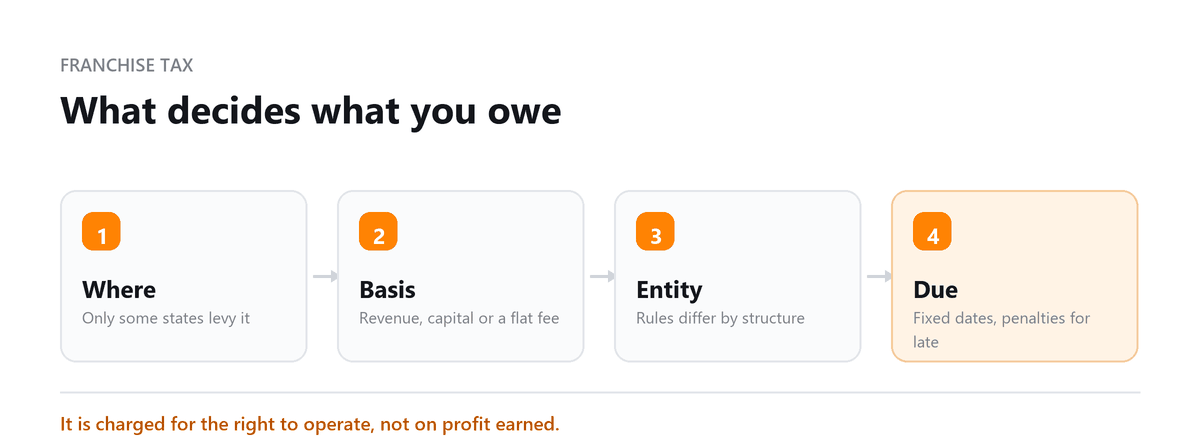
Franchise tax is not a single tax with one set of rules. It is a category, and the states that levy one differ in what they call it, what they measure and who it applies to.
- Some charge a flat amount per entity regardless of size or activity
- Some measure it on the capital or net worth of the business
- Some measure it on revenue or on a margin after defined deductions
- Some apply it to particular entity types only, so an LLC and a corporation in the same state may be treated differently
- Some combine a minimum amount with a calculated one, and charge whichever is higher
The practical consequence for a business registered in several states is that each one has to be handled on its own terms, and a process built around one state's rules will not transfer. Build the calendar from the states you are actually registered in, confirm each state's basis and dates from its own revenue department or secretary of state, and review the list whenever the business registers somewhere new or withdraws from somewhere old.
Book a free consultation and we will check every state you operate in.
FAQs
What is franchise tax, and how does it work?
Franchise tax is a state-level tax or fee that some businesses must pay for the privilege of conducting business in a state. It is separate from federal income tax and may be based on factors such as revenue, business activity, or net worth rather than taxable profit. Requirements vary by state and entity type.
Which states have a franchise tax in 2026?
Several states impose a franchise tax or similar business-level tax, including Texas, Delaware, and Tennessee, although the tax name, calculation method, exemptions, and filing requirements differ. Businesses operating across multiple states should check each state's current rules to determine their obligations.
Does Texas have a franchise tax in 2026?
Yes. Texas imposes a franchise tax on taxable entities doing business in the state. For the 2026 franchise tax report, the no-tax-due threshold is $2.47 million in annualized total revenue. Businesses above or below the threshold may still have reporting requirements. (Texas Comptroller)
Does California charge a minimum franchise tax?
Yes. California generally requires corporations doing business in the state to pay an $800 minimum franchise tax. California LLCs are also generally subject to an $800 annual tax, along with an additional LLC fee when California income reaches applicable thresholds. Certain first-year exceptions and other exemptions may apply depending on the entity and circumstances. (State of California Franchise Tax Board)
Do businesses have to pay franchise tax if they have no profit?
In some states, yes. Franchise taxes may be calculated using revenue, capital, margins, or a minimum fixed amount rather than net income. For example, California generally requires the $800 minimum franchise tax from qualifying corporations even when they operate at a loss.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Owe Franchise Tax Somewhere?
Book a free consultation and we will check every state you operate in.