
State Unemployment Insurance or SUI, also SUTA tax, refers to an employer’s payroll tax from which unemployment insurance benefits are paid to the jobless workers. For every company that employs individuals on its payroll, being aware of and considering possible state UI taxes is essential. They are highly volatile and depend on the state(s) a company operates in and the number of workers who are on layoff, file for unemployment claims, and register with the state’s EI system.
Consequently, the inaction on SUI tax matters is not an option for employers since they can balloon a company’s payroll costs. On the contrary, continuous analyses of UI claims enable the maintenance of low SUI tax liabilities.
Every employer with employees must understand SUI obligations, as rates vary significantly by state and by the employer's claims history.
The single most impactful step an employer can take to lower their SUI experience rating is to rigorously contest invalid claims with clear documentation within the state's response deadline
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat Is SUI Tax?
State Unemployment Insurance tax is collected by state governments and deposited into state unemployment trust funds. State Unemployment Tax Act (SUTA) tax is a payroll tax paid by employers to fund unemployment benefits for workers who are laid off. When an eligible worker is laid off (not fired for cause or resigning voluntarily), they draw unemployment benefits funded by this pool.
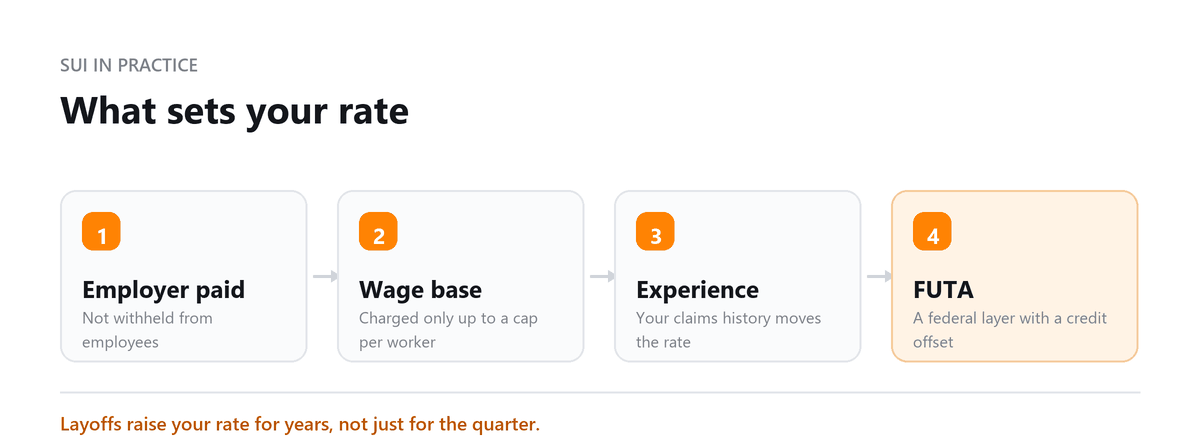
· SUI is an employer-paid tax in most states (exceptions: Alaska, New Jersey, and Pennsylvania require a small employee contribution)
· SUI applies only to wages up to the state wage base, not all wages
· The rate varies based on the employer's 'experience rating', a history of prior unemployment claims
SUI vs FUTA: Key Differences
| Factor | SUI (State) | FUTA (Federal) |
|---|---|---|
| Who administers | State workforce agency | IRS |
| Rate | Varies by state and employer experience | 6% on first $7,000 per employee |
| Effective FUTA rate | , | 0.6% after 5.4% state credit |
| Wage base | Varies by state ($7,000 to $62,500+) | $7,000 federal |
| Who pays | Employer (mostly) | Employer only |
| Purpose | Funds state unemployment benefits | Funds federal unemployment admin + state loans |
SUI Tax Rates Across the US, 2025
| State | 2025 Wage Base (approx.) | New Employer Rate (approx.) |
|---|---|---|
| California | $7,000 | 3.4% |
| New York | $12,500 | 4.1% |
| Texas | $9,000 | 2.7% |
| Florida | $7,000 | 2.7% |
| Illinois | $13,590 | 3.175% |
| North Carolina | $31,400 | 1.0% |
| Massachusetts | $15,000 | 2.42% |
Note: Rates for experienced employers can range from near 0% (for employers with no layoffs) to over 14% (for employers with high claims history). The wage base, the maximum wages subject to SUI per employee per year, also varies from $7,000 (federal minimum) to over $62,500 in some states.
How SUI Rates Are Determined
Most states use an 'experience rating' system:
· New employers receive a standard new employer rate for 1 to 3 years
· After that, rates are set based on the ratio of benefits paid to former employees vs total wages paid
· Employers with fewer claims pay lower rates; employers with high turnover and layoffs pay more
· Rates are assigned annually, typically in November or December for the following year
Reducing Your SUI Tax Bill
· Contest unemployment claims when employees were terminated for cause or resigned voluntarily
· Maintain thorough documentation of performance issues, policy violations, and resignation letters
· Consider voluntary contributions to the state trust fund to reduce your experience ratio and lower your rate
· Monitor your annual rate notice and appeal if you believe the calculation is incorrect
· Minimise unnecessary layoffs, even a few large claims can spike your rate for years
Do All States Have Unemployment Insurance?
Yes, all 50 states, DC, Puerto Rico, and the US Virgin Islands have unemployment insurance programs. However, the District of Columbia, Puerto Rico, and some territories have distinct rules. Federal civilian employees and ex-military members are covered by separate federal programs (UCFE and UCX).
Self-Employed Unemployment Insurance
Self-employed individuals are generally not eligible for traditional state unemployment insurance, they do not pay SUI and do not qualify for benefits. However:
· California offers voluntary SDI coverage for self-employed (see Post 14, california-sdi-tax)
· Some states offer Pandemic Unemployment Assistance (PUA) expansion programs, check current state law
· Business owners who also receive W-2 wages from their own corporation may be eligible for unemployment on those wages in some states
Profitjets client data shows that active claims management and experience rating audits lower SUI rates for multi-state employers by an average of 1.8% within two tax cycles.
Conclusion
SUI tax is a mandatory employer obligation in every state. Rates vary widely and are directly influenced by your layoff history. Proactive claims management, proper documentation, and annual rate review are the most effective ways to control SUI costs.
A mid-sized logistics firm partnered with Profitjets after a sudden spike in turnover pushed their state SUI rate above 6.2%. By auditing historical employee separations, contesting improper claims, and establishing streamlined exit documentation, Profitjets helped them lower their experience rate to 2.4% over 24 months saving the business over $42,000 annually in direct payroll tax liability.
Your Rate Is Experience-Rated
Unemployment tax is not a fixed cost. New employers start on a rate set by the state, and thereafter the rate moves with the claims history attached to the employer's account.
That makes it one of the few taxes an employer can genuinely influence, and it makes the claims process worth taking seriously. Claims that go unchallenged when there were grounds to respond, and claims charged to the wrong account, both raise a rate that then applies to the whole payroll for future periods.
- Respond to claim notices within the window given, since a late response generally forfeits the right to contest
- Keep documentation of the reasons for any separation at the time it happens
- Check the annual rate notice against your own record rather than filing it unread
- Review the account for charges that relate to people who were never your employees, which does happen
Rates, wage bases and the appeal windows are set by each state and revised annually, so work from the state agency's current notice.
Registering in a New State
The obligation follows the employee rather than the employer. An employee working in a state where you have never operated generally creates an unemployment obligation in that state, and it arises before the first payroll rather than after it.
Remote working has made this ordinary rather than exceptional. A single hire in another state typically means registering with that state's employment agency, and usually with its revenue agency for withholding as well, each with their own account, rate and filing calendar.
Where an employee works in more than one state, there are established rules for deciding which state the wages are reported to, based on where the work is localised, where the base of operations is and where the employee lives. Getting that wrong means reporting to the wrong state and having to correct both. Confirm the current requirements with each state's agency before the first payroll runs.
Reporting, Deposits and Reconciliation
The tax runs on a quarterly rhythm in most states, with a return reporting wages by employee alongside a payment, and it has its own reconciliation requirements separate from income tax withholding.
The wage base is the part that trips up payroll set up by hand. The tax is charged on wages up to an annual limit per employee, so the cost is front loaded into the early part of the year and stops once each employee passes the limit. The limit differs by state, which matters where an employee moves between states during a year and wages already counted in one state may or may not carry across.
- Reconcile the wages reported for unemployment purposes to the payroll records each quarter, not annually
- Watch the wage base reset at the start of each year, since the cost per employee changes noticeably
- Check that employees are reported to the correct state, particularly after any change in where someone works
- Keep the rate notice, the returns and the payment records together, since these are the first documents requested in any state payroll audit
Wage bases and filing dates are set by each state and change annually.
Book a free consultation and we will run SUI, FUTA and the filings.
FAQs
What is SUI tax and who pays it?
State Unemployment Insurance (SUI) tax is a state payroll tax that helps fund unemployment benefits for eligible workers. In most states, employers are responsible for paying SUI taxes, although state rules, wage bases, tax rates, and employee contribution requirements can vary.
What is the difference between SUI and FUTA tax?
SUI is administered at the state level, while FUTA is a federal employer tax. For 2026, the standard FUTA rate is 6% on the first $7,000 of wages per employee. Employers may generally receive a credit of up to 5.4% for qualifying state unemployment contributions, reducing the effective FUTA rate to 0.6%. (IRS)
What is the FUTA wage base for 2026?
The federal FUTA wage base is $7,000 per employee for 2026. FUTA generally applies only to the first $7,000 of wages paid to each employee during the year. State unemployment wage bases can be different and may change based on state law.
Can employers lose part of their FUTA tax credit?
Yes. Employers may receive a reduced FUTA credit if they operate in a credit reduction state or fail to meet applicable requirements for claiming the full credit. Credit reduction states are states with outstanding federal unemployment loans that meet the conditions for a FUTA credit reduction.
Do self-employed individuals pay FUTA or SUI tax?
Generally, no. FUTA applies to employers rather than self-employed individuals, and self-employed workers generally do not pay traditional state unemployment taxes on their own earnings. Eligibility for unemployment benefits depends on state law and the worker's employment status.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Payroll Taxes Handled?
Book a free consultation and we will run SUI, FUTA and the filings.