
A tax deduction lowers the amount of income that is subject to taxes. A tax credit reduces the amount of tax payable directly.
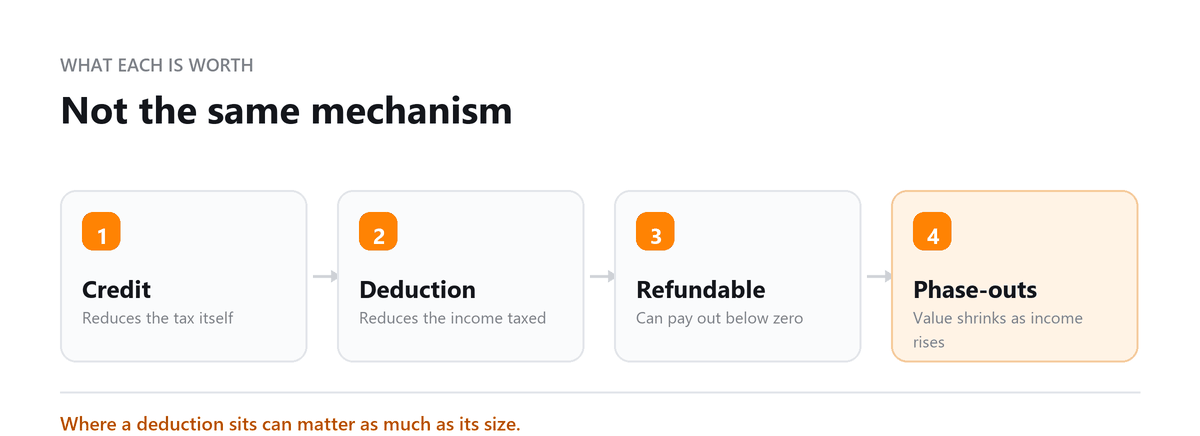
The difference is significant in and of itself. In comparison, tax credits and tax deductions both serve to reduce the amount of taxes one has to pay, yet they do so in a different manner. Whereas a deduction is subtracted for the taxable income amount on which one's taxes are based, a credit is subtracted from the taxes owed directly.
A tax credit is usually more valuable than a deduction of an equal amount and should be claimed whenever possible, but both types of tax reductions are beneficial. The value of the deduction depends entirely on the marginal rate, with 24%, a $1,000 deduction saves you $240. A $1,000 credit saves you $1,000, whoever you are.
Which is why a credit for which you qualify and fail to take is typically the most expensive item on your return. Deductions are given attention because of variety and relative ease of identification. Credits are missed because they are specific, with qualifying factors, and not spoken of nearly as much.
This guide will cover how each works, what business tax credits and deductions are most common, and where small businesses most commonly leave money on the table.
The overlooked one is the R&D credit. Businesses hear research and development and picture laboratories. The qualifying activity is far broader than that software development, process improvement, product iteration, a lot of ordinary engineering work qualifies. Companies doing genuinely eligible work go years without claiming because nobody framed what they do as research.
Anu Gupta, CA, EA, B.Tech · LinkedInThe Core Difference, With Numbers
Example: You earn $100,000 in taxable income. Your effective tax rate is 22%.
| $1,000 Deduction | $1,000 Credit | |
|---|---|---|
| How It Works | Reduces taxable income by $1,000 | Reduces your tax bill by $1,000 |
| Taxable Income After | $99,000 | $100,000 (unchanged) |
| Tax Before Application | $22,000 | $22,000 |
| Tax After Application | $22,000 − ($1,000 × 22%) = $21,780 | $22,000 − $1,000 = $21,000 |
| Tax Saved | $220 | $1,000 |
| Relative Value | $220 of benefit | $1,000 of benefit, 4.5x more valuable at 22% tax rate |
Tax Credits Explained
Tax credits reduce your tax bill directly, $1 credit = $1 less tax owed. They are more valuable than deductions of the same size. The benefit does not depend on your tax rate.
Types of Tax Credits
| Credit Type | What It Means |
|---|---|
| Refundable | If the credit exceeds your tax bill, you receive the remainder as a refund. Example: Earned Income Tax Credit. |
| Non-Refundable | Can reduce your tax to $0 but not below, no refund for the excess. Example: Child and Dependent Care Credit (partially). |
| Partially Refundable | Has a refundable and non-refundable component. Example: Child Tax Credit. |
Common Business Tax Credits
| Credit | Who Qualifies | Value |
|---|---|---|
| R&D Tax Credit (Section 41) | Businesses with qualifying research and development activity | 20% of qualifying R&D expenses above a base amount, can be significant for tech, pharma, manufacturing |
| Work Opportunity Tax Credit (WOTC) | Employers hiring from certain target groups (veterans, felons, long-term unemployed) | $2,400 to $9,600 per qualifying hire depending on hours worked |
| Disabled Access Credit | Small businesses making access improvements for disabled employees/customers | 50% of eligible expenditures between $250 and $10,250 = max $5,000 credit |
| Employer Health Insurance Credit | Small businesses covering <25 employees at under-average wages | Up to 50% of premiums paid (via ACA marketplace plan) |
| Clean Energy Business Credits | Businesses installing solar, EVs, or eligible energy-efficient equipment | Vary, check current IRS guidance; Inflation Reduction Act expanded many credits |
| Employee Retention Credit (ERC) | COVID-era credit, 2020/2021 only (may still have outstanding claims) | Up to $26,000 per employee for 2020 to 2021 |
Tax Deductions Explained
Deductions reduce your taxable income. The tax saving equals the deduction amount × your marginal tax rate. Higher tax brackets benefit more from the same deduction.
Standard vs Itemised Deductions (Personal)
| Standard Deduction (2025) | Itemised Deductions | |
|---|---|---|
| Single / MFS | $15,000 | Medical expenses above 7.5% of AGI, state/local taxes (SALT, capped at $10K), mortgage interest, charitable contributions |
| Married Filing Jointly | $30,000 | Same categories; choose itemised only if total exceeds standard deduction |
| Head of Household | $22,500 | Same categories |
Common Business Deductions
| Deduction | Description |
|---|---|
| Business Expenses (Ordinary and Necessary) | Rent, utilities, software, subscriptions, marketing, supplies, any cost ordinary to your industry |
| Home Office Deduction | If you use a portion of your home exclusively for business: simplified method ($5/sq ft up to 300 sq ft) or actual expense method |
| Vehicle Expenses | Business mileage at IRS standard rate (67 cents/mile for 2024) or actual expenses |
| Section 179 Deduction | Immediate deduction of equipment/asset purchase (up to $1,220,000 for 2024) instead of depreciating over time |
| Bonus Depreciation | 100% first-year depreciation on qualified property (phasing down post-2022) |
| QBI Deduction (Section 199A) | Pass-through business owners may deduct up to 20% of qualified business income; subject to income limits and service business rules |
| Health Insurance Premiums | Self-employed owners can deduct 100% of health insurance premiums for themselves and family on Schedule 1 |
| Retirement Contributions | SEP-IRA: up to 25% of compensation or $69,000 (2024); Solo 401(k): employee $23,000 + employer 25% contribution |
Ordinary and necessary business expenses. Rent, utilities, software, marketing, supplies, professional fees anything ordinary for your industry and necessary for your business.
Home office. Requires regular and exclusive use for business, a desk in a shared living room generally fails. Simplified method at a set rate per square foot up to a cap, or actual expenses.
Vehicle. Standard mileage rate or actual expenses. Choose carefully in year one; switching later is restricted.
Section 179. Immediate deduction for qualifying equipment rather than depreciating it.
QBI deduction (Section 199A). Pass-through owners may deduct a portion of qualified business income, subject to income thresholds and restrictions on specified service businesses. This is the largest deduction most small business owners have.
Self-employed health insurance. Premiums for yourself and family, deductible above the line.
Retirement contributions. SEP-IRA and Solo 401(k) both allow substantial deductible contributions. A SEP can be funded up to the filing deadline including extensions, making it one of the few meaningful deductions still available after year-end. Solo 401(k) has different timing rules, particularly on when the plan must be established.
What to actually do with this
Look at credits first. They're worth more per dollar and they're the ones businesses miss. Go through the list above against what your business actually does, particularly R&D if you build anything.
Check whether missed years can be recovered. An amended return can generally claim a refund within a window broadly three years from filing or two years from payment, whichever is later. Missed credits and deductions from prior years are frequently recoverable and most people never look.
Keep the records contemporaneously. The R&D credit in particular requires documentation of qualifying activity. Reconstructing it two years later is harder and less credible than recording it as you go.
Ask about the payroll offset if you're pre-profit. A credit you can't use against income tax may still be usable against payroll tax, which is the difference between worthless and valuable for a startup.
Don't let a deduction drive a purchase. Spending $10,000 to save $2,400 is only sensible if you needed the thing. This is the reasoning behind a lot of poor December equipment purchases.
We run a software business and assumed our previous accountant had already captured everything available to us. During Profitjets review, they identified an R&D tax credit opportunity worth about $28,000 that we hadn't claimed. They went through our development payroll and project records, documented the qualifying work, and helped us include the credit in our return. I had expected the review to find a few small deductions, but recovering nearly $28,000 from something we didn't even know we were missing made a huge difference.
Book a free consultation and we will check what you are entitled to.
Frequently Asked Questions
Is a credit or a deduction better?
A credit, per dollar, always. It reduces tax directly while a deduction only reduces the income being taxed. How much better depends on your bracket, the credit's advantage is largest at low marginal rates and narrows as your rate rises. You don't usually choose between them anyway; claim whatever you're entitled to.
Can I claim a credit and a deduction for the same expense?
Generally not for the same dollars. The R&D credit, for instance, requires reducing your deduction for those expenses by the credit amount, or making an election that adjusts it. The rules differ by credit, and the interaction is one of the more common places self-prepared returns go wrong.
What if my credit is bigger than my tax bill?
Depends on the credit. Refundable ones pay the excess back. Non-refundable ones take you to zero and the remainder is either lost or carried forward, depending on the specific credit. Check which applies before writing off an unused credit in a loss year.
Can I claim credits I missed in past years?
Often yes, by amending. The window is generally three years from filing or two from payment, whichever is later. Unclaimed R&D credits in particular are commonly recoverable, worth a review if you've been doing qualifying work without claiming.
Are business deductions worth more than personal ones?
Business expenses reduce both income tax and self-employment tax, so effectively they save at a higher combined rate than personal deductions at the same bracket. That's one reason to be rigorous about capturing legitimate business expenses, and about keeping them cleanly separated from personal spending, since mixed accounts make them hard to evidence.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Leaving Money on the Table?
Book a free consultation and we will check what you are entitled to.