
Accounting Cycle Example: Sweet Treats Bakery
To make the accounting cycle concrete, consider Sweet Treats Bakery, a small cupcake business. The owner sells $500 worth of custom cupcakes to a corporate client on account. Here is how that single transaction flows through all eight steps of the accounting cycle and eventually lands in a set of financial statements the owner can take to the bank.
The accounting cycle sounds mechanical, but it's actually a discipline. When each step is done on time every month, you get financial statements you can trust, and that's what allows you to run your business on facts rather than guesses.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat are the Steps of the Accounting Cycle?
Step 1: Identifying Transactions
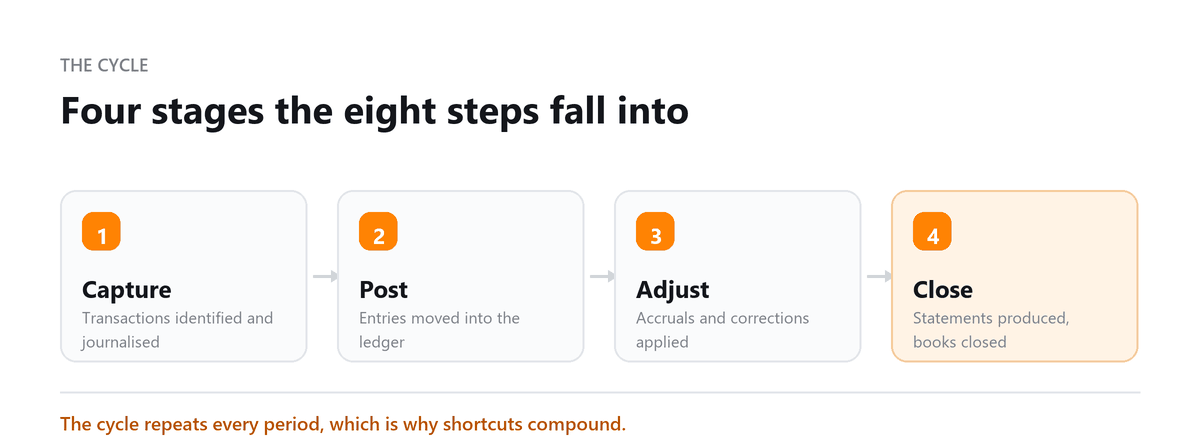
The cycle begins by recognizing economic events that have financial impact on the business. Not every business event qualifies, only those that can be measured in money terms and affect at least two accounts. Source documents provide the evidence: sales invoices, purchase receipts, bank statements, payroll records, loan agreements, and credit card statements. For Sweet Treats Bakery, the $500 cupcake sale is identified through the customer invoice issued to the corporate client.
Step 2: Recording Transactions in a Journal
Once identified, each transaction is recorded in chronological order in the general journal, the accounting system's first book of entry. Journal entries use the double-entry format: at least one account is debited and at least one is credited, and the total must balance. For our bakery example, the entry records a debit to Accounts Receivable (the corporate client owes $500) and a credit to Sales Revenue ($500 earned). The entry includes the date, account names, amounts, and a brief description.
Step 3: Posting to the General Ledger
Journal entries are then posted, transferred, to the general ledger, which organizes every transaction by individual account. Each account accumulates its running balance as entries are posted. The Accounts Receivable ledger account now shows $500 added to its balance; the Sales Revenue account reflects the same $500 credit. The ledger is the master reference, any question about an account's balance is answered here.
Step 4: Trial Balance
At the end of the accounting period, the accountant prepares a trial balance, a list of all ledger account balances, showing debits in one column and credits in another. The purpose is to verify that the double-entry system is in balance: total debits must equal total credits. If they do not, an error has occurred somewhere in the journal entries or posting. For Sweet Treats Bakery's monthly close, this step catches any entry that was posted incorrectly before financial statements are prepared.
Step 5: Adjusting Entries
Regular journal entries capture cash transactions and invoiced sales, but many economic activities happen continuously without a triggering document, depreciation of equipment, accrual of wages owed but not yet paid, expiration of prepaid insurance. Adjusting entries record these items at period end so that the financial statements reflect economic reality rather than just cash movement. For the bakery, this step might include recording one month's depreciation on the commercial oven and accruing wages earned by staff in the last days of the month.
Step 6: Adjusted Trial Balance
After all adjusting entries are posted, the accountant prepares a second trial balance, the adjusted trial balance, to verify that the books are still in balance after the adjustments. This is the clean starting point for financial statement preparation. Every account balance on the adjusted trial balance flows directly into one of the financial statements.
Step 7: Financial Statements
The three core financial statements are prepared from the adjusted trial balance:
- Income Statement: Revenue minus expenses equals net income or net loss for the period. The bakery's $500 cupcake sale appears here as revenue.
- Balance Sheet: A snapshot of assets, liabilities, and equity at period end. Accounts receivable and equipment appear as assets; the owner's investment and retained earnings appear in equity.
- Cash Flow Statement: Reconciles net income to actual cash generated or consumed. The bakery's $500 sale on account has not yet generated cash, that difference appears here.
Step 8: Closing Entries
The final step zeros out all temporary accounts, revenue, expenses, and dividends, and transfers their net balances to Retained Earnings. This resets the income statement accounts to zero for the new period while preserving the cumulative equity balance on the balance sheet. Revenue and expense accounts are temporary because they measure activity for a specific period; the balance sheet accounts are permanent because they carry forward indefinitely. After closing entries, the post-closing trial balance confirms that only balance sheet accounts have non-zero balances.
The Importance of the Accounting Cycle
The accounting cycle is not bureaucratic overhead, it is the mechanism through which financial chaos is transformed into reliable information. Its value to a business includes:
- Accuracy: Each step checks the previous one, creating a built-in error-detection system.
- Informed decision-making: Financial statements produced at the end of each cycle give management current data to act on.
- Regulatory compliance: Auditors, tax authorities, and lenders all rely on financial statements built through a proper accounting cycle.
- Operational efficiency: A documented, repeatable cycle reduces close times and minimizes last-minute scrambling at year end.
Why Choose Profitjets
Profitjets manages the full accounting cycle for small and mid-size businesses, from daily transaction recording through month-end close and financial statement delivery. Our clients typically receive a complete close package within five business days of month end, giving management timely data to act on without the overhead of an internal accounting team.
Conclusion
The accounting cycle is the heartbeat of sound financial management. Each of its eight steps builds on the last, creating a reliable, auditable trail from raw transaction to finished financial statement. Understanding how the cycle works, and insisting it runs on schedule every period, is one of the highest-return habits a business owner can develop.
From the Profitjets Team
Profitjets has worked with more than 50 businesses on their monthly accounting cycles, helping move transactions from the initial journal entry through reconciliation and final financial reporting.
In many of these reviews, 5 to 15% of monthly entries have needed some form of correction, reclassification, or additional documentation. Catching these issues during the accounting cycle helps prevent small recording errors from carrying into the financial statements.
Book a free consultation and we will close your books on a fixed date each month.
Frequently Asked Questions
How long does the accounting cycle take?
For most small businesses, monthly closes take 3 to 10 business days after month end, depending on transaction volume and how organized the records are. Outsourced accounting firms typically deliver close packages within 5 business days.
What is the difference between the accounting cycle and the budget cycle?
The accounting cycle records what already happened, past transactions. The budget cycle plans for what should happen, future revenue and expenses. Both run on the same period timeline but serve opposite directions.
Can accounting software automate the accounting cycle?
Software automates journal entry creation, ledger posting, and trial balance generation. Adjusting entries, financial statement review, and closing decisions still require human judgment, usually an accountant or CFO.
What happens if I skip adjusting entries?
Your financial statements will be inaccurate. Common omissions include unrecorded accrued expenses, uncounted depreciation, and prepaid expenses not properly allocated, all of which misstate profit and tax liability.
Is the accounting cycle different for cash basis versus accrual accounting?
Yes. Cash basis skips accruals and deferrals, so the cycle is simpler, there are few adjusting entries. Accrual accounting requires thorough adjusting entries to match revenue and expenses to the correct period.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Cycle Run for You?
Book a free consultation and we will close your books on a fixed date each month.