Selling your invoices to a third party for cash now, and collection from your customers later.
The factor will pay you a good part of the amount you are owed on an invoice within a day or so, and then will proceed to collect from your customer on when the account is due and you then get the rest of the amount you're owed minus their cut.
Though accounts receivable factoring is a great tool to have, it's important to really know how it works before using it.
Here's why:If you have $200000 in receivables due on Friday (and you need to pay some of that to your employees) and you have a cash flow problem, not a profitability problem, no amount of positive sales growth is going to help you before that money hits your account.
Though a 2% fee sounds cheaper than a 15% interest rate on a loan, when you annualize that 2%, invoice factoring can easily run you anywhere between 20-35%, which is still a price worth paying depending on your situation
Here's why this guide will show you how invoice factoring works, what it costs, the difference between recourse and non-recourse factoring, and what to do if your cash flow problems are of you're own doing.
Factoring makes sense when your customers are creditworthy, your terms are long, and the cash gap is structural rather than something you created. What I see more often is a business with a 55-day DSO on Net 30 terms considering factoring, and the actual problem is that invoices go out late and nobody follows up. Fixing that is free. Factoring that is expensive.
Ankit Sagatani, MBA, B.Com · LinkedInWhat is Factoring Accounts Receivable?
When a business factors its accounts receivable, it is essentially selling an asset (the right to collect future payment from a customer) for immediate cash. The factor pays the business an advance (typically 70-90% of the invoice value), collects payment directly from the customer when the invoice is due, and then pays the remaining balance to the business minus a fee.
How Does Accounts Receivable Factoring Work?
| Step | Description |
|---|---|
| 1. Invoice issued | Business delivers goods or services and issues a standard invoice to the customer |
| 2. Invoice sold to factor | Business submits the invoice to the factoring company for purchase |
| 3. Advance paid | Factor pays 70-90% of the invoice value to the business within 24-48 hours |
| 4. Factor collects | The factoring company collects payment directly from the customer on the invoice due date |
| 5. Reserve released | After the customer pays, the factor pays the remaining 10-30% to the business, minus the factoring fee |
Worked Example
| Item | Amount |
|---|---|
| Invoice value | $10,000 |
| Advance rate | 80% |
| Advance paid to business | $8,000 (within 24-48 hours) |
| Factoring fee (2% of invoice) | $200 |
| Reserve released after customer pays | $1,800 ($2,000 reserve minus $200 fee) |
| Total received by business | $9,800 ($8,000 + $1,800) |
Types of Accounts Receivable Factoring
Recourse Factoring
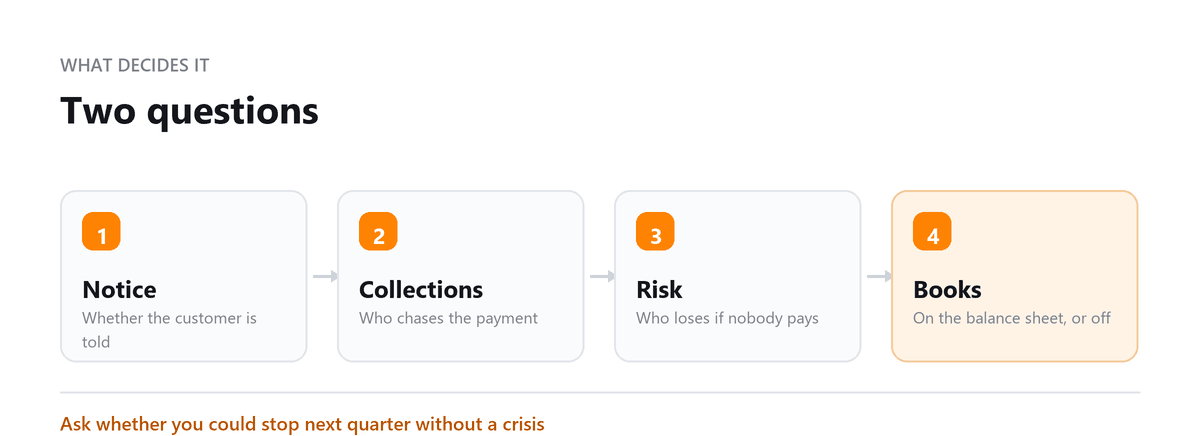
The most common type. If the customer fails to pay the invoice, the business must buy it back from the factor (repay the advance). The business bears the credit risk. Factoring fees are lower because the factor's risk is reduced.
- Advance rate: typically 80-90% of invoice value
- Fee: typically 1-3% of invoice value
- Risk: business bears the risk if customer defaults
Non-Recourse Factoring
The factor assumes the credit risk. If the customer fails to pay due to insolvency or bankruptcy, the factor absorbs the loss, the business does not repay the advance. Higher fees reflect this risk transfer.
- Advance rate: typically 70-85% of invoice value
- Fee: typically 3-5% of invoice value
- Risk: factor bears the risk if customer is insolvent (but not if customer simply disputes the invoice)
Accounts Receivable Factoring Rates
Factoring costs depend on:
| Factor | Impact on Rate |
|---|---|
| Invoice volume | Higher volume = lower rate per invoice (economies of scale for the factor) |
| Customer credit quality | Factors pay more for invoices from creditworthy enterprise customers |
| Invoice terms | Longer net terms (Net 60, Net 90) increase factoring cost vs Net 30 |
| Recourse vs non-recourse | Non-recourse is 1-2% more expensive, factor bears credit risk |
| Industry | Some industries (construction, healthcare) carry higher rates due to payment dispute frequency |
Typical factoring rates: 1-5% of invoice value, depending on the factors above. On an annualised basis, factoring can be expensive, a 2% fee on a Net 30 invoice is equivalent to approximately 24% APR. It is not a substitute for longer-term financing but is valuable for short-term cash flow management.
Benefits of Accounts Receivable Factoring
- Immediate cash flow: access 70-90% of invoice value within 24-48 hours instead of waiting 30-90 days
- No new debt: factoring is not a loan, the business sells an asset rather than borrowing, so it does not appear as debt on the balance sheet in most cases
- Outsourced collections: the factor handles collection from customers, freeing the business from AR management
- Scales with revenue: as the business invoices more, available factoring capacity grows automatically, unlike a fixed line of credit
- Credit assessment by the factor: factors evaluate customer credit quality, giving the business a free credit check on new customers
Accounts Receivable Factoring vs Invoice Financing
| AR Factoring | Invoice Financing | |
|---|---|---|
| Structure | Sell the invoice (asset sale) | Borrow against the invoice (loan) |
| Who collects from customer | Factor collects directly | Business collects; loan repaid from proceeds |
| Customer relationship | Customer pays the factor | Customer relationship unchanged |
| Advance rate | 70-90% of invoice | 70-85% of invoice |
| Fee structure | 1-5% of invoice value | 0.5-3% per month on outstanding balance |
| Appears as debt? | No (asset sale in most cases) | Yes (loan) |
| Credit check | Factor checks customer credit | Lender checks business credit |
Book a free consultation and we will look at the cheaper fix first.
Frequently Asked Questions
Is AR factoring the same as invoice factoring?
Yes. The terms are used interchangeably for the same arrangement: selling outstanding invoices to a third party for immediate cash.
Who typically uses factoring?
Industries with long payment cycles and creditworthy customers: staffing, trucking and logistics, manufacturing, wholesale distribution, government contracting. It's uncommon in B2C, where individual consumer credit is too varied for a factor to assess.
How quickly can I get the money?
Usually 24 to 48 hours for an advance once the facility is set up. Setting it up takes longer, the factor assesses your customers, reviews your invoicing and agrees terms, which typically runs one to three weeks. Arrange the facility before you need it, not during the week you're short.
Is factoring bad for my business?
It's a tool with a price. Used for a structural gap, long customer terms against short payment obligations, it's a reasonable cost of doing business, and whole industries run on it. Used to paper over slow invoicing or weak collections, it's an expensive way to avoid fixing something free. The distinction is whether the gap would still exist if your AR process were excellent.
Can I factor just one invoice?
Spot factoring exists and some factors offer it, usually at a higher rate than a committed facility. Many require minimum monthly volumes and charge if you don't meet them, so if you only expect occasional need, confirm that specifically before signing, minimum volume commitments are a common source of unexpected cost.
Written by
Ankit Sagatani, MBA, B.Com
Ankit works with business owners across the US on industry-specific bookkeeping, from real estate to construction and retail. He writes about what each trade's books actually need. Connect on LinkedIn Connect on LinkedIn
Free consultation
Cash Tied Up in Invoices?
Book a free consultation and we will look at the cheaper fix first.