A 1031 exchange allows an investor to defer a payment of taxes that are owed on gains realized by selling one investment property by investing the sale proceeds in another. However, these taxes are not entirely forgiven, they become due at termination of the replacement property, and the amount is based on the gain that triggered the exchange.
The process itself is well-documented and heavily utilized. Investors frequently make errors during the execution process, however, due to the particularity of the rules. For instance, a 1031 exchange requires two strict deadlines, prohibits the usage of the funds received from the sale of the property at any point, strictly defines the reinvestment amount, including debt payoff.
Each of these details, if mishandled, can result in the failure of the exchange and taxation on the gain. Additionally, there is no allowance for partial performance, nor is there an option for appeal, the gain will be subject to taxation at whatever point the abovementioned rules are breached, and investors will owe money at the point of sale, closing, or surrender of the replacement property.
This article will discuss the fundamentals of a 1031 exchange, analyze the elements that qualify or do not qualify for such an exchange, its deadlines, and the primary sources of error.
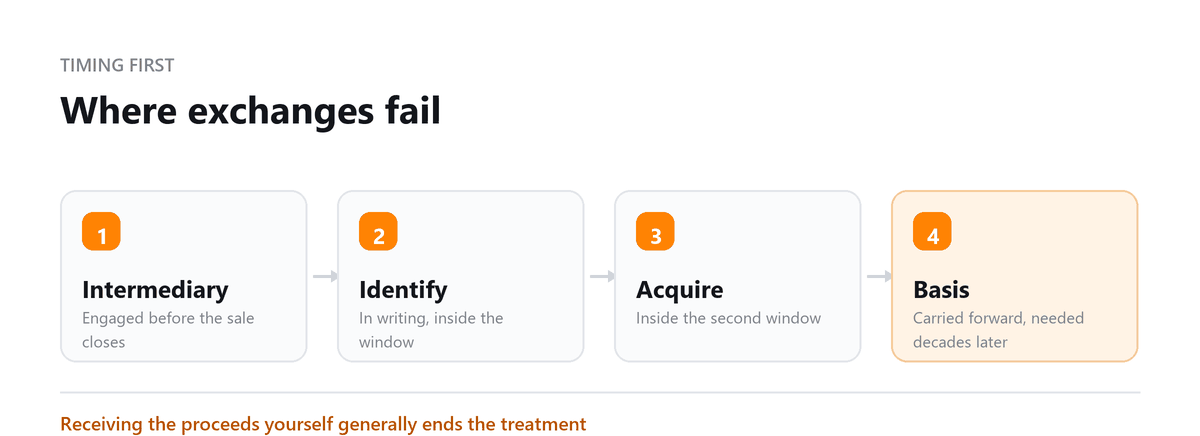
The most common failure isn't exotic, it's the investor who takes receipt of the sale proceeds, even briefly, because the closing was arranged before anyone brought in a qualified intermediary. Once those funds touch your account, the exchange is dead and no amount of good intention afterward revives it. The QI has to be engaged before closing. Every other mistake on this list is recoverable with planning. That one isn't.
Anu Gupta, CA, EA, B.Tech · LinkedInWhat is a 1031 Exchange?
A 1031 exchange allows a real estate investor to sell an investment property and defer capital gains tax on the profit, provided they reinvest the proceeds into a like-kind replacement property within the statutory time limits. The tax is not eliminated, only deferred, it becomes due when the replacement property is eventually sold without another 1031 exchange.
Example: An investor purchases a rental property for $400,000. They later sell it for $700,000, a $300,000 gain. Without a 1031 exchange, they would owe capital gains tax on the $300,000 gain (potentially $60,000+ in federal tax). With a 1031 exchange, the full $700,000 proceeds are rolled into a replacement property, and no tax is due at the time of sale.
What Does 'Like-Kind' Mean in Section 1031?
Despite the name, 'like-kind' is broader than most investors realise. Under Section 1031, any US investment real estate is considered like-kind to any other US investment real estate:
- A single-family rental can be exchanged for an apartment building
- A vacant lot can be exchanged for a commercial office building
- A retail strip centre can be exchanged for a warehouse
- Raw land can be exchanged for a rental house
What does NOT qualify as like-kind: personal residences, foreign property (US property only), inventory, and partnership interests (though Tenancy in Common interests in property can qualify).
What is the 'Deferred Tax' Benefit Under Section 1031?
The deferred gain accumulates across exchanges. Each time a 1031 exchange is completed, the tax basis of the original property carries into the replacement property, the deferred gain does not disappear, it simply transfers. However:
- Upon death, beneficiaries receive a stepped-up cost basis to fair market value, effectively eliminating the deferred gain permanently if the investor holds the property until death
- If the investor continues to exchange into larger and larger properties throughout their lifetime, they can potentially defer capital gains tax indefinitely while building a larger real estate portfolio
Section 1031 Exchange Timelines
Two statutory deadlines govern a 1031 exchange, both are strict and cannot be extended except in officially declared federal disaster areas:
| Deadline | Requirement | Count From |
|---|---|---|
| 45-day identification deadline | Investor must identify potential replacement properties in writing to the qualified intermediary | Day of sale of the relinquished property |
| 180-day exchange deadline | Investor must close on the replacement property | Day of sale of the relinquished property (not from the 45-day deadline) |
Missing either deadline terminates the exchange: the full capital gains tax becomes due on the original sale. Both deadlines are calculated from the same starting point (date of sale), not sequentially. If the 180-day deadline falls before the investor's tax return due date (April 15), the investor can extend their return to preserve the full 180 days.
Identification Rules for the 45-Day Window
Investors can identify replacement properties using one of three rules they can use only one rule per exchange:
| Rule | Constraint |
|---|---|
| 3-Property Rule | Identify up to 3 replacement properties of any value |
| 200% Rule | Identify any number of properties, but total fair market value cannot exceed 200% of the relinquished property's value |
| 95% Rule | Identify any number of properties of any value, but must acquire 95%+ of the total identified value |
Most investors use the 3-Property Rule it is the simplest and provides adequate flexibility.
What Is 'Boot' in a 1031 Exchange?
Boot is anything received in a 1031 exchange that is not like-kind property:
- Cash boot: proceeds from the sale not reinvested into the replacement property
- Mortgage boot (debt relief): if the replacement property has less debt than the relinquished property, the difference is treated as taxable boot
- Other property boot: personal property, furniture, or non-real estate items received in the transaction
Boot is taxable in the year of the exchange, it does not qualify for deferral. To avoid boot, the replacement property must be of equal or greater value than the relinquished property, and the investor must reinvest all proceeds (including equity).
Vacation Homes and Primary Residences
Primary residences do not qualify for 1031 exchanges, Section 1031 applies only to investment or business property. Vacation or second homes can qualify under specific rules:
- The property must be held for investment, not personal use
- The IRS safe harbour requires: held for 24+ months (before and after the exchange); rented at fair market value for at least 14 days per year; personal use limited to the lesser of 14 days or 10% of days rented at fair market value
Frequently Asked Questions
Book a free consultation and we will map the timeline with you.
Frequently Asked Questions
Can I do a 1031 exchange on my primary residence?
No. Section 1031 covers property held for investment or business use only. A former residence converted to a genuine rental may qualify later, but conversion needs to be real and sustained rather than nominal, and the timing matters. Note that a primary residence has its own exclusion under Section 121, which is a different provision and often more valuable worth comparing before assuming an exchange is the right route.
What is a qualified intermediary?
A third party who holds the proceeds between your sale and your purchase, so you never take receipt of them. Using one is effectively required for a valid exchange, and they also prepare the exchange agreement and identification documents. Choose on track record and how client funds are held, not on fee, this party is holding your sale proceeds.
Can I use a 1031 exchange for stocks, crypto or equipment?
No. Since 2018 the provision applies only to real property. Before then, personal property including equipment and collectibles qualified; that's no longer the case.
What happens to the deferred tax eventually?
It comes due whenever you sell without another exchange. If you hold until death, your heirs generally receive a stepped-up basis to fair market value, which eliminates the deferred gain which is why the exchange-until-death strategy exists. That's an estate planning decision rather than a tax filing one, and it needs proper advice.
Can I take some cash out of the exchange?
Yes, and you'll pay tax on it as boot. A partial exchange is perfectly valid; you defer on the portion reinvested and pay on the rest. What causes trouble is boot that wasn't planned for, particularly mortgage boot arising from replacing a property with one carrying less debt.
Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Planning an Exchange?
Book a free consultation and we will map the timeline with you.