
When the fiscal year approaches, most of the small business owners are in a pickle to resolve issues in their books. Uncategorized mixed up transactions, reconciliations and inconsistency in financial records made the process even more difficult to track. Most of these issues impose ad-hoc decisions with the straining tax season.
But what if your issues are preventable with the quick fix. Last minute bookkeeping doesn't have to rely on poor quality. By prioritizing the right tasks and resolving the challenges will help the businesses approach tax filing stress and compliance burden Here’s the last minute prep checklist for small business owners before reaching the deadline or fiscal year end. These insights will guide you to fix the issues in sequence and prepare yourself in advance to remain secure for the next year.
Last-minute bookkeeping is always more expensive than planned bookkeeping, in time, in stress, and sometimes in penalties. But if you are already behind, doing it properly still beats doing it badly or not at all.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhy Last-Minute Bookkeeping Still Matters
Even when time is short, getting your books as accurate as possible matters enormously. Clean records help you avoid tax penalties, understand your true cash position, identify deductible expenses you might otherwise miss, give your accountant or CPA accurate data to work from, and close the fiscal year in a state that makes the next year easier to manage.
10 Last-Minute Bookkeeping Tips for Business Owners
1. Categorise Every Transaction
Work through your bank and credit card statements and assign the correct category to every transaction. This is tedious but non-negotiable, miscategorised expenses mean inaccurate reports and potentially missed deductions. Use your accounting software's bulk-categorisation tools to speed this up.
2. Reconcile Bank and Credit Card Statements
Match your internal records against every bank and credit card statement for the year. Any discrepancy is a sign of a missing transaction, a duplicate entry, or an error that needs to be corrected before you can produce reliable financial statements.
3. Separate Personal and Business Finances
If personal and business transactions have been mixed, identify and reclassify each one. Personal expenses must be removed from business records, or coded as owner draws, before your accounts are accurate. This is one of the most time-consuming parts of any catch-up engagement.
4. Track Down Missing Invoices and Receipts
Review your records for transactions without supporting documentation. Reach out to vendors for duplicate invoices, check your email for digital receipts, and reconstruct what you can from bank statements. Documentation matters for tax compliance, gaps leave you vulnerable.
5. Update and Archive Payroll Records
Ensure all payroll runs are correctly recorded, that employer tax contributions are accurately reflected, and that year-end payroll filings (W-2s, 1099s) are in order. Payroll errors can attract regulatory scrutiny and penalties.
6. Review and Write Off Bad Debts
Identify invoices that are genuinely uncollectable and write them off properly before year-end. Bad debt write-offs reduce your taxable income, but they must be recorded correctly and documented to withstand scrutiny.
7. Double-Check Asset Purchases
Any significant asset purchases made during the year should be recorded correctly, as capital assets subject to depreciation, not as immediate expenses (unless they qualify under Section 179 or similar provisions). Review with your accountant if unsure.
8. Generate Year-End Financial Reports
Once reconciliation is complete, produce your year-end profit and loss statement, balance sheet, and cash flow statement. These are the documents your CPA needs to prepare your tax return and the documents you need to assess how the year actually went.
9. Schedule a Consultation with a Tax Professional
Before finalising your year-end records, speak with your CPA or tax advisor. They can identify additional deductions, flag compliance issues, and advise on any year-end moves, like equipment purchases, pension contributions, or expense pre-payments, that may reduce your tax liability.
10. Outsource What You Can
If the volume of catch-up work is overwhelming, outsource it. Professional bookkeeping services can organise months of records far faster than a business owner working alone, and they know exactly what needs to be in order for tax filing. The cost is almost always less than the value of your time.
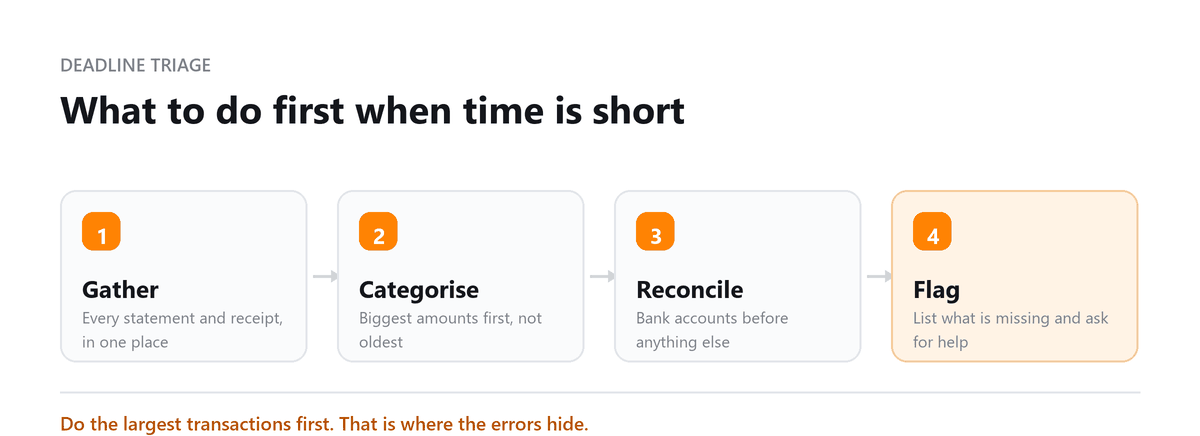
Extra Tips for 2026
- Use AI-assisted tools: Modern platforms like QuickBooks Online use machine learning to categorise transactions automatically reducing manual effort significantly.
- Back up everything to cloud storage: Ensure all financial records, receipts, and documents are backed up securely before year-end.
- Set a tax calendar reminder: Note every tax deadline for the coming year now, quarterly estimated payments, payroll filings, annual returns so you are never caught off guard again.
Through catch up bookkeeping services our team of experts at Profitjets helped businesses detect gaps and reorganize their pitfalls. We have implemented a structured and streamlined process to review and reconcile their financial activity. We even had clients with 24 months of unresolved challenges in bookkeeping. Most of them approached us when the process became a hassle disrupting their visibility so we have cleaned up and organized records structurally to improve their financial health.
Book a free consultation and we will catch the books up before the deadline.
Frequently Asked Questions
How long does it take to catch up on bookkeeping?
It depends on how far behind and how complex the records are. A professional catch-up bookkeeping service can typically organise several months of records within a week or two. Years of disorganised records take longer but are still manageable with the right approach.
Can I deduct expenses if I have lost the receipts?
In some cases, yes, if you have other credible documentation (bank statements, credit card records, vendor invoices). The IRS and most tax authorities accept reasonable documentation in place of original receipts. Consult your tax professional for guidance on specific situations.
Do I need a CPA, or can a bookkeeper handle my year-end?
A bookkeeper handles transaction recording, reconciliation, and report preparation. A CPA handles tax strategy, official filings, and compliance. For year-end, you typically need both, a bookkeeper to get the records in order and a CPA to file the return and advise on tax planning.
Is Excel good enough for year-end bookkeeping?
Excel can work for very simple situations, but it becomes error-prone at scale and does not integrate with bank feeds or produce standard financial statements automatically. Cloud accounting software provides significantly better accuracy, auditability, and reporting capability.
Should I outsource year-end bookkeeping?
If your books are significantly behind or you are not confident in their accuracy, yes, outsourcing is strongly recommended. Professional bookkeeping services specialise in catch-up work and can deliver audit-ready records far faster and more reliably than most business owners working independently.
Conclusion
Being behind on bookkeeping is stressful, but it is recoverable. Work through these ten steps methodically, get professional help if the volume is overwhelming, and use the experience to build better habits for the year ahead. The goal is not just to close out this year cleanly, but to enter next year in a position where last-minute scrambles are no longer part of the calendar.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Behind and Running Out of Time?
Book a free consultation and we will catch the books up before the deadline.