What is Account Reconciliation in Accounting?
Account reconciliation is the critical process where businesses verify that their financial statements are accurate and error-free. In practice, this means comparing the balances recorded in your internal accounting system against external statements, bank statements, vendor invoices, customer ledgers, and identifying any discrepancies that need to be investigated and resolved.
Reconciliation is not a single task; it is a category of verification activities that runs across multiple account types on a regular schedule. Done consistently, reconciliation ensures that the numbers in your books reflect reality, not just data entry. Done poorly or skipped entirely, it allows errors and fraud to compound undetected until they become material problems.
Monthly reconciliation is the single most powerful fraud prevention tool available to small businesses, and it costs almost nothing. Most fraud that persists for years does so because nobody was checking the bank statement against the books.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhy is Reconciliation Important?
- Prevents financial misstatements: Discrepancies caught during reconciliation, duplicate entries, misposted amounts, bank fees not recorded, prevent errors from reaching financial statements where they would mislead management and external stakeholders.
- Ensures regulatory compliance: Accurate books are the foundation of accurate tax filings. Unreconciled accounts frequently produce tax discrepancies that trigger IRS notices or audits.
- Detects fraud: The majority of small business fraud that persists for years does so simply because bank statements were never compared to internal records. Monthly reconciliation closes that window.
Types of Account Reconciliation
Bank Reconciliation
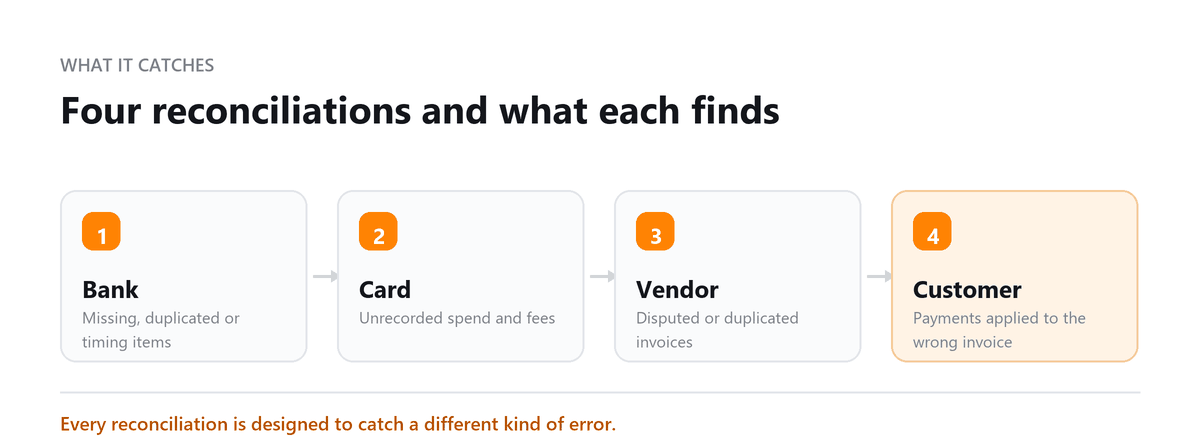
Bank reconciliation is the most common and fundamental type. It compares your internal Cash account balance against your bank statement balance for the same period. Common reconciling items include outstanding checks (issued but not yet cleared), deposits in transit (recorded in your books but not yet credited by the bank), bank service fees, and interest income. Every business with a bank account should complete bank reconciliation monthly at minimum.
Vendor Reconciliation
Vendor reconciliation compares the Accounts Payable balance in your books against the statements your vendors send. It confirms that every bill you have received from a vendor matches the amount you have recorded as owed, that payments are properly reflected, and that there are no disputed charges or duplicate invoices lurking in the balance. This process is especially important for businesses with many supplier relationships or high-volume purchasing.
Customer Reconciliation
Customer reconciliation confirms that the Accounts Receivable balance in your system, what customers owe you, matches the customer's own records of what they believe they owe. Discrepancies arise from timing differences, unapplied payments, disputed invoices, and credit memos. Proactive customer reconciliation speeds up collections and reduces bad debt write-offs.
Intercompany Reconciliation
Businesses with multiple entities, parent companies, subsidiaries, joint ventures, must ensure that transactions between those entities are recorded consistently in all sets of books. If Entity A records a loan to Entity B, Entity B must show the same loan as a liability. Intercompany reconciliation catches imbalances that would cause consolidated financial statements to be incorrect.
Credit Card Reconciliation
Credit card reconciliation matches the transactions on your credit card statements against the expense records in your accounting system. It catches expenses that were charged to a card but never recorded in the books, fraudulent charges, personal expenses that were incorrectly charged to a business card, and duplicate entries. Given the volume of credit card transactions in most businesses, this reconciliation benefits significantly from automation.
What Type of Accounting to Use for Reconciliation
Manual Reconciliation
In manual reconciliation, an accountant or bookkeeper downloads bank and vendor statements, compares them line by line against accounting records, and notes and investigates every discrepancy. Manual reconciliation is suitable for businesses with low transaction volumes and simple financial structures. It is time-intensive and prone to human error at scale, but it requires no additional software investment.
Automated Reconciliation
Modern accounting software dramatically accelerates reconciliation through bank feeds and rule-based matching. The software imports transactions directly from bank and credit card accounts, automatically matches them against accounting records, and flags unmatched items for human review. This approach reduces error rates, speeds close times, and is practical for businesses of any size. Leading tools include QuickBooks Online, Xero, and NetSuite.
| Software | Reconciliation Feature | Best For |
|---|---|---|
| QuickBooks Online | Automated bank feed matching | Small to mid-size businesses |
| Xero | Smart bank reconciliation rules | Growing businesses |
| NetSuite | Multi-entity reconciliation | Mid-market & enterprise |
Double-Entry Accounting and Reconciliation
Reconciliation is inherently linked to the double-entry accounting system. Because every transaction must be recorded as equal debits and credits, a trial balance that balances is the first internal reconciliation check. When the trial balance balances but a bank reconciliation reveals discrepancies, it signals that transactions were recorded with the correct mathematical structure but the wrong details, wrong amount, wrong account, or wrong timing. The two checks, trial balance and bank reconciliation, together catch different categories of errors.
Reconciliation Examples
- Bank reconciliation example: Your Cash account shows $42,800 at month end. The bank statement shows $43,150. The difference: a $450 check issued to a vendor has not yet cleared the bank (outstanding check), and the bank charged $100 in service fees not yet recorded in your books. Adjusted bank balance: $43,150 to $450 = $42,700. Books balance after adding bank fee: $42,800 to $100 = $42,700. Reconciled.
- Vendor reconciliation example: Your Accounts Payable shows $18,000 owed to Supplier X. Their statement shows $19,200. The difference is a $1,200 invoice from late in the month that was received by the vendor's system on the 30th but not processed in your books until the 2nd of the following month. Record the invoice and the balance reconciles.
How Profitjets Can Help
Profitjets performs monthly reconciliation across all account types as part of our standard bookkeeping service. Bank accounts, credit cards, vendor payables, and customer receivables are all reconciled as part of each monthly close, ensuring your financial statements are built on verified, accurate data from the ground up.
Conclusion
Account reconciliation is the most reliable tool available to small businesses for maintaining financial accuracy, detecting fraud, and building the trust in their numbers that lenders, investors, and tax authorities require. It takes discipline but not complexity, and for most businesses, modern accounting software makes it faster and more reliable than ever before.
From the Profitjets Team
Book a free consultation and we will find where the difference comes from.
Frequently Asked Questions
How often should a small business reconcile its accounts?
Monthly is the standard recommendation. Higher transaction volumes or businesses with multiple bank accounts, credit cards, or vendor relationships benefit from more frequent reconciliation, even weekly for cash-heavy operations.
What's the difference between account reconciliation and bank reconciliation?
Bank reconciliation is one specific type of account reconciliation, it compares your internal cash records to your bank statement. Account reconciliation is the broader process that includes vendor, customer, intercompany, and credit card reconciliations.
What causes reconciliation discrepancies?
Common causes include outstanding checks not yet cleared, deposits in transit, bank fees not recorded in your books, duplicate entries, and data entry errors. Each discrepancy must be identified and corrected before closing the period.
Can account reconciliation prevent fraud?
Yes, regular reconciliation catches unauthorised transactions, duplicate payments, and discrepancies early. Many small business frauds persist for years simply because bank statements were never compared to internal records.
Is automated reconciliation reliable?
Modern tools like QuickBooks, Xero, and NetSuite match transactions with high accuracy using bank feeds. However, human review is still required for unusual items, missing matches, and period-end adjustments, automation speeds the process, it doesn't eliminate judgement.
Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Books Not Reconciling?
Book a free consultation and we will find where the difference comes from.