
Most founders don’t have a Chief Accounting Officer (CAO), so when the post appears on an org chart or in a boardroom, the first question is often whether this is another CFO. It isn’t, and both roles are required in large organizations, for reasons that follow.
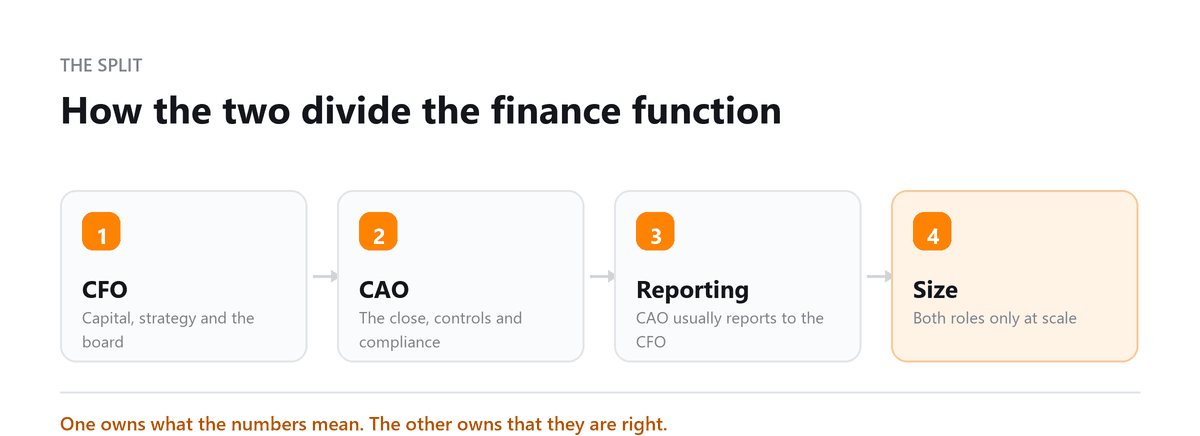
Both roles sit at the top of the finance org chart, both are responsible for the same financial statements, and both are present when the auditors arrive. The difference is direction: the CFO is externally focused and the CAO is internally focused. The former focuses on strategy, capital structure, and fundraising; the latter on execution, making sure that every number in those strategic financial statements is accurate, controlled, and able to withstand scrutiny.
Conflating the two roles creates risk in either direction. A strategist CFO overseeing a purely technical accounting operation is likely to find himself reviewing restated financial statements with the auditors, while a technically skilled CAO asked to interpret the financials for a fundraise may find himself with excellent reports but little ability to understand the business context behind them.
Expert Perspective
This guide covers what each role does, how they differ, where they overlap, and at what point a growing company should split them into two separate seats.
CFO vs CAO: Roles
What is a CFO?
A Chief Financial Officer (CFO) is the senior financial executive responsible for the overall financial strategy of the organization. The CFO manages capital allocation, investor relations, mergers and acquisitions, treasury operations, and the financial planning and analysis function. The CFO sets the financial direction of the business and communicates that direction to the board, investors, and lenders. They report to the CEO and interact directly with the board through the audit and finance committees.
What is a CAO?
A Chief Accounting Officer (CAO) is responsible for the technical accounting function of the organization. The CAO ensures financial statements are prepared accurately under GAAP, manages the accounting team, maintains internal controls, serves as the primary liaison to external auditors, and oversees technical accounting policy decisions. In public companies, the CAO signs management representation letters confirming the accuracy of financial statements. The CAO typically reports to the CFO, though in some organizations they report directly to the CEO or audit committee.
| Dimension | CFO | CAO |
|---|---|---|
| Primary focus | Strategy and capital | Accounting accuracy and controls |
| Financial statements | User and communicator | Owner and preparer |
| External relationships | Investors, banks, M&A advisors | External auditors, regulators |
| Typical background | Finance, investment banking, FP&A | Public accounting (Big 4), CPA |
| Reports to | CEO | CFO (typically) or CEO directly |
| Common in | Large, complex organizations | Public companies, financial services |
The CFO and CAO have to speak as one financial voice, even though they come at the numbers from opposite ends. The CFO translates the business for investors. The CAO makes sure what's being translated is correct. When those two aren't aligned, that's when restatements and audit findings start showing up.
Anu Gupta, CA, EA, B.Tech · LinkedInHow the CFO and CAO Work Together
The two roles meet most often at the financial close. Every month, quarter, and year, the CAO's team produces the financial statements, and the CFO reviews them, makes sense of the results, and presents them to the board and investors.
For public companies, earnings releases and SEC filings like the 10-K and 10-Q depend on that same handoff. The CAO makes sure every figure is technically right. The CFO shapes how those figures are explained to the market.
New accounting standards follow the same split. When FASB or IASB introduces something like ASC 842 for leases or ASC 606 for revenue recognition, the CAO leads the technical implementation. The CFO handles what the change does to reported results and how investors are told about it.
Audits work the same way. The CAO manages the auditors day to day, while the CFO takes the overall financial picture to the audit committee.
Building Your Dream Financial Team: CFO vs CAO
Think of it as vision versus infrastructure. The CFO decides what the finance function should become: what analysis it should deliver, how it should support business decisions, and how the team should be structured. The CAO builds the accounting foundation that makes that possible, including timely and accurate statements, strong controls, and a close process that runs cleanly every month.
In smaller companies, generally pre-IPO or under $500 million in revenue, one person often covers both roles. They hold the CFO title and also run accounting.
That changes as the business gets bigger and more complex. Once a company is heading toward an IPO or becomes subject to Sarbanes-Oxley (SOX) requirements, separating the CFO and CAO roles becomes important for both reporting quality and governance.
Hiring the Right Profile
These are very different people, and it's worth hiring for the difference.
A strong CFO thinks strategically, has led finance across several areas, communicates well in a boardroom, and is comfortable building relationships with investors, lenders, and advisors.
A strong CAO has deep technical accounting knowledge, almost always a CPA, and usually years at a Big 4 or large regional firm. They're detail-oriented and at ease making complex accounting judgments that will be tested under audit.
One of the most common mistakes is putting the wrong profile in the wrong seat. A technically brilliant accountant placed in a CFO role may struggle with strategy and investors. A strategic CFO placed in a CAO role may not have the technical depth the job needs. Either way, both functions end up with gaps.
Making the Partnership Work
The best CFO and CAO pairs keep a clear line between their areas and trust each other within them.
Day to day, that usually looks like this. The CAO runs the monthly close and sets its timeline, while the CFO reviews the results and builds the board presentation. The CAO handles auditor requests and technical accounting questions, and the CFO presents the audit outcome to the audit committee. When a new standard arrives, the CAO works out how to implement it and the CFO works out what it means for the business and how to communicate it.
Tax provisions, especially across multiple jurisdictions, are a shared area. The CAO manages the technical preparation, and the CFO looks at the strategic and financial statement impact. Here and elsewhere, the partnership holds up best when each person is open about what they know and doesn't try to overrule the other in their own territory.
Conclusion
The CFO and CAO are two halves of finance leadership in a complex organization. The CFO looks ahead, setting direction, managing capital, and communicating strategy. The CAO looks inward, making sure the numbers are right, the controls hold, and the audit relationship is well run. Companies that invest in both, and help them work as a real partnership, end up with financial reporting that is both accurate and genuinely useful for decisions.
We’ve worked with businesses where the accounting team was keeping the books moving, but nobody was really owning the financial picture at a leadership level. In one case, the CFO was spending too much time reviewing basic accounting issues instead of focusing on forecasting and business decisions, so we clarified the responsibilities between the accounting function and finance leadership and tightened the monthly reporting process. That gave the CFO more time to work on the decisions that actually required senior financial judgment.
Book a free consultation and we will run the close for you.
Frequently Asked Questions
What is the difference between a CFO and a CAO?
A CFO is the senior finance executive responsible for strategy, capital allocation, investor relations, and the company's overall financial health. A CAO is responsible for technical accounting: preparing accurate financial statements under GAAP, managing the audit relationship, and maintaining internal controls. In most companies, the CAO reports to the CFO.
Does a small business need a CAO?
Usually not. Small businesses generally have a controller or accounting manager running the accounting function. The CAO title is far more common in large public companies and financial institutions, where accounting is complex and the role carries board-level accountability. For most growing businesses, a strong controller reporting to the CFO is enough.
Can one person be both CFO and CAO?
Yes, and in many small and mid-size companies that's exactly what happens. The CFO handles financial strategy and also oversees accounting and the audit. As reporting requirements grow more complex, particularly around an IPO or public listing, the two roles are usually split.
What does a CAO do during a public company audit?
The CAO is management's main contact with the external auditors. They provide supporting documentation, explain accounting judgments, answer audit questions, and sign the management representation letter confirming the financial statements are accurate. The CFO is involved at the executive level, especially when results are presented to the audit committee.
Does a CAO need to be a CPA?
In practice, almost always. The role demands deep technical accounting expertise, and a CPA, or an equivalent international designation, is the standard proof of it. Most CAOs also spend years at a Big 4 firm, where they build technical skills across many audit clients.
Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Need the Controls Side Covered?
Book a free consultation and we will run the close for you.