
Ask a founder about cash, and they will inevitably open their banking app to show the magical number on the screen - the balance in their account. This metric is great, but it will not tell you how much money customers have outstanding invoices from you for, or how much money is due to suppliers.
These two figures are known as accounts receivable and accounts payable, respectively. The relationship between the two determines whether a company that has had a profitable month will have cash reserves to pay salaries or not.
Accounts payable (AP) is an invoice that a company owes to suppliers and contractors, whereas accounts receivable (AR) are invoices issued to customers that have not been paid yet: almost every small business has AP and AR in QuickBooks or Xero, and very few track the ratio of AR to AP, which is the root cause of most cash flow issues.
The pattern I see constantly is a business that looks healthy on the P&L and still struggles to pay its bills on time. Revenue is booked and margins are fine. nobody is watching DSO, so the gap stays invisible until the bank balance shows it. By then the fix is a line of credit, when it could have been a firmer conversation with two slow-paying customers months earlier.", Ankit Sarawagi, CA, Founder, Profitjets LinkedIn: https://www.linkedin.com/in/ankit-sarawagi/
Core Definitions
- Accounts Payable (AP): Money your business owes to suppliers, vendors, or service providers for goods and services received but not yet paid. AP is a current liability on the balance sheet. When you receive a supplier invoice with 30-day payment terms, AP increases. When you pay it, AP decreases.
- Accounts Receivable (AR): Money that customers owe your business for goods or services delivered but not yet paid. AR is a current asset on the balance sheet. When you issue an invoice, AR increases. When the customer pays, AR decreases.
Side-by-Side Comparison
| Dimension | Accounts Payable (AP) | Accounts Receivable (AR) |
|---|---|---|
| Definition | Money your business OWES to others | Money OWED TO your business by customers |
| Balance Sheet Position | Current Liability | Current Asset |
| Created When | You receive supplier/vendor invoice and defer payment | You issue a customer invoice and payment is pending |
| Eliminated When | You pay the supplier/vendor | Customer pays you |
| Cash Flow Effect | Delays cash outflow, preserves cash short-term | Delays cash inflow, starves cash if slow to collect |
| Key Metric | DPO, Days Payable Outstanding | DSO, Days Sales Outstanding |
| Goal | Pay on time (maintain supplier relationship) but not too early (preserve cash) | Collect as quickly as possible (minimise DSO) without damaging customer relationships |
| Risk if Managed Poorly | Late payments damage supplier trust; missed discount opportunities | Bad debts write-offs; cash flow gaps; inability to pay your own bills |
Key Metrics
| Metric | Formula | What It Tells You |
|---|---|---|
| Days Sales Outstanding (DSO) | (AR Balance / Annual Revenue) × 365 | Average days to collect payment after invoicing. High DSO = slow collections = cash flow risk. |
| Days Payable Outstanding (DPO) | (AP Balance / COGS) × 365 | Average days to pay suppliers. High DPO = you are using supplier credit longer. |
| Accounts Receivable Turnover | Net Credit Sales / Average AR Balance | How many times per year you collect your full receivables balance. Higher = faster collection. |
| Accounts Payable Turnover | COGS / Average AP Balance | How many times per year you pay your full payables. Lower = longer payment period. |
Cash Conversion Cycle
The cash conversion cycle (CCC) measures how long it takes for cash invested in inventory to return as cash from sales. It combines inventory, AR, and AP management:
CCC = DIO (Days Inventory Outstanding) + DSO − DPO
A lower CCC is generally better, your cash is tied up for fewer days. Businesses with negative CCC (common in retail and SaaS) collect cash before they pay suppliers, an extremely strong cash position.
Best Practices
AP Best Practices
- Use AP aging reports to track outstanding invoices by due date, never miss a payment by accident
- Negotiate payment terms with suppliers, 30/45/60 days are negotiable, especially for large or reliable customers
- Capture early payment discounts where offered (e.g. 2/10 net 30 = 2% discount if paid within 10 days, this is a 37% annualised return)
- Automate AP with accounting software (QuickBooks, Xero) to reduce manual errors
AR Best Practices
- Invoice immediately upon delivery, every day of delay in invoicing is a day added to collection
- Set clear payment terms upfront, 'Net 30' or 'Due on receipt'
- Send automated reminders at 7, 14, and 30 days overdue, most clients pay on reminder, not on invoice
- Review AR aging weekly, flag accounts over 60 days and escalate
- Consider invoice financing or factoring if DSO exceeds 45 days and cash flow is strained
Why You Have to Manage AP and AR Together
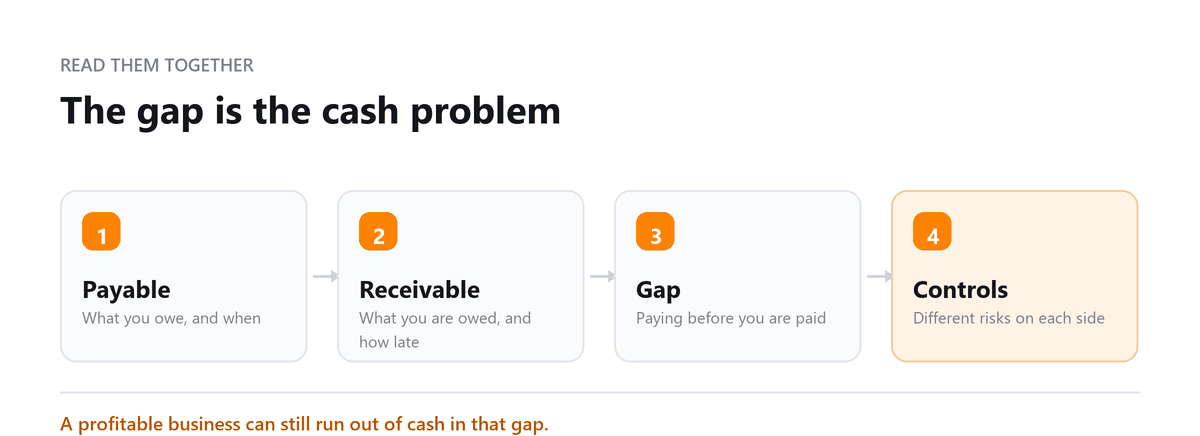
Looking at AP or AR on its own gives you half the picture. A business can collect efficiently and still run short of cash if it pays suppliers faster than it needs to. It can also stretch payables to the limit and still struggle because receivables are drifting out to 70 days. The number that matters is the gap between when cash leaves and when it comes back.
Most small businesses start out managing AP and AR reactively. Bills get paid when they're remembered, and customers get chased when the account runs low. The switch to managing both on purpose usually happens when a business hires a controller or fractional CFO, or after a cash crunch shows how much money was sitting in unpaid invoices.
Book a free consultation and we will find where the gap is.
FAQs
Is accounts payable a debit or a credit?
AP carries a credit balance, because it's a liability. When a supplier invoice comes in, you debit the expense or inventory account and credit AP. When you pay it, you debit AP and credit cash, which brings the balance back down.
Which matters more for cash flow, AP or AR?
For most small businesses, AR. Paying suppliers a few days later buys you a little breathing room. Invoices that sit unpaid for 60 or 90 days can leave a profitable business unable to cover its own bills. That doesn't make AP an afterthought. Missed early-payment discounts and late fees add up, and a supplier who stops extending credit is a cash problem of its own.
What's a good DSO for a small business?
It depends on the terms you offer, so the useful comparison is DSO against your own payment terms rather than an industry average. If you invoice on Net 30 and your DSO is 32, collections are working. If it has crept to 50, customers are treating your terms as optional, and it's worth finding out which accounts are responsible before the gap grows.
What happens if a customer never pays?
Once collection efforts are exhausted, the invoice is written off as a bad debt. Under the direct write-off method, you debit bad debt expense and credit AR. Businesses that follow GAAP and have material bad debts use the allowance method instead, which debits the allowance for doubtful accounts. On the tax side, most businesses can deduct a bad debt only when it's actually written off. Cash-basis businesses can't deduct an unpaid invoice at all, because that income was never reported in the first place.
That catches a lot of owners off guard.
Should AP and AR be handled by the same person?
At small scale it's common, and it's usually fine as long as someone else reviews the work. The risk is that one person who can both record customer payments and approve supplier bills can move money without anyone noticing, whether by mistake or on purpose. A simple fix is to have the owner approve payments and look over the AR aging report each month, even if one bookkeeper does the day-to-day entries.
Once the business grows enough to justify splitting the roles, separating who records cash coming in from who releases cash going out is one of the most basic internal controls you can put in place.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Cash Tight Despite Good Profit?
Book a free consultation and we will find where the gap is.