
Federal Tax Navigation in Illinois Illinois has a progressive state income tax with IRS tax brackets. Illinois’ individual income tax is set at a flat 4.95%.
State and Local Taxes Besides paying regular federal taxes on their annual federal income tax return (Form 1040), Illinois residents also pay higher local sales tax and state corporation taxes which make up for an overall higher tax bill compared to most other states.
Tax Optimization Strategies Understanding how your federal income tax withholdings interact with state taxes can help you as an individual/business owner maximize deductions while minimizing effective tax rates paid through proactive tax structuring strategies that protect earned incomes from unnecessary double taxation risks associated with failing to plan ahead strategically.
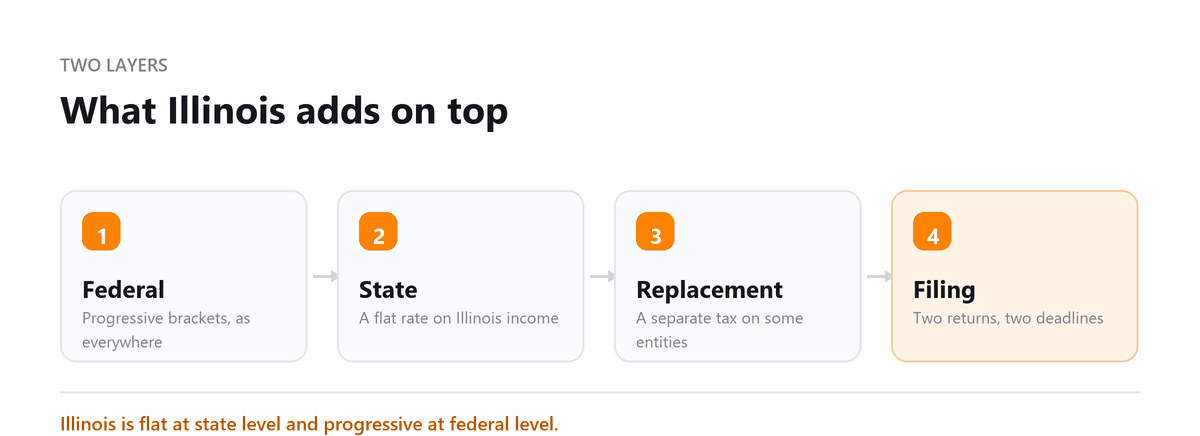
Illinois residents pay both federal income tax (progressive brackets, 10% to 37%) and Illinois state income tax at a flat 4.95% rate.
This guide covers both obligations so Illinois taxpayers understand their complete picture.
Because Illinois imposes a flat 4.95% state income tax directly on top of progressive federal brackets, a middle-income earner in Chicago often faces a combined marginal tax rate over 27%, nearly 5% higher than the national baseline for similar earnings in non-income-tax states.
Anu Gupta, CA, EA, B.Tech · LinkedInFederal Income Tax in Illinois
Federal tax rules apply identically to Illinois residents as to all US taxpayers. Illinois has no special federal tax status, residents file Form 1040 and pay federal income tax at the same progressive rates as every other state.
Federal Income Tax Rates in Illinois (2025 Tax Year)
| Rate | Taxable Income, Single Filer (TY2025) |
|---|---|
| 10% | $0 to $11,925 |
| 12% | $11,925 to $48,475 |
| 22% | $48,475 to $103,350 |
| 24% | $103,350 to $197,300 |
| 32% | $197,300 to $250,525 |
| 35% | $250,525 to $626,350 |
| 37% | Over $626,350 |
What Makes Illinois Unique: State Tax on Top of Federal
Unlike most states with graduated income tax rates, Illinois uses a flat individual income tax rate of 4.95%. This means all Illinois taxable income, regardless of how much you earn, is taxed at 4.95% by the state, in addition to your federal obligation.
| Tax Type | Rate / Structure |
|---|---|
| Federal income tax | 10% to 37% progressive brackets (TY2025) |
| Illinois state income tax (individual) | 4.95% flat rate |
| Illinois corporate income tax | 9.5% flat rate (7% income tax + 2.5% personal property replacement tax) |
| Illinois state sales tax | 6.25% (local add-ons may apply) |
Federal Tax Withholding in Illinois
Illinois employers withhold both federal income tax (per IRS tables) and Illinois state income tax (4.95%) from employee paychecks. FICA (Social Security 6.2% + Medicare 1.45%) is also withheld. The total withholding rate for a middle-income Illinois employee is substantially higher than for residents of no-state-tax states like Texas or Florida.
Taxation for Businesses in Illinois
Illinois businesses face multiple tax obligations:
· Federal corporate income tax: 21% flat (C-Corps) or pass-through treatment (S-Corps, partnerships, LLCs)
· Illinois corporate income tax: 9.5% on net Illinois income (including 2.5% PPRT)
· Illinois sales tax: 6.25% state rate; municipalities may add up to 4.75% on top
· Illinois franchise tax: applicable to foreign corporations registered in Illinois
· Illinois employers also pay state unemployment insurance (SUI) and may have local business tax obligations
Federal Tax Filing in Illinois
Illinois residents file Form 1040 with the IRS by April 15. Illinois state returns are filed separately with the Illinois Department of Revenue using Form IL-1040, also by April 15.
· IRS mailing for Illinois residents: Department of the Treasury, IRS, Kansas City, MO 64999-0002 (no payment); P.O. Box 931000, Louisville, KY 40293-1000 (with payment)
· IL-1040 deadline: April 15 (same as federal)
In 2025 to 2026, Profitjets evaluated and restructured state and federal tax positions for over 210 Illinois business clients, achieving an average reduction of $18,400 in annual combined tax liability through S-Corp election timing, Pass-Through Entity (PTE) tax optimization, and maximized retirement contributions.
Conclusion
Illinois taxpayers face one of the higher combined tax burdens among US states, federal progressive brackets plus Illinois's 4.95% flat state rate and 9.5% corporate rate. Coordinated federal and state tax planning is especially important in Illinois.
When an IT consulting firm owner in Naperville turned to Profitjets, their business was paying full federal income tax alongside Illinois's flat 4.95% state tax and 9.5% corporate burden as an unoptimized entity. By helping them transition to an S-Corporation structure and electing into the Illinois Pass-Through Entity (PTE) tax, we created a workaround for the federal SALT deduction cap. This single structural shift lowered their combined effective tax rate by 6.2%, saving the owner $34,500 in federal tax obligations in their very first year.
Filing Two Returns That Do Not Match
An Illinois filer prepares a federal return and a state return, and the second is not a copy of the first with a different rate applied. It starts from the federal figure and then adds and subtracts.
Those additions and subtractions are where errors live. Some income exempt federally is taxable in Illinois, and some income taxable federally is not taxed by Illinois, retirement income being the well-known example. Credits available federally may have no state equivalent, and the state has credits with no federal counterpart.
- Start from the federal return, but check every adjustment rather than assuming the base carries across
- Retirement income is treated distinctly in Illinois, which matters for anyone planning around it
- Property tax and education credits exist at state level with their own conditions
- Where income was earned in another state, check the credit for tax paid elsewhere before assuming double taxation
Registration and Payroll in Illinois
A business operating in Illinois registers with the Department of Revenue before it starts trading, and separately with the employment agency once it has staff. Both registrations are prerequisites rather than follow-ups.
Payroll brings state withholding on top of the federal obligations, with its own deposit schedule that depends on the size of the payroll, its own periodic returns and its own annual reconciliation. New hires have to be reported, and unemployment contributions run through a separate account with a rate assigned to the employer.
Businesses making taxable sales also register for sales tax, and Illinois is a state where local rates sit on top of the state rate, so the rate charged depends on location rather than being uniform. The Department of Revenue publishes current rates by address, and that lookup is the right source rather than a remembered figure.
Arriving or Leaving Part Way Through a Year
A move into or out of Illinois splits the year, and the split is handled through a part-year resident return rather than by choosing one state for the whole period.
Income is allocated between the periods based on when it was earned, which is straightforward for salary and considerably less so for anything received in a lump: a bonus relating to work done before the move, an equity event, or a payment for work performed over a longer stretch. Those are allocated on the period the income relates to rather than the date it was received.
Illinois also continues to tax income sourced to the state after you leave, so someone who moves away but keeps working for an Illinois employer, or who owns property there, may continue filing. Keep dated evidence of the move itself, since the question of when residency actually changed is one the state can revisit. Current guidance is published by the Illinois Department of Revenue.
Book a free consultation and we will handle both returns.
FAQs
What is the Illinois income tax rate in 2026?
Illinois has a flat individual income tax rate of 4.95% for 2026. Unlike states with graduated income tax brackets, Illinois generally applies the same rate to taxable net income regardless of income level.
Does Illinois have a flat or progressive income tax?
Illinois uses a flat individual income tax system. The state income tax rate is 4.95%, rather than different tax brackets based on income. Your actual Illinois tax liability can still vary based on exemptions, deductions, credits, and other adjustments. (Illinois Department of Revenue)
How much is Illinois corporate income tax in 2026?
C corporations generally pay a 7% Illinois corporate income tax on net income, plus a 2.5% Personal Property Replacement Tax (PPRT), for a combined statutory rate of 9.5%. S corporations and partnerships have different tax treatment and may be subject to a 1.5% replacement tax. (Illinois Department of Revenue)
Does Illinois income tax apply to business income?
Yes. Business income earned by a sole proprietor generally flows through to the owner's individual Illinois income tax return and is subject to the 4.95% individual rate. Partnerships and S corporations generally pass income through to their owners, although eligible entities may elect Illinois' 4.95% pass-through entity tax.
How does Illinois income tax compare with federal income tax?
Illinois imposes a separate 4.95% state income tax in addition to federal income tax. Federal income tax uses graduated brackets, while Illinois generally applies a flat rate. Because the two systems have different tax bases, deductions, exemptions, and credits, adding the two headline rates does not necessarily represent your effective combined tax rate.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Filing in Illinois?
Book a free consultation and we will handle both returns.