
Most business owners do not think about their federal tax liability until they are getting ready to prepare their return. By then, the year is over, the money has been made, and almost all the decisions that could have decreased their tax bill have already been made. The only thing left is to determine the number and, most of the time, figure out how to pay it.
The issue with tax liabilities is that they are often conflated with what one owes at filing time.
Tax liabilities are not the amounts owed; they are the amounts that should have been paid on the income that one has earned. The amounts owed at filing time are simply the difference between what was due and what was paid in withholdings and estimated payments.
A business owner can pay all the bills associated with their quarterly payments and still be shocked at what they owe at the end of the year if their business made more than they budgeted for.
Expert Perspective
This guide explains what federal tax liability is, how it's calculated, what isn't taxed, the main federal taxes businesses owe, and practical ways to reduce your liability within the rules.
The only value in knowing one's federal tax liability is that it allows them to control it throughout the year instead of simply learning about it too late. Understanding how the number is put together helps a person see what levers they have to make changes and, consequently, what they can change. The tax deductions, credits, business structure, timing, and payments that they can influence are all viable levers for changing one's tax liability.
A federal tax liability is the total amount of tax you owe the IRS for a given tax year, after accounting for deductions, credits, and withholding. Understanding your tax liability, and how to manage it, is fundamental to financial planning.
Most business owners underestimate their federal tax liability because they base it on what they took out of the business, not what the business earned. They'll draw $80,000, set aside tax on that, and then the return shows $140,000 of profit. Add self-employment tax on top of income tax, and the gap can be tens of thousands of dollars. By the time they see it in March, the only choices left are paying it or setting up a plan with the IRS.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is a Federal Tax Liability?
Your federal tax liability is the total amount of federal tax you owe for a tax year, after deductions and credits are applied but before subtracting any payments you've already made.
Once your liability is calculated, it's compared with what you've already paid through paycheck withholding and quarterly estimated payments. If you've paid less than your liability, you owe the difference when you file. If you've paid more, the IRS refunds the excess.
A Simple Example
ABC Co. is a C corporation with $150,000 of taxable income for the year. At the 21 percent federal corporate tax rate, its federal income tax liability is $31,500.
During the year, ABC Co. made $24,000 in quarterly estimated tax payments. When it files its return, it owes the remaining $7,500.
If ABC Co. had paid $35,000 in estimates instead, its liability would still be $31,500, and it would receive a $3,500 refund or apply it to next year's taxes.
What is Exempt From Federal Income Tax Liability?
Certain income types and taxpayer categories are partially or fully exempt:
- Income below the standard deduction threshold ($15,000 single / $30,000 MFJ for TY2025)
- Qualified gifts and inheritances (not income to the recipient)
- Municipal bond interest
- Life insurance death benefits
- Employer-paid health insurance premiums
- Certain veterans' benefits
How Federal Tax Liability is Calculated
For individuals, including sole proprietors, partners, LLC members, and S corporation shareholders who report business income on their personal returns, federal income tax liability is built in four steps.
Step 1: Calculate Adjusted Gross Income
Start with gross income from all sources, including wages, business profit, interest, dividends, and capital gains. Subtract adjustments such as contributions to certain retirement plans, HSA contributions, half of self-employment tax, and self-employed health insurance premiums. The result is your adjusted gross income, or AGI.
Step 2: Subtract Deductions to Find Taxable Income
From AGI, subtract either the standard deduction or your itemized deductions, whichever is larger. Many business owners can also subtract the qualified business income deduction. What remains is taxable income.
Step 3: Apply the Tax Rates
Apply the federal income tax brackets to your taxable income. Rates are progressive, so each slice of income is taxed at its own rate, starting at 10 percent. Long-term capital gains and qualified dividends are taxed at separate, lower rates. The result is your gross income tax liability.
Step 4: Subtract Credits and Add Other Taxes
Subtract any tax credits you qualify for. Credits reduce your tax dollar for dollar, which makes them more valuable than deductions of the same amount. Then add other federal taxes that apply, most importantly self-employment tax for business owners. The result is your total federal tax liability.
C corporations follow a simpler path. Taxable income is calculated at the corporate level and taxed at a flat 21 percent, before any business credits are applied.
The Federal Taxes Businesses Are Responsible For
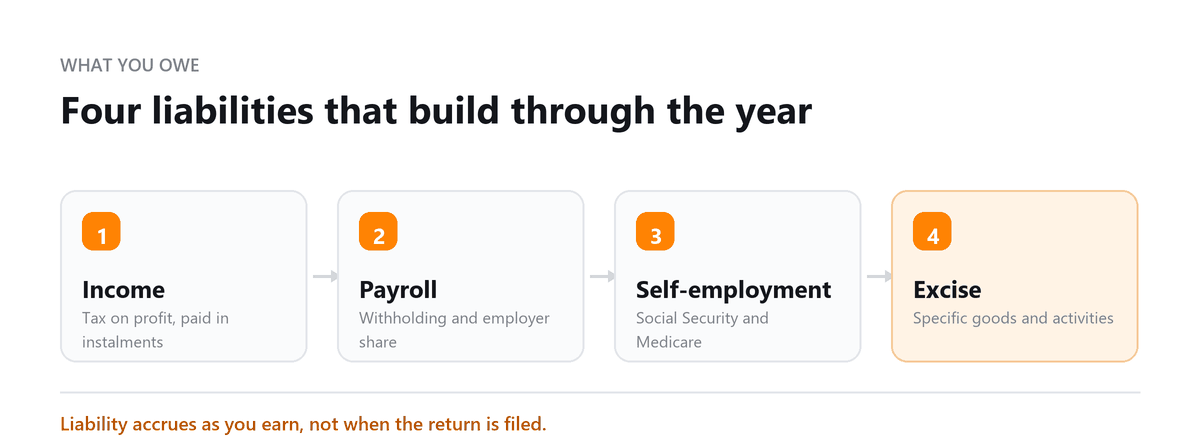
A business's total federal tax picture usually involves more than income tax.
| Federal Tax | Who It Applies To | What It Covers |
|---|---|---|
| Income tax | C corporations directly; owners of pass-through businesses on their personal returns | Tax on business profit |
| Self-employment tax | Sole proprietors, partners, and most LLC members | Social Security and Medicare on business earnings |
| Payroll taxes | Businesses with employees | Employer Social Security and Medicare, plus income tax and FICA withheld from employee paychecks |
| Federal unemployment tax (FUTA) | Most businesses with employees | Federal unemployment insurance funding |
| Excise taxes | Specific industries and products | Taxes on items such as fuel, certain equipment, and some services |
Payroll taxes deserve particular care. Income tax and FICA withheld from employees' paychecks is held in trust for the IRS. If a business fails to pay it over, the responsible owners and managers can be held personally liable through the trust fund recovery penalty.
FUTA: Federal Unemployment Tax Liability
Employers pay federal unemployment tax at 6 percent on the first $7,000 of each employee's wages each year. Most employers receive a credit of up to 5.4 percent for paying state unemployment taxes on time, which brings the effective FUTA rate down to 0.6 percent, or a maximum of $42 per employee per year.
That credit isn't guaranteed everywhere. If your state has borrowed from the federal government to pay unemployment benefits and hasn't repaid the loan, it becomes a credit reduction state, and employers there pay a higher effective FUTA rate.
FUTA is reported annually on Form 940, but deposits are made quarterly. If your accumulated FUTA liability is more than $500 at the end of a quarter, you must deposit it by the end of the following month. If it's $500 or less, it carries forward to the next quarter.
How to Reduce Your Federal Tax Liability
Use Every Deduction You're Entitled To
Contributions to retirement plans like a SEP-IRA, Solo 401(k), or employer 401(k) can reduce taxable income significantly. HSA contributions, a qualifying home office, business vehicle use, and ordinary business expenses all count too. Accurate bookkeeping throughout the year makes sure none of these get missed.
Claim the Credits You Qualify For
Credits reduce tax dollar for dollar. Depending on your situation, that may include the Child Tax Credit, the Earned Income Tax Credit, the research and development credit for businesses developing products or processes, and credits for providing employee benefits. Several clean energy credits were phased out or ended under legislation passed in 2025, so check current eligibility before counting on one.
Review Your Business Structure
For sole proprietors and single-member LLCs, all business profit is subject to self-employment tax. Once profit reaches a high enough level, typically somewhere in the low six figures, electing S corporation status can reduce self-employment tax by splitting income between a reasonable salary and distributions. The election adds payroll and compliance costs, so it's worth modeling with a CPA first.
Manage the Timing of Income and Expenses
Businesses can sometimes shift the timing of income and deductions between tax years. Delaying an invoice until January or bringing forward a planned equipment purchase into December can move taxable income from one year to the next. This works best when you expect your tax rate to change between years.
Offset Gains With Losses
If you've sold investments at a gain, selling others that have lost value can offset that gain. Up to $3,000 of net capital losses can also offset ordinary income each year, with any excess carried forward.
Pay Enough During the Year
Paying more during the year doesn't lower your liability, but it does prevent underpayment penalties. You'll generally avoid them if your withholding and estimated payments cover at least 90 percent of this year's tax or 100 percent of last year's, rising to 110 percent if your prior-year adjusted gross income was above $150,000.
Conclusion
Your federal tax liability is the real measure of what you owe the IRS, not the balance due at filing or the refund you receive. It's built from your income, reduced by deductions and credits, and increased by taxes like self-employment and payroll taxes. The businesses that manage it well don't wait for tax season. They track profit as the year goes, make accurate estimated payments, review their structure, and use every deduction and credit available, so the number on the return is one they already expected.
We were surprised when our federal tax liability came in nearly $20,000 higher than expected because we hadn't planned for several deductions and estimated payments during the year. Profitjets reviewed our business expenses, identified deductions and credits we could properly claim, and set up quarterly tax projections and estimated payments so we could plan for the liability throughout the year instead of discovering it at filing.
Book a free consultation and we will calculate the full position.
Frequently Asked Questions
What's the difference between tax liability and taxes owed?
Tax liability is your total federal tax for the year after deductions and credits. Taxes owed is what remains after subtracting payments you've already made through withholding or estimated taxes. If your payments were greater than your liability, you receive a refund instead.
Can my federal tax liability be zero?
Yes. If deductions reduce your taxable income to zero, or credits fully offset the tax on it, your federal income tax liability can be zero. You may still owe other federal taxes, such as self-employment tax on business earnings or FICA taxes on wages.
What happens if I don't pay my federal tax liability on time?
The IRS charges a failure-to-pay penalty of 0.5 percent of the unpaid tax per month, up to 25 percent, plus interest that's set quarterly. Filing late adds a separate failure-to-file penalty of 5 percent per month, also up to 25 percent. If you can't pay in full, file on time anyway and look into an IRS payment plan to limit the penalties.
Do business owners need to make estimated tax payments?
Usually, yes. Because no tax is withheld from business profit, most self-employed individuals who expect to owe $1,000 or more for the year need to make quarterly estimated payments. Corporations generally must make estimated payments if they expect to owe $500 or more.
Does a tax refund mean I lowered my tax liability?
No. A refund only means you paid more during the year than your liability turned out to be. Your liability is lowered through deductions, credits, and planning, not by how much you pay in advance.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want to Know What You Owe?
Book a free consultation and we will calculate the full position.