
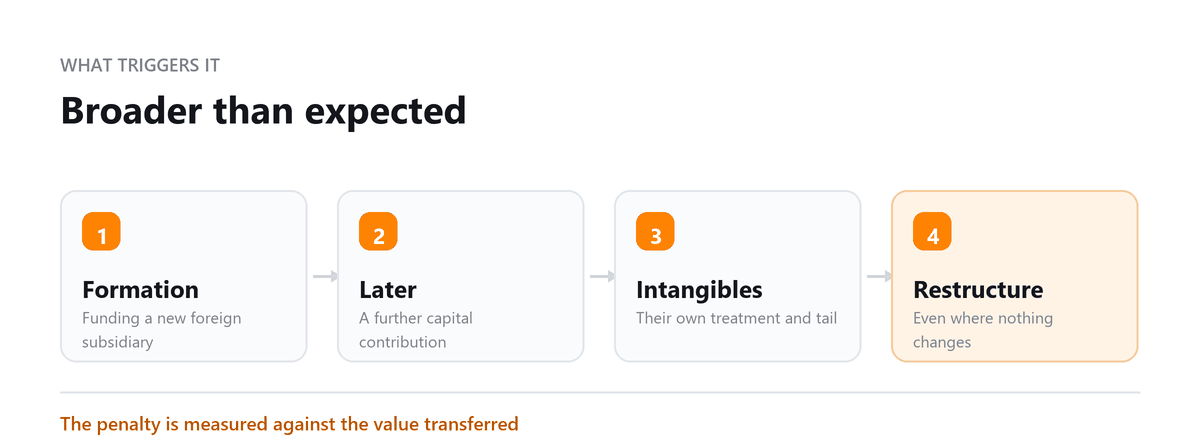
A US founder sets up a company abroad to be closer to customers and moves some money, equipment, and the software the business depends on into the new entity. A US business funds a subsidiary in another country with a large cash injection.
Or a family puts property into a foreign holding company as part of an estate plan. In each case, the focus is on the business or family goal. The US tax reporting that comes with moving property into a foreign corporation is easy to miss.
Form 926, Return by a U.S. Transferor of Property to a Foreign Corporation, is how those transfers are reported. It covers cash contributions above certain thresholds and transfers of other property in exchanges that would normally be tax-free between US companies, such as forming or capitalizing a corporation.
Behind the form sit the outbound transfer rules of Section 367, which can require you to recognize gain on appreciated property, and treat transferred intangible property as if it were sold for ongoing royalty payments.
Missing the form is expensive. The penalty is generally 10 percent of the value of the property transferred, and the statute of limitations can stay open until the information is filed. Because the reporting depends on the value of what was transferred, and valuation drives both the tax and the penalty, the time to get it right is when the transfer is planned, not when the return is being prepared.
This guide explains who has to file Form 926, which transfers are reportable, how the Section 367 outbound transfer rules affect tangible and intangible property, when and how to file, and the penalties for failing to file.
What is Form 926?
Form 926 is an information return filed by a US person who transfers property to a foreign corporation in certain exchanges. It reports who made the transfer, the foreign corporation that received it, the type and value of the property, the transferor's ownership before and after, and how any gain or special income inclusion was treated.
The requirement comes from Section 6038B. Form 926 is filed with the transferor's income tax return for the year of the transfer.
Who Must File Form 926?
A U.S. person (citizen, resident, corporation, partnership, estate, or trust) who transfers property to a foreign corporation must file Form 926 if:
- They owned 10% or more of the stock of the foreign corporation immediately after the transfer, OR
- The value of the property transferred by the U.S. person (or related persons) exceeded $100,000 during the tax year
Note: The $100,000 threshold is measured across all transfers to the same foreign corporation during the year, not per-transfer.
When Is Form 926 Due?
Form 926 doesn't have a deadline of its own. You attach it to your US income tax return for the tax year that includes the date of the transfer, and it's due when that return is due, including extensions.
The deadline you meet therefore depends on who made the transfer and which return they file:
| Transferor | Return Form 926 Is Attached To | Calendar-Year Due Date | Extended Due Date |
|---|---|---|---|
| Individual | Form 1040 or 1040-NR | April 15 | October 15 |
| C corporation | Form 1120 | April 15 | October 15 |
| Estate or trust | Form 1041 | April 15 | September 30 |
| Partner in a partnership that made the transfer | The partner's own return | Based on the partner's return | Based on the partner's return |
When a due date falls on a weekend or legal holiday, it moves to the next business day.
A calendar-year individual who transferred property to a foreign corporation during 2025 files Form 926 with their 2025 Form 1040. That return was due April 15, 2026, or October 15, 2026 if an extension was filed.
Some sources say Form 926 must be filed within 30 days of the transfer. That's not correct. What matters is the tax year the transfer falls in and the due date of the return for that year.
Timing Points to Keep in Mind
An extension covers Form 926 too. A valid extension for your income tax return extends the time to file Form 926 attached to it.
Gain recognition agreements must be filed on time. If you're deferring gain on a transfer of stock or securities, the agreement generally has to be filed with a timely filed return, including extensions. Missing that deadline can make the full gain taxable.
Late filing still helps. If a Form 926 was missed for an earlier year, filing it as soon as possible, generally with an amended return, starts the statute of limitations running and supports a reasonable cause request against the penalty.
The most important valuation issue on Form 926 is usually intangible property. Founders move code, customer relationships, or a brand into a new foreign subsidiary and record it at cost, which is often close to zero.
But the outbound transfer rules and the penalty are both based on fair market value on the date of transfer, and intangibles transferred to a foreign corporation are generally treated as producing annual income back in the US over their useful life.
A value that looks conservative on day one can mean years of understated income and a much larger penalty base if the IRS disagrees.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat Property Must Be Reported?
| Property Type | Reported on Form 926? |
|---|---|
| Cash | YES, if total transfers exceed $100,000 threshold |
| Tangible property (equipment, inventory) | YES |
| Intangible property (patents, trade secrets, goodwill) | YES, and gain recognition rules apply even if no gain recognised at transfer |
| Stock of another corporation | YES, subject to specific gain recognition rules |
| Services | Generally not a Form 926 transfer, but value of services may need to be reported elsewhere |
Penalty for Failure to File
If you fail to file Form 926, or file an incomplete or incorrect form, the penalty is generally 10 percent of the fair market value of the property at the time of the transfer. The penalty is capped at $100,000 per transfer, unless the failure was due to intentional disregard, in which case there's no cap. The penalty doesn't apply if the failure was due to reasonable cause and not willful neglect.
Gain Recognition
For transfers of stock or securities that would otherwise qualify for a gain recognition agreement, failing to meet the reporting requirements can cause the transfer to be treated as fully taxable.
An Open Statute of Limitations
When required Form 926 information isn't provided, the statute of limitations for assessing tax on that return generally stays open until it is. If the failure was due to reasonable cause, the extension is limited to the items related to the transfer.
When and Where to File Form 926
Form 926 is attached to your US income tax return for the tax year that includes the date of the transfer, and it's due by that return's due date, including extensions. That could be Form 1040, Form 1120, or another return depending on who made the transfer.
If a transfer took place in 2025 and you're a calendar-year individual, Form 926 is due with your 2025 Form 1040, including any extension you've filed.
If the transfer is part of a series of related transfers, or if a gain recognition agreement is involved, the regulations may require additional statements. Review the current instructions for the specific transaction.
How to Complete Form 926
Form 926 is organized around a few key areas.
Transferor information. The transferor's name, identifying number, and, where the transferor is a partnership or other flow-through entity, information about the partners or owners.
Transferee foreign corporation information. The foreign corporation's name, address, country of incorporation, and identifying number if it has one, along with whether it's a controlled foreign corporation.
Property transferred. Details of each category of property, including cash, stock and securities, tangible property, and intangible property, with dates, descriptions, fair market values, adjusted basis, and any gain recognized.
Additional information. The transferor's ownership percentage before and after the transfer, whether any intangible property is subject to Section 367(d), and whether gain recognition agreements or other elections apply.
Form layouts change from time to time, so work from the most recent revision of Form 926 and its instructions.
Practical Planning Tips
Value the property before the transfer. Document fair market value on the transfer date, especially for intangible property, and keep the valuation with your tax records.
Track cash contributions over 12 months. Keep a running record of cash sent to each foreign corporation, including amounts from related persons, so you know when the $100,000 test is met.
Plan gain recognition agreements in advance. They must be filed on time with the return, and they carry ongoing obligations, so decide whether to use one before the transfer closes.
Coordinate with other international filings. A transfer to a foreign corporation often comes with Form 5471 for the foreign corporation, Form 8938 or an FBAR for foreign accounts, and transfer pricing documentation for payments between the companies.
Keep basis records. Your basis in the foreign corporation's stock depends on what you transferred and any gain recognized, which affects the tax result when you eventually sell or receive distributions.
Book a free consultation before the transfer is made.
FAQs
When is Form 926 due?
Form 926 is due with your US income tax return for the tax year that includes the date of the transfer, including extensions. For a calendar-year individual who made a transfer in 2025, that means filing it with the 2025 Form 1040. There's no separate deadline measured from the date of the transfer.
Do I have to file Form 926 for a cash contribution to a foreign company?
Only if you own at least 10 percent of the foreign corporation immediately after the transfer, or if you and related persons transferred more than $100,000 in cash to that corporation during the 12 months ending on the date of the transfer. If neither test is met, the cash transfer generally isn't reportable on Form 926.
What is the penalty for not filing Form 926?
The penalty is generally 10 percent of the fair market value of the property transferred, capped at $100,000 per transfer unless the failure was due to intentional disregard. It doesn't apply if you can show reasonable cause. The statute of limitations for the related tax can also remain open until the required information is filed.
Does transferring intellectual property to a foreign subsidiary trigger tax?
Usually, yes. Under Section 367(d), a US person who transfers intangible property to a foreign corporation is generally treated as receiving annual payments tied to the property's use, and must include those amounts in income each year over its useful life. Since 2018, goodwill and going concern value are included in these rules.
Can I avoid recognizing gain when transferring property to a foreign corporation?
It depends on the property. Gain on most appreciated tangible property transferred to a foreign corporation must now be recognized, since the former active trade or business exception was repealed for transfers after 2017. Transfers of stock or securities may qualify for deferral with a properly filed gain recognition agreement. Intangible property is generally covered by Section 367(d) rather than immediate gain recognition.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Funding a Foreign Subsidiary?
Book a free consultation before the transfer is made.