
Definitions
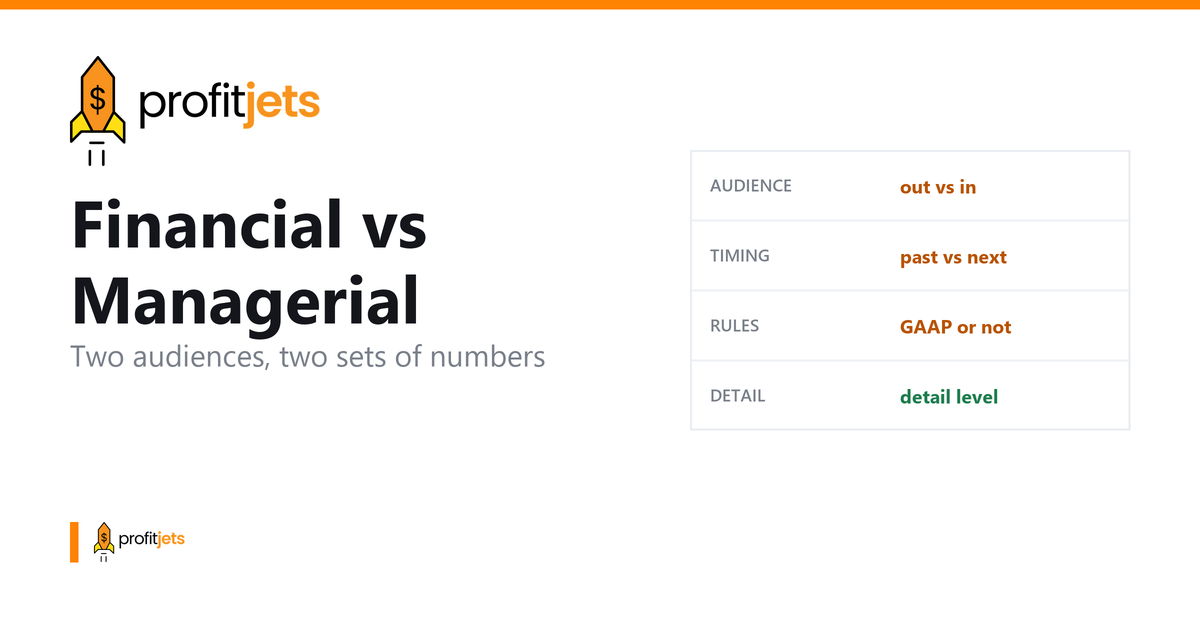
Financial accounting is the logbook of a business's past, the systematic process of recording, classifying, and reporting financial transactions in a standardised format for external stakeholders. Its outputs are the income statement, balance sheet, and cash flow statement: structured, GAAP-compliant documents that communicate a company's financial performance and position to investors, lenders, regulators, and tax authorities. Financial accounting is governed by strict standards precisely because its audience includes parties outside the business who rely on comparable, auditable information.
Managerial accounting, by contrast, is the navigation system for the future. Rather than reporting what has already happened to external parties, it analyses financial and operational data to help internal management make better decisions going forward. It has no mandatory regulatory framework, businesses design their own managerial accounting reports based on what information their leadership actually needs to allocate resources, manage costs, and plan for growth.
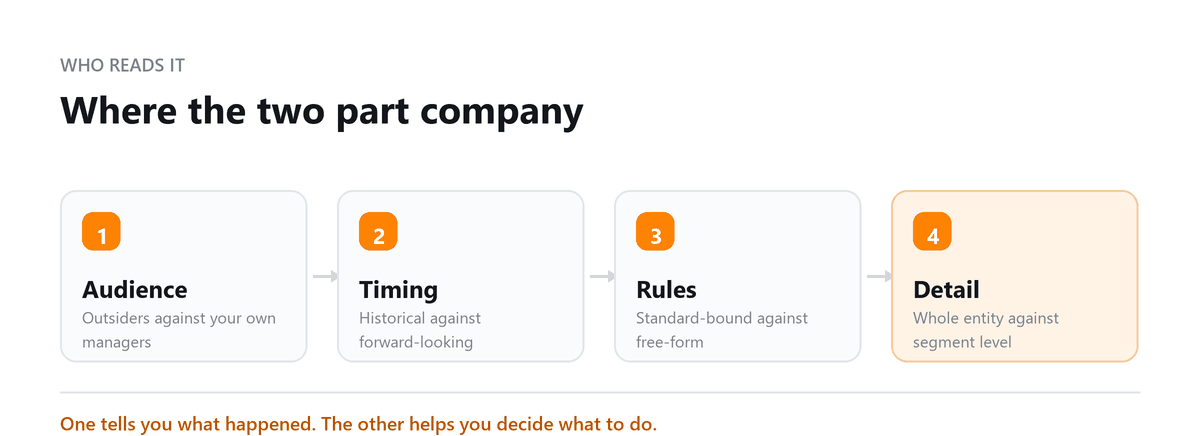
Financial accounting tells you what happened. Managerial accounting helps you decide what to do next. Businesses that master both, using historical data to inform forward-looking decisions, consistently outperform those that treat accounting as a rear-view mirror.
Ankit Sarawagi, CPA, CA, MBA · LinkedInImportance of Each
Financial Accounting
Financial accounting ensures that a business maintains the transparency, compliance, and communication standards that external stakeholders require. Without accurate financial accounting, a business cannot file taxes correctly, cannot satisfy lender reporting covenants, cannot attract equity investors, and cannot demonstrate to regulators that it is operating within applicable rules. The standardised format of financial accounting also enables benchmarking: investors and analysts can compare financial statements across companies and industries because the underlying rules are consistent.
Managerial Accounting
Managerial accounting enables better internal decisions by translating financial data into operational insights. It helps management understand which products or services are most profitable, which cost centres are consuming resources disproportionately, how actual performance compares to budget, and what the financial implications of a proposed strategic decision might be. Where financial accounting answers 'what happened?', managerial accounting answers 'what should we do next?'
Similarities
Despite their different purposes, financial and managerial accounting share a common foundation. Both rely on the same underlying financial data, transactions recorded in the general ledger. Both influence business decisions, even if financial accounting does so indirectly through investor and lender behaviour. And both apply core accounting principles: the concept of matching revenues and expenses, the distinction between assets and liabilities, and the importance of accurate, consistent data as the basis for any analysis.
Examples
Consider a bakery evaluating whether to open a second location. The financial accountant's role is to produce the historical financial statements that show the first location's actual revenue, cost structure, and profit over the past three years, the record of what happened. The managerial accountant's role is to build a forward-looking analysis: projected costs for the new location, break-even analysis, cash flow forecast for the first 18 months, and a comparison of the expected return against the capital required.
Both functions are essential, the historical record informs the forecast, and the forecast guides the decision.
Advantages
Financial Accounting Advantages
Financial accounting builds investor and lender confidence by providing an independently verifiable, standards-compliant record of performance. It ensures regulatory compliance across tax filings, SEC reporting (for public companies), and lender covenant reporting. It standardises financial communication, because financial statements follow consistent rules, stakeholders across different industries and geographies can evaluate them with confidence.
Managerial Accounting Advantages
Managerial accounting enhances decision-making speed by providing management with the specific analyses needed for each decision, without the constraints of a standardised reporting format. It improves operational efficiency by identifying where costs are exceeding budget and which activities are consuming resources without generating proportionate returns. It supports strategic planning by enabling scenario modelling, sensitivity analysis, and forward-looking projections that are impossible using historical financial statements alone.
Differences
| Factor | Financial Accounting | Managerial Accounting |
|---|---|---|
| Focus | Historical (past) | Forward-looking (future) |
| Audience | External (investors, regulators) | Internal (management, leadership) |
| Regulations | Strict GAAP/IFRS | Flexible, no mandatory standards |
| Reporting frequency | Quarterly/Annual | As needed (daily to monthly) |
| Format | Standardized statements | Custom reports, dashboards |
Which is Harder?
Both financial and managerial accounting require a strong foundation in accounting principles, and both present distinct challenges. Financial accounting demands compliance rigor: the practitioner must know the applicable rules, apply them consistently, and ensure the output can withstand audit scrutiny. A single misclassification or disclosure omission can create material compliance exposure. Managerial accounting demands strategic thinking and business judgment: the practitioner must understand not just the numbers but the business context well enough to design analyses that actually improve decisions.
Neither is inherently harder, they require different skill sets applied to different problems.
The Intersection
In practice, financial and managerial accounting are not independent functions, they feed each other. The financial statements produced through financial accounting provide the data inputs for managerial forecasting and analysis. A well-maintained set of GAAP-compliant books makes it far easier to build accurate managerial models, because the underlying data is reliable and consistently classified. Businesses that invest in both, rigorous financial accounting for compliance and transparency, and disciplined managerial accounting for strategic decisions, consistently outperform those that treat accounting as a pure compliance function.
How Profitjets Supports Both
Profitjets delivers both financial and managerial accounting capabilities for growing businesses. Our bookkeeping and accounting teams maintain GAAP-compliant financial records and deliver monthly financial statements for compliance and investor reporting. Our virtual CFO services build on that financial foundation to provide the forward-looking analyses, cash flow forecasts, budget-vs-actual reviews, scenario models, that managerial accounting requires. For businesses that need both functions but are not ready to hire a full accounting team, Profitjets provides integrated support at a fraction of the in-house cost.
Conclusion
Financial accounting and managerial accounting serve complementary purposes that every business needs. Financial accounting provides the standardised, auditable record of performance that external stakeholders require for trust and compliance. Managerial accounting translates that historical record into forward-looking analyses that drive better internal decisions. Neither function can substitute for the other: a business with excellent financial accounting but no managerial analysis is compliant but strategically blind; a business with sophisticated managerial models but poor financial accounting is building forecasts on unreliable data.
The most effective finance functions integrate both disciplines into a coherent system.
Book a free consultation and we will cover compliance and decision reporting.
Frequently Asked Questions
Is managerial accounting required by law?
No, unlike financial accounting, managerial accounting has no mandatory regulatory framework. Businesses choose their own methods, formats, and frequency based on what helps management make better decisions. The flexibility is both a strength and a challenge.
Can a small business skip managerial accounting?
Technically yes, but it's a competitive disadvantage. Without managerial accounting, you cannot easily track which products are most profitable, which cost centres are over-spending, or whether you're on track to hit your revenue targets. Even simple budget-vs-actual reports add significant value.
What qualifications do financial accountants vs managerial accountants typically hold?
Financial accountants often hold CPA credentials, given the compliance and audit requirements. Managerial accountants frequently pursue CMA (Certified Management Accountant) certification, which focuses on financial analysis, strategy, and decision support.
How does managerial accounting help with pricing decisions?
Managerial accounting uses cost analysis to determine the true cost of producing a product or delivering a service, including direct materials, labour, and overhead allocation. This allows you to set prices that cover costs and generate the desired margin.
What reports does managerial accounting produce?
Common outputs include budget-vs-actual variance reports, product profitability analyses, customer segment P&Ls, departmental cost reports, cash flow forecasts, and break-even analyses. None of these are required by GAAP, they exist purely to improve internal decisions.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Both Sets Produced?
Book a free consultation and we will cover compliance and decision reporting.