
Small business owners get a monthly report from their bookkeeper and rarely have any interest in actually reading it. The numbers are there - but it arrives three weeks late, it looks different every month, and it fails to answer the questions of value to the owner such as: did we make money, where did the money go, and can we afford the things we want to do in the coming quarter?
What's the solution to this? Probably not more reports. The issue is that reporting doesn't support decision making.
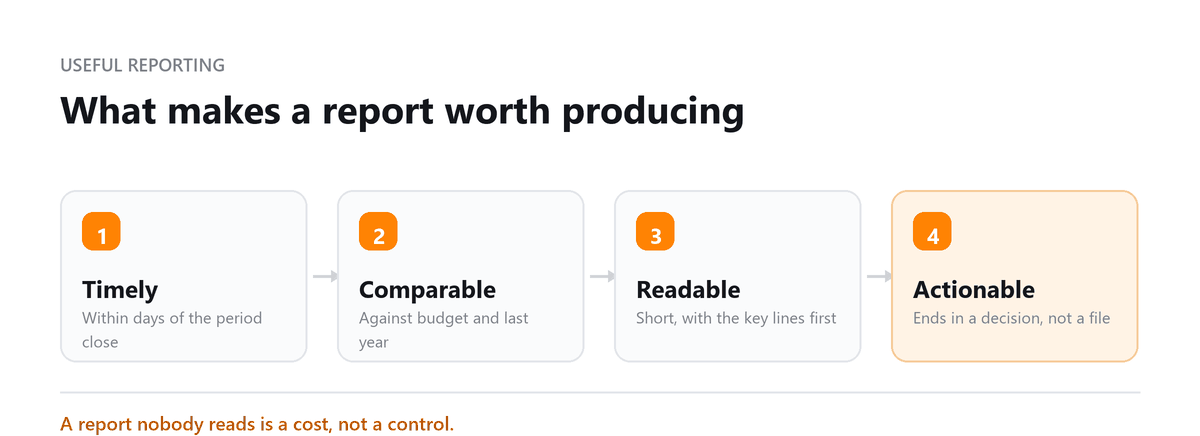
Smart financial reporting means providing accurate information on a timely, consistent basis in a standard format with the most important metrics near the top. It means comparing the results to a budget and to last month, not just looking at one month in isolation, so that you can understand trends and changes.
The good news is that smarter financial reporting doesn't require a finance team or fancy software.
It's a matter of establishing certain financial reporting habits including closing the books promptly each month, keeping good records throughout the month, focusing on the most important financial metrics, and taking the time to understand what the reports are saying.
Expert Perspective
The single biggest improvement most small businesses can make to their reporting is speed. A report that shows up on the 25th of the following month is a history lesson, not a management tool. They catch margin problems, overspending, and slow-paying customers while there's still time to act. Fancy dashboards help, but a timely, consistent report that someone actually reads does more.
Ankit Sarawagi, CPA, CA, MBA · LinkedInThis guide covers five practical tips for improving financial reporting in a small business: closing the books on time, keeping reports consistent, tracking the right metrics, comparing results with budgets and prior periods, and building a regular review routine, along with common reporting mistakes and when to get outside help.
Why Should More Small Businesses Consider Smart Financial Reporting?
For most small business owners, financial reporting means getting the books to the accountant once a year. That approach treats reporting as a compliance event rather than a management tool, and it leaves enormous value on the table. Smart financial reporting recasts the activity entirely: instead of a backward-looking tax exercise, it becomes a GPS for the business.
Done consistently, it tells you exactly where cash is coming from and where it is going, whether revenue growth is outpacing cost growth, which months are structurally profitable versus which rely on seasonal spikes, and whether the business is on track to hit its annual targets. For small businesses navigating growth, cash flow pressure, or competitive markets, that ongoing clarity is a genuine competitive advantage.
Beyond Basic Bookkeeping, How to Optimize Reporting
Bookkeeping and reporting are related but distinct activities. Bookkeeping records financial transactions, invoices sent, bills paid, payroll processed, bank transactions categorised. Reporting analyses those transactions and transforms them into structured insights: trend lines, variance analyses, margin calculations, and forward-looking projections. The distinction matters because many small businesses invest in bookkeeping but stop short of the reporting layer that makes the bookkeeping data actually useful.
Cloud-based accounting tools and dashboard software now make it practical for businesses of any size to bridge this gap, automatically pulling categorised transaction data into formatted reports and visualisations without manual intervention.
How to Optimize Financial Reporting for Growth
Three structural practices separate businesses with strong financial reporting from those with good-enough bookkeeping. First, rolling cash flow forecasts, updated monthly using actual data from the prior period, provide a forward-looking view of cash availability that historical statements cannot. Second, cloud security infrastructure ensures financial data is protected, backed up, and accessible to authorised users from any location, reducing the operational fragility of storing financial records on local machines.
Third, standardising the chart of accounts and reporting framework across all periods ensures that every report produced is directly comparable to every prior report, enabling trend analysis that is impossible when categories shift between periods.
5 Key Tips for Smart Financial Reporting
Tip 1: Embrace Cloud-Based Accounting
Cloud accounting platforms, including QuickBooks Online, Xero, and Zoho Books, provide real-time access to financial data from any device, automatic bank feed integration that eliminates manual transaction entry, and bank-level encryption for data security. For small businesses, the shift from desktop accounting software or spreadsheets to cloud platforms reduces the time spent on data entry, ensures records are always current, and enables the accountant and business owner to work from the same live data rather than exchanging files.
Most cloud platforms also integrate directly with payroll, inventory, and payment processing tools, further reducing manual reconciliation work.
Tip 2: Standardize Financial Reporting
A standardised chart of accounts, the master list of categories used to classify every transaction, is the foundation of comparable financial reporting. When every expense is categorised consistently using the same account codes from month to month, the resulting reports are directly comparable across periods, making trend analysis reliable. Without standardisation, a cost that appears in 'Marketing' one month and 'Advertising' the next creates noise that obscures real performance changes.
Establishing and enforcing a consistent chart of accounts from the outset is one of the highest-leverage investments a small business can make in its reporting infrastructure.
Tip 3: Track Cash Flow, Not Just Profits
Many small businesses focus exclusively on the income statement, and run into cash flow crises while showing solid profitability on paper. This happens because accrual accounting recognises revenue when it is earned, not when cash is received. A business with $50,000 in outstanding receivables may show healthy income statement profit while the bank account is depleted. Tracking cash flow separately, using a dedicated cash flow statement and a rolling 13-week cash forecast, provides the liquidity visibility that the income statement cannot.
This distinction is especially important for businesses with extended payment terms, seasonal revenue patterns, or significant upfront costs.
Tip 4: Automate KPI Dashboards
KPI dashboards translate financial data into the specific metrics that matter for decision-making. Tools like Fathom, LivePlan, and Power BI connect directly to cloud accounting software and automatically refresh visualisations of key metrics, gross margin percentage, accounts receivable days outstanding, operating cash flow, revenue per employee, on a monthly or weekly basis. Automated dashboards eliminate the manual work of producing management reports and ensure that the right metrics reach the right people at the right cadence.
They also enable benchmarking against industry averages, making it easier to identify where the business performs above or below its peers.
Tip 5: Go Beyond Bookkeeping with Expert Guidance
At a certain scale, typically $1M+ in revenue, or when facing a fundraise, acquisition, or significant strategic decision, standard bookkeeping and basic reporting are insufficient. A virtual CFO provides the strategic layer that bookkeeping alone cannot: scenario modelling (what happens to cash flow if revenue drops 20%?), capital structure analysis, investor reporting, and forward-looking financial planning.
Virtual CFO services give growing small businesses access to senior financial expertise at a fraction of the cost of a full-time CFO hire, typically through a monthly retainer that scales with the complexity of the business.
Additional Tips
Beyond the five core tips, four additional practices strengthen small business financial reporting. Automate invoicing and payment collection to reduce receivables days and improve cash flow predictability. Implement cybersecurity measures and regular backups for financial data, cloud accounting platforms provide built-in protection, but businesses should also maintain backup processes for critical documents. Conduct quarterly scenario planning using actual financial data to model different revenue and expense trajectories. And schedule periodic CPA reviews, even if you outsource day-to-day bookkeeping, to ensure tax compliance, catch classification errors, and get strategic financial advice.
Financial Reporting Software Comparison
| Tool | Best For | Key Feature |
|---|---|---|
| QuickBooks Online | Small businesses | Automated bank feeds & reconciliation |
| Xero | Growing businesses | Multi-user access & Hubdoc integration |
| Zoho Books | Budget-conscious SMBs | Full suite with payroll |
| Fathom | KPI reporting | Visual dashboard & benchmarking |
| Power BI | Custom analytics | Advanced data modelling |
Profitjets by the Numbers
Profitjets clients using structured financial dashboards and reporting have saved an average of 6 to 10 hours per month on manual reporting and financial reviews, giving leadership more time to focus on business decisions.
In Practice“Before Profitjets, I was relying on spreadsheets and pulling numbers from different systems whenever I needed to make a financial decision. With our cloud-based dashboards and regular CFO reporting, I can now see cash flow, profitability, and key performance trends in one place, which makes it much easier to decide when to hire, invest, or adjust spending.”
Conclusion
Smart financial reporting is not about adding complexity, it is about making the financial data you are already generating work harder for your business. Cloud accounting tools, standardised frameworks, cash flow tracking, automated dashboards, and expert guidance turn raw transaction records into a genuine management intelligence system. Small businesses that invest in this infrastructure consistently make faster decisions, avoid cash flow surprises, and present a more credible financial picture to lenders and investors.
The five tips in this guide provide a practical roadmap for building that capability at any stage of business growth.
Book a free consultation and we will build the pack around your decisions.
Frequently Asked Questions
What makes financial reporting "smart" for a small business?
Smart financial reporting is accurate, timely, consistent, and focused on decisions. That means closing the books promptly each month, using the same format and accounting methods every period, highlighting the few metrics that matter most, and comparing results with a budget and past performance so trends and problems are easy to spot.
How quickly should a small business close its books each month?
A good target for most small businesses is within about ten business days after month-end. Reports prepared much later lose much of their value, because problems they reveal have had more time to grow. Keeping transactions categorized and accounts reconciled during the month makes a faster close much easier.
Which financial metrics should small business owners track?
It depends on the business, but most owners benefit from tracking revenue, gross margin, net profit, cash balance, accounts receivable aging, and a comparison of actual results with budget. Businesses with inventory should add inventory turnover, and service businesses often track utilization or revenue per employee. A short list you review consistently is more useful than dozens of figures you ignore.
Why compare financial reports with a budget and prior periods?
A single month's numbers don't show whether results are good or bad. Comparing them with your budget shows whether the business is performing as planned, and comparing them with the same period last year shows trends while accounting for seasonality. Together, these comparisons point you to the areas that need attention.
When should a small business get help with financial reporting?
Consider outside help when reports are regularly late, the books need frequent corrections, you're preparing for financing or investment, or you don't have the time or confidence to interpret the numbers. An outsourced bookkeeper or accountant can take over the monthly close and reporting, and a fractional CFO can help turn those reports into forecasts and strategy.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Reports You Will Actually Use?
Book a free consultation and we will build the pack around your decisions.