
Corporate filing dates are not a single date. They depend on the entity's year end, on whether an extension was requested, and on the state as well as the federal position.
The consequences of missing a filing and of missing a payment are separate, and they are not equally severe. That distinction matters most to the businesses under the most pressure, which are exactly the ones that tend to delay both together.
This covers how the dates are determined, how extensions change them, how the two kinds of consequence differ, and what to do when a date has already passed.
Missing a Form 1120 deadline or making late estimated tax payments costs corporations real money. This guide covers every calendar-year and fiscal-year deadline for C-corporation federal income tax, extension mechanics, estimated tax payment schedules, and the penalty structure for non-compliance.
Filing Deadlines
Calendar-Year Corporations
Calendar-year C-corporations (fiscal year ending December 31) must file Form 1120 by April 15 of the following year. If April 15 falls on a Saturday, Sunday, or legal holiday, the deadline shifts to the next business day.
| Tax Year End | Form 1120 Due Date |
|---|---|
| December 31, 2025 | April 15, 2026 |
| December 31, 2024 | April 15, 2025 |
Fiscal-Year Corporations
For corporations with a fiscal year other than December 31, the return is due by the 15th day of the fourth month after the close of the fiscal year.
| Fiscal Year End | Form 1120 Due Date |
|---|---|
| March 31 | July 15 |
| June 30 | October 15 |
| September 30 | January 15 (of the following calendar year) |
| Any other month-end | 15th day of the 4th month after fiscal year end |
Where a business cannot pay, the instinct is to delay the return as well. That is usually the more expensive choice, because the consequences of not filing and of not paying are separate and the first is generally harsher. File, pay what you can, then deal with the balance.
Ankit Sarawagi, CPA, CA, MBA · LinkedInAutomatic 6-Month Extension (Form 7004)
A C-corporation can automatically extend its filing deadline by 6 months by filing Form 7004 by the original due date. No IRS approval is required, the extension is automatic upon timely filing of Form 7004.
- Calendar-year: Extended deadline is October 15
- Fiscal-year: Extended deadline is 6 months after the original due date
- CRITICAL: An extension to FILE is NOT an extension to PAY. Taxes owed are still due on the original deadline.
Pro Tip: Always file Form 7004 even if you expect a refund. It gives you time to gather all K-1s and year-end information without rushing, and the risk of a late-filing penalty is zero once you file the extension.
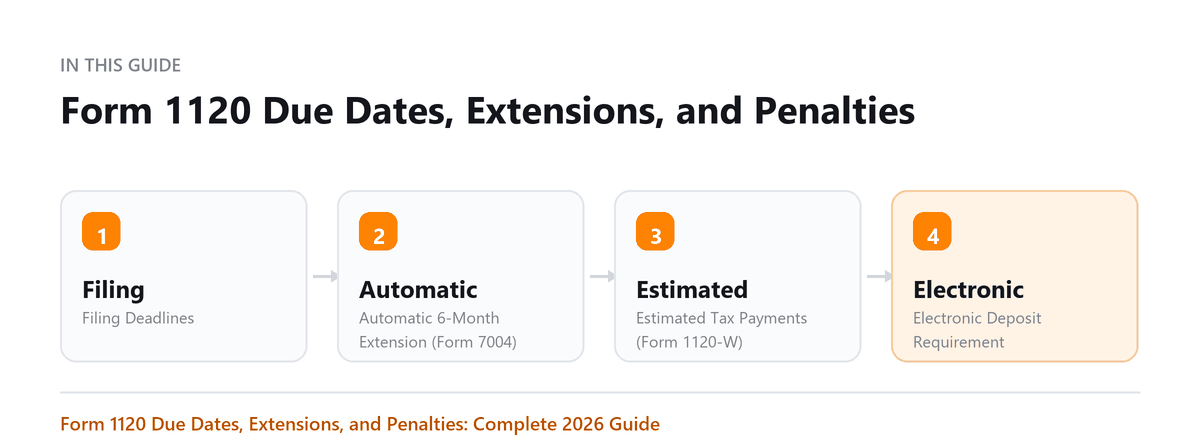
Estimated Tax Payments (Form 1120-W)
Corporations that expect to owe $500 or more in federal income tax must make quarterly estimated tax payments. These are due on the 15th day of the 4th, 6th, 9th, and 12th months of the corporation's fiscal year.
Calendar-Year Estimated Tax Due Dates
| Installment | Due Date |
|---|---|
| 1st installment (25%) | April 15 |
| 2nd installment (25%) | June 15 |
| 3rd installment (25%) | September 15 |
| 4th installment (25%) | December 15 |
Large Corporation Accelerated Payment Rules
Corporations with taxable income of $1 million or more in any of the three preceding tax years ('large corporations') cannot use the prior-year safe harbor for any installment other than the first. They must base payments on current-year income.
Safe Harbor Methods
A corporation avoids the underpayment penalty if it pays:
- 100% of the current year's tax liability (paid in four equal installments), OR
- 100% of the prior year's tax liability (only available for non-large corporations)
Electronic Deposit Requirement
All corporate tax deposits, including estimated tax payments and the balance due with the return, must be made through the Electronic Federal Tax Payment System (EFTPS). Checks mailed to the IRS are no longer accepted for corporations.
Penalty Structure
Late Filing Penalty
| Situation | Penalty |
|---|---|
| Return filed late, tax was owed | 5% of unpaid tax per month (or fraction of a month), up to 25% maximum |
| Return filed 60+ days late | Minimum penalty: the lesser of $510 or 100% of the unpaid tax (whichever is smaller), whichever is smaller |
| Return filed on time, no tax owed | No late-filing penalty |
Late Payment Penalty
| Situation | Penalty |
|---|---|
| Tax paid late | 0.5% of unpaid tax per month (or fraction of a month), up to 25% maximum |
| During active IRS installment agreement | 0.25% per month (reduced rate) |
Interest on Underpayments
In addition to penalties, interest accrues on any unpaid tax from the original due date to the payment date. The interest rate is the federal short-term rate plus 3 percentage points, adjusted quarterly.
Penalty Abatement
Corporations can request penalty abatement for:
- First-time penalty abatement (FTA): Available if no penalties in the preceding three years
- Reasonable cause: Circumstances beyond the corporation's control (e.g., key officer illness, natural disaster, reliance on erroneous tax advice)
- Statutory exceptions: Certain tax treaties or specific IRS guidance
Book a free consultation and we will take the return off your desk.
Frequently Asked Questions
What if we file the extension but still don't pay on time?
The late-payment penalty (0.5%/month) accrues from April 15 on the unpaid balance, even with an extension. Interest also accrues. File the extension, but pay as much as you can by April 15.
Can a corporation e-file an extension?
Yes. Form 7004 can be e-filed through authorized tax software or the IRS e-file system. It is the fastest and safest method.
How do I pay the balance due if we e-file?
Pay via EFTPS, credit card (through IRS authorized payment processors), or check with Form 1120-V payment voucher when paper filing.
Is there a penalty for underpaying estimated taxes?
Yes. The estimated tax penalty (Form 2220) applies if estimated payments are less than the required amount or are late. It is calculated based on the IRS underpayment interest rate.
What if we cannot pay the tax owed?
File the return on time (to avoid the 5% late-filing penalty) and set up an installment agreement with the IRS (Form 9465 or online through IRS.gov).

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Filing Handled?
Book a free consultation and we will take the return off your desk.