
What is a Journal Entry in Accounting?
A journal entry is the formal record of a financial transaction in a company's accounting system. Every economic event, a sale, a payment, a loan, a depreciation charge, is captured first as a journal entry before it flows anywhere else in the books. Each entry follows the double-entry format: it specifies the date, the accounts affected, the debit and credit amounts for each account, and a brief description (called a narration) explaining what occurred.
Journal entries are the DNA of an accounting system. Every line in every financial statement can be traced back to the journal entries from which it was built. Errors in journal entries propagate forward into ledgers, trial balances, and ultimately financial statements, which is why getting them right at the point of entry matters enormously.
The journal entry is the DNA of your financial records. Every mistake in profit reporting, every tax issue, every audit finding traces back to a journal entry that was wrong, or missing entirely.
Ankit Sarawagi, CPA, CA, MBA · LinkedInWhat is the Purpose of a Journal Entry?
Journal entries serve four essential functions in an accounting system:
- Chronological record: They create a time-stamped log of every transaction, making it possible to reconstruct the financial history of any period.
- Account balance updates: Each entry updates the balances of the affected accounts, maintaining the accuracy of the general ledger.
- Financial statement foundation: The ledger balances produced by journal entries are the raw material from which financial statements are built.
- Error detection: The requirement that every entry must balance (debits = credits) provides a continuous internal check that catches data entry mistakes before they propagate.
Types of Journal Entries
Sales Entries
Sales entries record revenue earned from the delivery of goods or services. A cash sale debits Cash and credits Sales Revenue. A credit sale debits Accounts Receivable (the customer owes you money) and credits Sales Revenue. Sales entries are among the most frequent in any revenue-generating business.
Purchase Entries
Purchase entries record the acquisition of inventory, supplies, or other assets. Buying inventory for cash debits Inventory and credits Cash. Buying on credit debits Inventory and credits Accounts Payable, reflecting the obligation to pay the supplier later.
Cash Receipt and Payment Entries
Cash receipt entries record money coming in, customer payments on account, loan proceeds, owner investment. Cash payment entries record money going out, vendor payments, rent, payroll. These entries keep the Cash account current and accurate at all times.
Adjustment Entries
Adjusting entries are made at period end to capture economic activity that occurred during the period but was not triggered by an external document. Examples include accruing wages owed to employees at month end, recording the portion of prepaid insurance that has been consumed, and charging depreciation on fixed assets. Without adjusting entries, financial statements would misrepresent the true performance of the period.
Closing Entries
Closing entries are made at the end of the accounting year to zero out all temporary accounts, revenue, expenses, and dividends drawn, by transferring their net balances to Retained Earnings. This resets the income statement accounts to zero for the new year while preserving the cumulative equity balance. After closing, only permanent accounts (assets, liabilities, equity) carry forward non-zero balances.
What is Included in a Journal Entry?
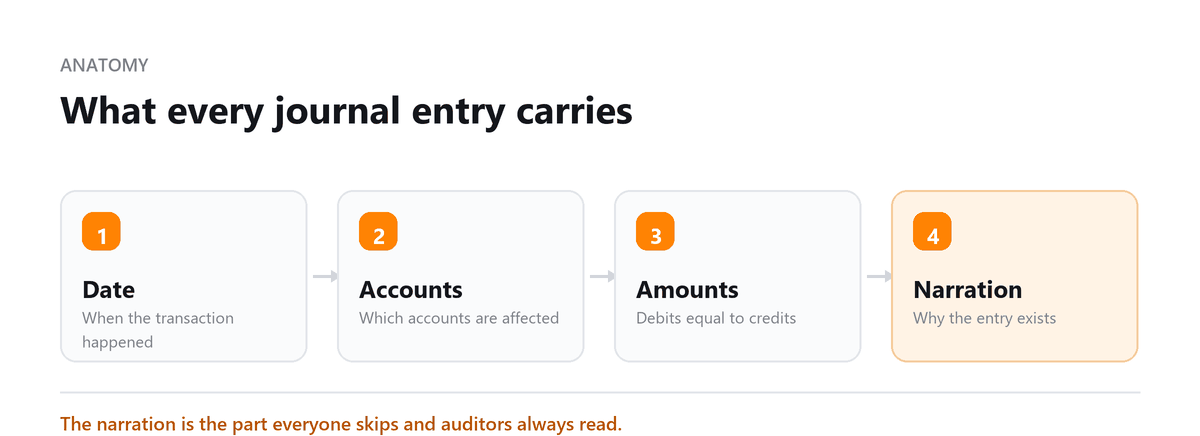
A properly formatted journal entry contains five elements:
- Date: The calendar date on which the transaction occurred.
- Account titles: The names of every account affected by the transaction.
- Debit amounts: The amount posted to the left (debit) side of each affected account.
- Credit amounts: The amount posted to the right (credit) side of each affected account.
- Description/narration: A brief explanation of what the entry records, enough context for an auditor or reviewer to understand the transaction without needing supporting documents.
How to Do Journal Entries in Accounting
Follow these six steps to record any transaction accurately:
Step 1: Identify the Transaction
Confirm that an economic event with financial impact has occurred. Gather the source document, invoice, receipt, bank statement, that evidences the transaction.
Step 2: Analyse the Account Impact
Determine which accounts are affected. Most transactions touch two accounts; complex transactions may affect three or more. Identify whether each affected account is an asset, liability, equity, revenue, or expense account.
Step 3: Choose Account Titles
Select the correct account names from your chart of accounts. Using consistent, standardized account names is critical for ledger accuracy and financial statement integrity.
Step 4: Classify as Debit or Credit
Apply the double-entry rules: assets and expenses increase with debits and decrease with credits. Liabilities, equity, and revenue increase with credits and decrease with debits. Determine which accounts are increasing and which are decreasing, then assign debits and credits accordingly.
Step 5: Record the Amount
Enter the dollar amount for each debit and credit. Verify that total debits equal total credits before saving the entry, an unbalanced entry signals an error.
Step 6: Provide a Description
Write a concise narration describing the transaction. Good narrations include the counterparty name, invoice or check number, and purpose. This detail saves significant time during audits and period-end reviews.
Journal Entry Examples
- Example 1, Merchandise Sale on Account: Debit Accounts Receivable $1,200 / Credit Sales Revenue $1,200. Narration: Sale of merchandise to ABC Corp per Invoice #1042.
- Example 2, Inventory Purchase for Cash: Debit Inventory $800 / Credit Cash $800. Narration: Purchase of raw materials from XYZ Supplier.
- Example 3, Monthly Rent Payment: Debit Rent Expense $2,500 / Credit Cash $2,500. Narration: Office rent payment for the month of December.
- Example 4, Utility Bill Accrual: Debit Utilities Expense $350 / Credit Accounts Payable $350. Narration: Accrued electricity bill for December, invoice not yet received.
Why Choose Profitjets
Profitjets accountants handle the full journal entry workflow for your business, from daily transaction recording to period-end adjusting entries, ensuring your books are accurate, compliant, and always close-ready. We eliminate the journal entry errors that lead to tax issues and financial misstatements.
Conclusion
Journal entries are the foundation of every financial record a business maintains. Getting them right, using the correct accounts, proper debit/credit classification, and clear narrations, is what separates books that hold up under scrutiny from ones that create problems at tax time or during due diligence. Whether you manage entries yourself or delegate to an outsourced team, understanding the mechanics of journal entries makes you a sharper reader of your own financial statements.
From the Profitjets Team
Book a free consultation and we will keep the journal clean and explained.
Frequently Asked Questions
Do journal entries have to be made every day?
Ideally yes for businesses with daily transactions. Modern accounting software creates journal entries automatically when you record invoices, payments, and expenses, so the manual work is minimal, but the daily discipline matters.
What's the difference between a journal entry and a ledger entry?
A journal entry records the transaction in chronological order (the journal). A ledger entry is that same information posted to the specific account it affects. The journal is the log; the ledger is the organised file.
Can journal entries be reversed?
Yes, reversing entries are a standard accounting technique. You post a reversing entry at the start of the next period to undo an accrual from the previous period, preventing double-counting.
What makes a journal entry invalid?
An unbalanced entry (debits ≠ credits), a missing account title, an incorrect date, or posting to the wrong account. Accounting software prevents unbalanced entries, but wrong account selection still requires human review.
How long should journal entry records be kept?
The IRS recommends keeping supporting records for at least 3 years (general rule) or 7 years if you underreported income significantly. Most accountants recommend 7 years as the default retention policy.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want the Entries Made Correctly?
Book a free consultation and we will keep the journal clean and explained.