
What Is a Journal in Accounting?
The journal, sometimes called the book of original entry, is the chronological record of every financial transaction a business conducts before any of that information is organized by account. Think of it as the unedited transaction log of the entire business: every sale, every purchase, every loan payment, every payroll run enters the journal first, in date order, exactly as it happened.
The journal's value lies in its completeness and its audit trail. Because every entry is timestamped and narrated, any transaction can be traced from a financial statement line item all the way back to the original source document. This traceability is what makes financial records defensible to auditors, tax authorities, and investors.
Compound journal entries are where I see the most errors in small business books. Business owners try to handle multi-leg transactions themselves and miss accounts entirely. A single missed line can misstate both the balance sheet and the income statement.
Ankit Sarawagi, CPA, CA, MBA · LinkedInComponents of a Journal Entry
Every journal entry, regardless of complexity, contains the same four elements:
- Date: The date the transaction occurred, not the date it is recorded.
- Account names: The titles of every account debited and credited, drawn from the company's chart of accounts.
- Debit/credit amounts: The monetary amount posted to each account, with debits listed first by convention.
- Narration: A brief description identifying the nature of the transaction, the counterparty, and any relevant reference numbers (invoice).
Types of Accounting Journal Entries
Simple Journal Entries
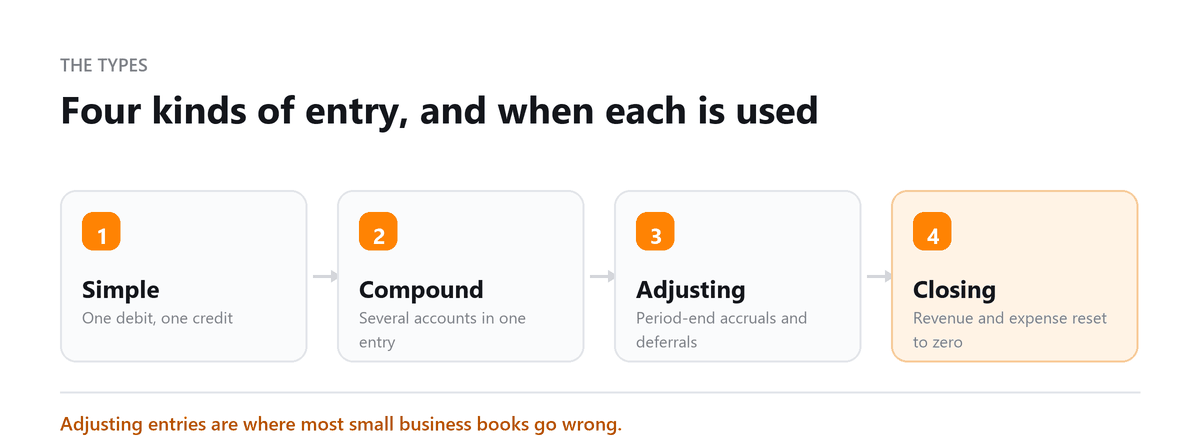
A simple journal entry involves exactly two accounts, one debited and one credited, for the same amount. This is the most common type. Example: when a business pays its monthly rent in cash, it debits Rent Expense and credits Cash for the same amount. Two accounts, perfectly balanced. Simple entries handle the vast majority of routine business transactions.
Compound Journal Entries
A compound journal entry involves three or more accounts in a single entry. They arise when a single transaction affects multiple accounts simultaneously. Example: a loan payment that includes both principal reduction and interest expense requires three accounts, Loan Payable (debit for principal), Interest Expense (debit for interest), and Cash (credit for total payment). The total debits still equal the total credit. Compound entries are more complex but are cleaner and more accurate than recording multi-leg transactions as separate simple entries.
Adjusting Journal Entries
Adjusting entries are posted at period end, monthly, quarterly, or annually, to capture economic activity that occurred during the period but was not triggered by an external document. The four categories of adjusting entries are:
- Accrued revenues: Revenue earned but not yet invoiced or received.
- Accrued expenses: Expenses incurred but not yet billed or paid (wages, utilities).
- Deferred revenues: Cash received in advance for services not yet delivered.
- Prepaid expenses: Costs paid upfront that cover future periods (insurance, rent).
Without adjusting entries, financial statements misrepresent the true performance of the period and violate the matching principle.
Closing Journal Entries
Closing entries are made at the end of the fiscal year to transfer all temporary account balances, revenues, expenses, and dividends, to Retained Earnings. This process has two effects: it zeros out the income statement accounts so they start fresh in the new year, and it rolls the net income (or loss) into the permanent equity balance on the balance sheet. After closing entries are posted, a post-closing trial balance confirms that only permanent accounts carry non-zero balances.
Journal Entry Accounting Examples for Common Transactions
Recording Sales
When a product is sold on credit: Debit Accounts Receivable (the customer owes you), Credit Sales Revenue (you earned the income). When cash is received for that sale: Debit Cash, Credit Accounts Receivable. The two-step process captures both the earning of revenue and the collection of cash separately, which is essential for accrual-basis reporting.
Paying Expenses
When an expense is incurred and paid immediately: Debit the relevant Expense account (e.g., Utilities Expense), Credit Cash. When an expense is incurred but not yet paid: Debit the Expense account, Credit Accounts Payable. When the bill is later paid: Debit Accounts Payable, Credit Cash. This two-entry sequence correctly records the liability when incurred and the cash outflow when paid.
Depreciating Assets
Each period, a portion of a long-lived asset's cost is recognized as an expense through depreciation. The entry: Debit Depreciation Expense, Credit Accumulated Depreciation. The asset's original cost stays unchanged on the balance sheet, but Accumulated Depreciation, a contra-asset account, grows each period, reducing the asset's net book value. This entry is always an adjusting entry because no external transaction triggers it.
General Journal vs Specialized Journals
Small businesses with low transaction volume can manage everything in a single general journal. Larger businesses use specialized journals to handle high-volume recurring transaction types more efficiently:
- Sales Journal: Records all credit sales.
- Purchase Journal: Records all credit purchases.
- Cash Receipts Journal: Records all cash inflows.
- Cash Disbursements Journal: Records all cash outflows.
Specialized journals allow different staff to work simultaneously on different transaction types and speed up the posting process. Only non-routine transactions that do not fit a specialized journal go into the general journal.
Why Accurate Journal Entries Matter
The entire edifice of financial reporting rests on journal entries. Inaccurate entries, wrong accounts, wrong amounts, missing narrations, incorrect dates, propagate forward into every downstream report. The consequences include:
- Regulatory non-compliance: Misstated financials can trigger IRS scrutiny and auditor qualifications.
- Financial transparency failure: Management cannot trust P&L reports built on faulty journal entries.
- Informed decision-making failures: Capital allocation, pricing, and hiring decisions made on wrong numbers carry compounding risk.
How Profitjets Can Help
Profitjets manages journal entry workflows for growing businesses, from routine daily entries and monthly adjusting entries to complex catch-up work for businesses with months of unrecorded transactions. Our accountants maintain a clean, audit-ready general ledger so that every financial statement we produce can be traced to source documents without exception.
Conclusion
Mastering journal entries means understanding not just the mechanics of debits and credits but the economic substance that each entry represents. Whether you are a business owner reviewing your books, a finance professional building your skills, or a management team evaluating the quality of your accounting function, journal entry accuracy is the starting point for everything else that matters in financial reporting.
From the Profitjets Team
Book a free consultation and we will handle the adjusting and closing entries.
Frequently Asked Questions
What is the golden rule of journal entries?
Every journal entry must balance, total debits must equal total credits. This is the foundational rule of double-entry accounting and the first thing any bookkeeper or accountant checks.
When should I use a compound journal entry instead of simple entries?
Use compound entries when a single transaction affects more than two accounts simultaneously, for example, a loan payment that splits between principal, interest, and bank fees. It's cleaner than three separate entries.
What are adjusting entries and why are they important?
Adjusting entries record economic activity that happened during the period but wasn't captured in a regular transaction, like accrued wages, prepaid insurance used up, or depreciation. Without them, your financial statements misrepresent the true period activity.
How do closing entries work?
At year end, closing entries zero out all temporary accounts (revenue, expenses, dividends) by transferring their balances to Retained Earnings. This resets the income statement accounts to zero for the new period while preserving the cumulative equity balance.
Is it possible to have a journal entry with only credits or only debits?
No, every valid journal entry must have at least one debit and one credit that balance. An entry with only debits or only credits violates the double-entry system and will cause your trial balance to fail.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Want Period-End Entries Right?
Book a free consultation and we will handle the adjusting and closing entries.