
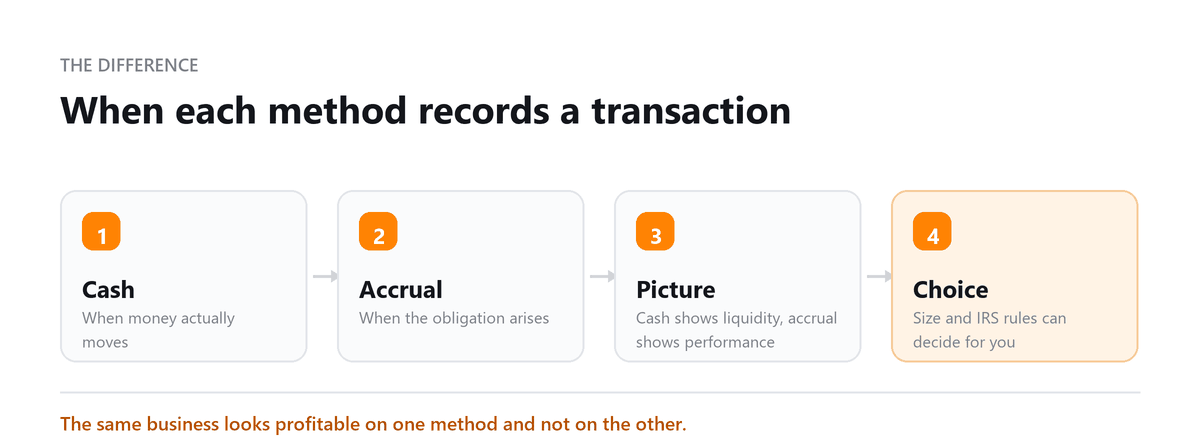
Cash basis accounting records transactions when cash is exchanged while accrual accounting records revenues and expenses when they are incurred, regardless of when the cash is actually received or paid.
For a solo freelancer who is paid upon delivery of a service, the difference between the two methods would show up in the income figures by a small amount. However, for a company that sends out invoices 30 days in advance and receives payments due in 30 days, the two methods could show completely different results for the same month, one indicating healthy growth and the other showing no income at all until the next year’s billing.
Most small businesses choose to be on the cash accounting method because it is simple to implement and provides real flexibility in terms of tax planning. And, despite the tax benefits, many companies stay on this method for too long, and the issue isn’t a tax code one, it is a strategic one. It’s because these companies are not taking into account their financial position a month or two in arrears.
And there is a third option, which is rarely explored, companies don’t have to be on the same accounting method for tax and operating purposes. And here’s where the actual answer lies for many companies that were considering switching accounting methods.
Cash basis stops being adequate once there's a meaningful gap between doing the work and getting paid which for most B2B businesses is from the first invoice. You look at a strong month and it's really last month's collections; you look at a weak one and the work was done, the money just hasn't landed. Owners make hiring and spending decisions on that, and the picture they're reading is two months out of date.
Ankit Sarawagi, CPA, CA, MBA · LinkedInCore Definitions
- Cash Basis Accounting: Revenue is recognised when cash is received. Expenses are recognised when cash is paid. Simple to maintain. Gives a real-time picture of cash position. Does not show money owed to you (receivables) or owed by you (payables) until cash moves.
- Accrual Basis Accounting: Revenue is recognised when it is earned (when the service is delivered or the product is sold), regardless of when payment arrives. Expenses are recognised when they are incurred, regardless of when paid. More complex. Provides a more accurate picture of financial performance over a period.
Side-by-Side Example
Scenario: You deliver $10,000 of consulting services in December. The client pays in January.
| Cash Basis | Accrual Basis | |
|---|---|---|
| When Revenue Is Recorded | January, when payment is received | December, when services are delivered |
| December P&L Shows | $0 revenue (cash not yet received) | $10,000 revenue (earned) |
| January P&L Shows | $10,000 revenue (cash received) | $0 revenue (already recorded in December) |
| Balance Sheet (Dec) | No accounts receivable | Accounts receivable: $10,000 |
| Accuracy | December looks understated; January looks overstated | December accurately reflects work done |
Comparison Table
| Dimension | Cash Basis | Accrual Basis |
|---|---|---|
| Revenue Recognition | When cash received | When earned (invoice issued / service delivered) |
| Expense Recognition | When cash paid | When incurred (bill received / cost matched to revenue) |
| Complexity | Simple, easier for small businesses | More complex, requires tracking A/R, A/P, prepayments, accruals |
| Financial Statements | P&L reflects cash timing, not performance | P&L reflects true economic performance |
| Tax Planning | More timing flexibility, defer income, accelerate expenses | Less timing flexibility, income tied to delivery, not receipt |
| Required For | Businesses under $30M average annual gross receipts (IRS threshold) | C-Corporations and businesses over the IRS gross receipts threshold; required for GAAP reporting |
| Best For | Sole traders, micro-businesses, service businesses with immediate payment | Any business with significant receivables, payables, or inventory; any business seeking investment or bank financing |
| GAAP Compliant | No, cash basis is not GAAP | Yes, accrual is the GAAP standard |
IRS Rules on Method Choice
Switching accounting methods requires IRS approval via Form 3115. This is not a simple change, it has tax implications. Always consult a CPA before changing methods.
What cash basis hides
The specific ways a cash-basis picture misleads, which is what makes this matter:
Profit that's already spent. A strong cash month can be collections on work done months ago, while this month's work sits unbilled. Owners hire and commit on the strength of it.
A payables backlog. Bills you've received and not paid don't exist on cash basis. A business can look profitable while carrying two months of unpaid supplier invoices.
Seasonality that isn't there. Cash timing creates peaks and troughs that have nothing to do with trading. You can't tell a genuinely slow month from a slow-paying one.
Margin you can't read. Costs land when paid rather than when they relate to revenue, so gross margin by period becomes close to meaningless, particularly with inventory or subcontractors.
The year-end distortion. Deferring December invoices and prepaying January expenses is legitimate tax planning on cash basis. It also makes your December and January figures useless for comparison, and it's why year-on-year trends in cash-basis books often make no sense.
Which Should You Use?
| Choose Cash Basis if… | Choose Accrual Basis if… |
|---|---|
| You are a freelancer or very small service business with immediate payment | You invoice clients on 30/60/90-day terms, receivables are significant |
| You want simple bookkeeping, minimal accounting overhead | You carry inventory, matching cost of goods to revenue requires accrual |
| Your revenue and expenses occur simultaneously | You are a C-Corporation (required by IRS above gross receipts threshold) |
| Tax simplicity is the priority | You are seeking bank financing or investment, lenders and investors require GAAP (accrual) financials |
| You stay under the IRS gross receipts threshold | You want accurate period-over-period performance comparison |
Cash basis if you're a freelancer or small service business paid at or near delivery, your bookkeeping capacity is limited, you value the tax timing flexibility, and nobody external is reading your statements.
Accrual basis if you invoice on credit terms, you carry inventory, you're seeking financing or investment, you're a C-Corporation above the threshold, or you want period-to-period comparisons that mean something.
Both- cash for tax, accrual for management: if you qualify for cash basis and want the timing flexibility, but need to actually understand your business. For most growing small businesses this is the right answer, and it costs nothing beyond keeping proper books.
The option nobody mentions: use both
This is the answer for a large share of readers and it's absent from almost every comparison of these two.
Your tax method and your management reporting don't have to match. You can file on a cash basis, taking the timing flexibility, while running your internal reporting on accrual so you can actually see how the business is performing.
QuickBooks and Xero both switch between cash and accrual views of the same data. If your bookkeeping records invoices and bills properly with receivables and payables tracked both views are available at a click, and nothing extra is required.
What that requires in practice: raise invoices in the system when you issue them, enter supplier bills when they arrive rather than when you pay them, and keep AR and AP current. That's ordinary good bookkeeping. The accrual view comes free with it.
So for many businesses the real question isn't "which method." It's whether your books are detailed enough to produce both. If they're not, that's the thing to fix, the method choice follows from it.
Book a free consultation and we will tell you which one fits and why.
Frequently Asked Questions
Can a small business use accrual even if not required to?
Yes, and many should. Any business invoicing on credit terms or carrying inventory gets a far more accurate picture from accrual. The extra bookkeeping is manageable in modern software with someone maintaining it properly. Whether you also change your tax method is a separate decision, you can run accrual internally while continuing to file on cash basis.
How do I switch from cash to accrual for tax?
Form 3115 plus a Section 481(a) adjustment for the cumulative difference. Positive adjustments generally spread over several years; negative ones are usually taken immediately. It's a CPA exercise, not a DIY one, and worth confirming you need the tax change rather than just better internal reporting.
Which method shows my business more accurately?
Accrual, for performance. Cash, for liquidity. Which you need depends on the question, a business can be profitable on accrual and unable to make payroll, which is exactly why looking at only one is risky. If your books support both views, use both.
Will my bank or investors care which method I use?
Yes. Lenders and investors generally want accrual financials, because cash-basis statements don't show what you're owed or what you owe. If financing is on the horizon, get accrual reporting running well before you need to hand statements over reconstructing it under time pressure is not where you want to be.
Does cash basis save me tax?
It gives you timing flexibility, not a permanent saving deferring income and accelerating expenses shifts tax between years rather than removing it. That's genuinely valuable in specific situations, such as an unusually high-income year. It's worth much less as a general strategy than the effort people put into it at every December.

Written by
Ankit Sarawagi, CPA, CA, MBA
Ankit leads the finance team at Profitjets, where he has worked with 500+ businesses across the US on bookkeeping, tax and CFO-level strategy. He writes about the habits that keep small business books accurate all year. Connect on LinkedIn
Free consultation
Picking a Method?
Book a free consultation and we will tell you which one fits and why.