
FIFO and LIFO are not statements about what physically leaves the warehouse, but rather assumptions about which units are sold. You can rotate inventory from oldest to newest while costing it newest to oldest. The method affects which purchase costs get charged to cost of goods sold, and therefore the amount of profit you report and the amount of tax you owe.
FIFO assumes that the oldest inventory is sold first. So when costs are rising (as they often do), this will result in lower costs of goods sold, higher profits, higher taxes owed, and a balance sheet that reflects inventory at roughly current cost.
LIFO assumes that the newest inventory is sold first. This results in higher costs of goods sold, lower profits, lower taxes owed, and inventory on the balance sheet that is significantly under-priced. LIFO earns its complexity where inventory costs rise persistently and you hold a lot of it: auto dealers, fuel and heating oil distributors, industrial and hardware wholesalers.
Before moving on: for most small businesses this choice is either already made or largely irrelevant. If your costs are stable, or your inventory turns over quickly, or you carry only small amounts of inventory, there's not much difference between the two methods and the added complexity of LIFO is not justified. The section below on when this actually matters is worth reading before diving into the rest of this post.
FIFO is clearly better when you're raising money or borrowing, because a lender looking at LIFO inventory sees a balance sheet carrying stock at prices from years ago, and it makes your asset position look weaker than it is. Tax deferral is worth less than a loan you didn't get.
Anu Gupta, CA, EA, B.Tech · LinkedInCore Definitions
- FIFO (First-In, First-Out): The oldest inventory items are assumed to be sold first. In a period of rising prices, FIFO results in lower COGS (older, cheaper costs), higher gross profit, and higher taxable income but the balance sheet shows inventory at a more current, realistic value.
- LIFO (Last-In, First-Out): The most recently purchased inventory is assumed to be sold first. In a period of rising prices, LIFO results in higher COGS (newer, more expensive costs), lower gross profit, lower taxable income, and a balance sheet that may understate the true current value of inventory (the 'LIFO reserve').
- IMPORTANT: LIFO is permitted under US GAAP but is PROHIBITED under IFRS (International Financial Reporting Standards). Businesses that report under IFRS, including most companies outside the US, cannot use LIFO. US public companies that use LIFO for tax purposes must also use LIFO for financial reporting (the 'LIFO conformity rule').
Numerical Example
Scenario: You buy 100 units at $10 (older batch) and 100 units at $12 (newer batch). You sell 100 units.
| FIFO | LIFO | |
|---|---|---|
| Units Sold Assumed | 100 oldest units (bought at $10) | 100 newest units (bought at $12) |
| COGS | 100 × $10 = $1,000 | 100 × $12 = $1,200 |
| Remaining Inventory Value | 100 units at $12 = $1,200 (current cost) | 100 units at $10 = $1,000 (older, understated) |
| Gross Profit (on $1,500 revenue) | $1,500 − $1,000 = $500 | $1,500 − $1,200 = $300 |
| Taxable Income (simplified) | Higher, $500 | Lower, $300 |
| Tax Paid (21% corporate rate) | $105 | $63 |
| Balance Sheet Inventory | More accurate (current cost) | Understated (old costs remain) |
Pros and Cons
| FIFO | LIFO | |
|---|---|---|
| Tax Impact (inflation) | Higher taxable income, higher tax | Lower taxable income, tax deferral advantage |
| Balance Sheet Accuracy | Inventory at near-current values, more accurate | Inventory may be significantly understated ('LIFO reserve') |
| Profit Reporting | Higher reported profit, may look better to investors | Lower reported profit, may concern investors unfamiliar with LIFO |
| IFRS Compliance | Permitted globally | PROHIBITED under IFRS, US GAAP only |
| Simplicity | Simpler to administer | More complex, LIFO reserve tracking, conformity rule |
| Best For | Businesses wanting balance sheet accuracy; IFRS reporters; most businesses outside US | US businesses with rising inventory costs wanting to defer tax (e.g. oil, auto dealers, hardware retailers) |
The LIFO Reserve
When a company uses LIFO, the difference between the value of inventory under FIFO and LIFO is called the LIFO Reserve. It represents the cumulative tax deferral. A large LIFO reserve means the company has deferred significant taxes over many years but also holds inventory on its balance sheet at very old, understated cost values. Analysts typically adjust for the LIFO reserve when comparing companies using different inventory methods.
Which Method Should You Choose?
| Choose FIFO if… | Choose LIFO if… |
|---|---|
| Your business reports under IFRS (LIFO is not permitted) | You are a US business with rising inventory costs and a significant tax liability |
| You want your balance sheet to reflect current inventory values | Your inventory does not deteriorate or expire (otherwise FIFO is operationally logical) |
| You are seeking investment or loans and want clean, internationally comparable financials | You are in oil/gas, auto, retail hardware, industries where LIFO has a long, established use |
| Your inventory costs are stable or declining (LIFO provides no tax benefit then) | You have the accounting infrastructure to track LIFO reserve and manage the conformity rule |
Does this decision actually matter for you?
Honest triage, because most readers of this page will conclude it doesn't.
- It matters if: you hold substantial inventory relative to your revenue, your purchase costs are rising persistently rather than fluctuating, you have the accounting capability to maintain LIFO layers, and the deferral is large enough to justify the administration.
- It matters much less if: your inventory turns quickly, your costs are flat or falling, LIFO gives you nothing then and can actively hurt, you hold little stock, or you're raising money or borrowing in the near term.
- And it's not a choice at all if: you report under IFRS, in which case FIFO or weighted average is your only option. For most US small businesses this is irrelevant, so don't let it dominate the decision.
Which to choose FIFO vs LIFO
FIFO if you want a balance sheet that reflects reality, you're seeking investment or lending, your costs are stable or falling, your inventory turns fast, or you simply don't want the administrative overhead. This is the right answer for most businesses.
LIFO if you're a US business with persistently rising costs and substantial inventory, you have the accounting infrastructure for it, you're in an industry where it's long established, and you're comfortable with lower reported profit in your published statements.
Weighted average if your inventory is fungible, your costs fluctuate rather than trend, and you want something simpler than LIFO that's accepted everywhere.
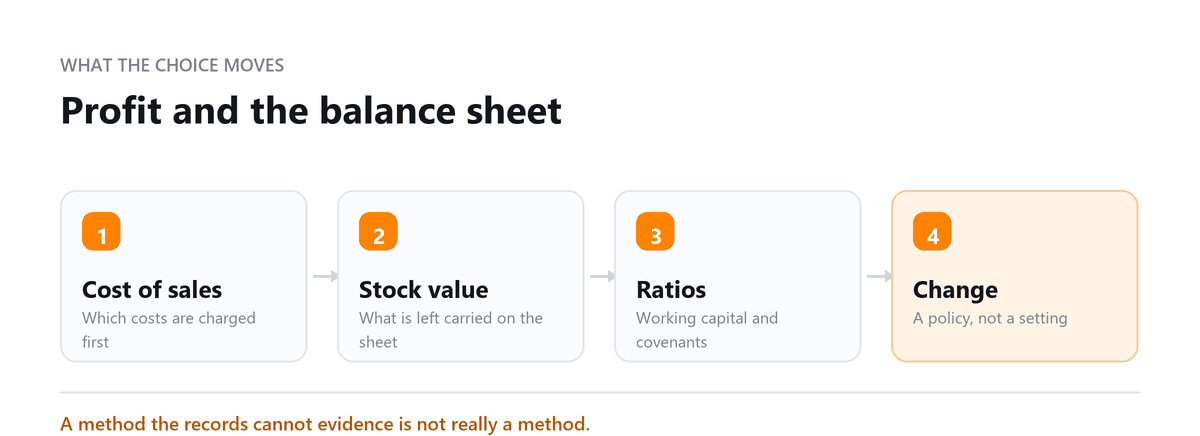
Don't change methods for a one-off tax outcome. This is an accounting policy decision with multi-year consequences and a difficult exit, not a lever to pull in a good year.
Book a free consultation and we will get the costing right.
Frequently Asked Questions
Can I switch between LIFO and FIFO?
Yes, with IRS approval via Form 3115 for a change in accounting method. Leaving LIFO is the expensive direction,the accumulated LIFO reserve generally comes into taxable income, which can be a substantial one-off hit, though spreading provisions may apply. Electing into LIFO requires Form 970 and brings the conformity rule with it. Neither is casual; take advice before either.
Is LIFO actually simpler to elect than to leave?
No, and this gets stated backwards frequently. Electing LIFO commits you to maintaining cost layers, tracking the reserve, and using LIFO in your financial statements as well as your return. Leaving is harder still, because the reserve becomes taxable. FIFO is the low-commitment position in both directions.
Why does LIFO exist if it understates inventory?
It was permitted primarily as a tax deferral mechanism, letting businesses match current costs against current revenue during inflationary periods. FASB considered eliminating it during IFRS convergence work and didn't. It remains available under US GAAP and prohibited under IFRS.
What's a LIFO liquidation?
When inventory quantities fall below prior-year levels, old low-cost layers flow into COGS. Profit and tax both spike, often in a year the business is already struggling because the reason inventory fell is usually that sales fell. It's the main risk of a long-standing LIFO position and it's poorly understood by the businesses carrying it.
What if my costs are falling?
LIFO works against you: newer, cheaper costs go to COGS, raising taxable income. In a deflationary environment FIFO produces the tax advantage LIFO would in an inflationary one. Which is why the method should follow your actual cost trend rather than a general assumption that LIFO saves tax.

Written by
Anu Gupta, CA, EA, B.Tech
Anu works with US businesses on tax and entity questions at Profitjets, from choosing a structure to the filings that follow it. She writes about the decisions owners make once and then live with for years. Connect on LinkedIn
Free consultation
Inventory Numbers Not Adding Up?
Book a free consultation and we will get the costing right.